#termmax @TermMax
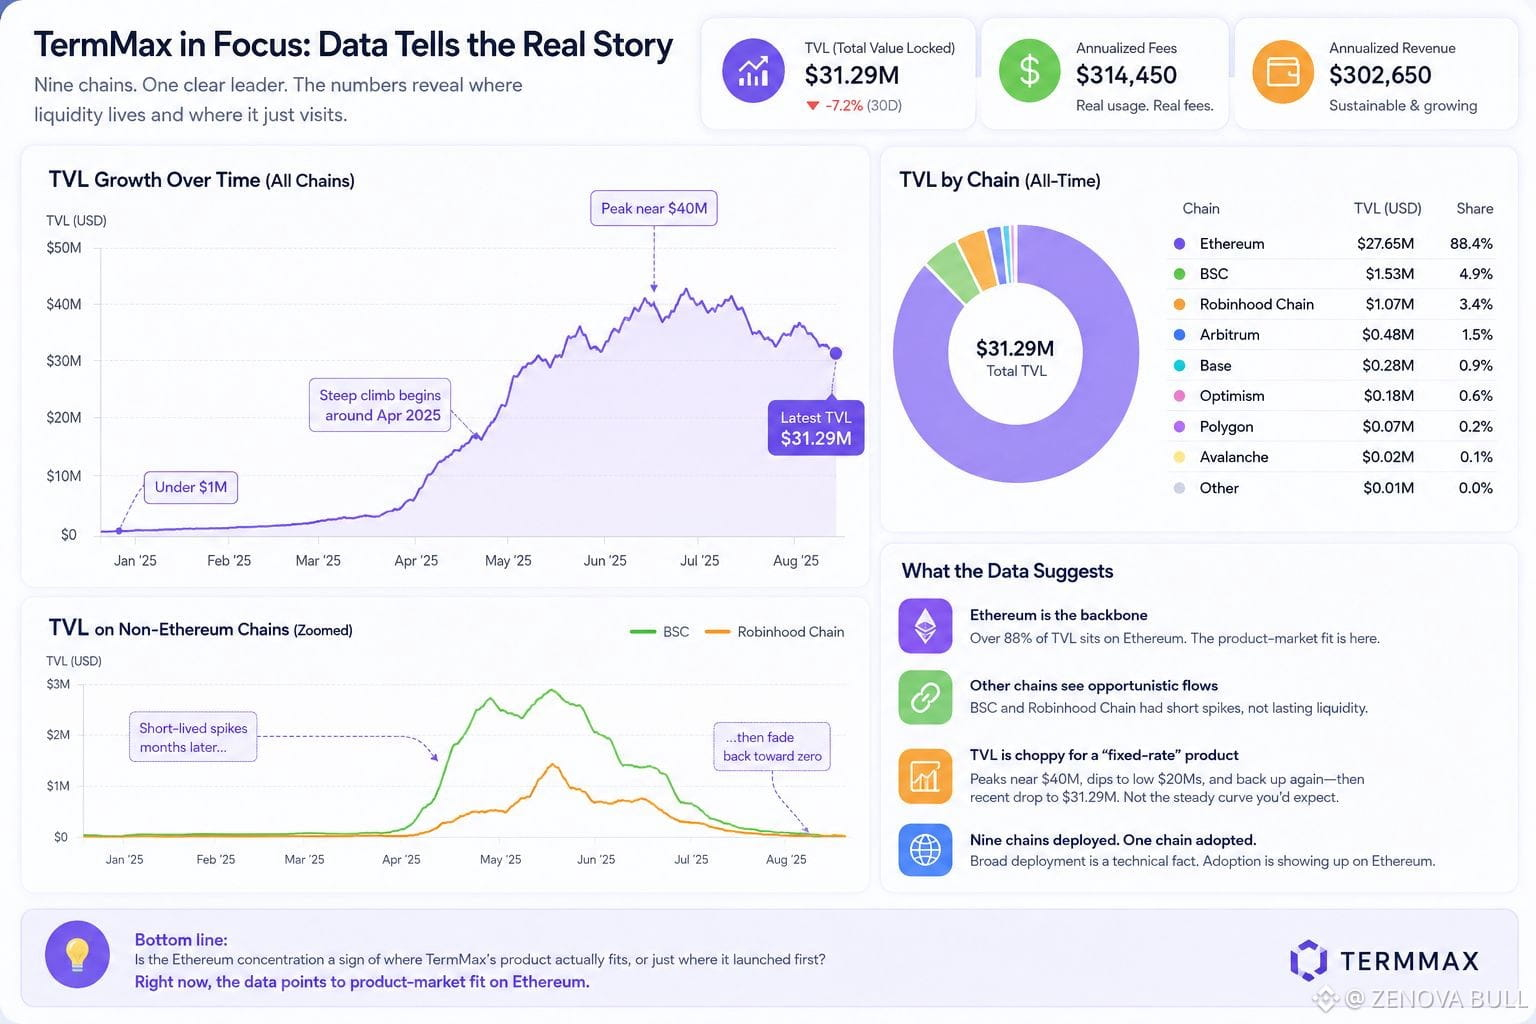
What caught my attention was the chain breakdown on TermMax's TVL dashboard. Nine chains are listed, but scroll through the actual chart and it's basically an Ethereum story — a steep climb from under $1M to over $30M starting around April 2025, while BSC and Robinhood Chain show up as short-lived spikes months later before fading back toward zero. Nine chains sounds like broad deployment. The liquidity says otherwise.
I went looking for what's driving the fees, since TermMax markets itself as fixed-rate lending plus options. Annualized fees sit at $314,450, revenue close behind — respectable for a protocol this size, and it suggests real usage, not just incentivized TVL sitting idle. But the TVL chart itself is choppier than I expected for a "fixed-rate" product: peaks near $40M, drops into the low $20Ms, climbs again, then a sharp drop near the most recent data point down to $31.29M. Fixed-rate lending should produce steadier curves than this. The volatility looks more like a protocol whose liquidity is opportunistic — bridging in for yield windows, then leaving.
I'm not saying the multichain expansion is fake. The deployments exist on-chain. But if BSC and Robinhood Chain together never held more than a few million before retreating, "nine chains" is a technical fact more than an adoption one.
Is the Ethereum concentration a sign of where TermMax's product actually fits, or just where it launched first?
$ACE
$ONG
$BOME
What caught my attention was the chain breakdown on TermMax's TVL dashboard. Nine chains are listed, but scroll through the actual chart and it's basically an Ethereum story — a steep climb from under $1M to over $30M starting around April 2025, while BSC and Robinhood Chain show up as short-lived spikes months later before fading back toward zero. Nine chains sounds like broad deployment. The liquidity says otherwise.
I went looking for what's driving the fees, since TermMax markets itself as fixed-rate lending plus options. Annualized fees sit at $314,450, revenue close behind — respectable for a protocol this size, and it suggests real usage, not just incentivized TVL sitting idle. But the TVL chart itself is choppier than I expected for a "fixed-rate" product: peaks near $40M, drops into the low $20Ms, climbs again, then a sharp drop near the most recent data point down to $31.29M. Fixed-rate lending should produce steadier curves than this. The volatility looks more like a protocol whose liquidity is opportunistic — bridging in for yield windows, then leaving.
I'm not saying the multichain expansion is fake. The deployments exist on-chain. But if BSC and Robinhood Chain together never held more than a few million before retreating, "nine chains" is a technical fact more than an adoption one.
Is the Ethereum concentration a sign of where TermMax's product actually fits, or just where it launched first?
$ACE
$ONG
$BOME