
#retail
retail
51,428 views
149 Discussing
Hot
Latest

·
--
Article
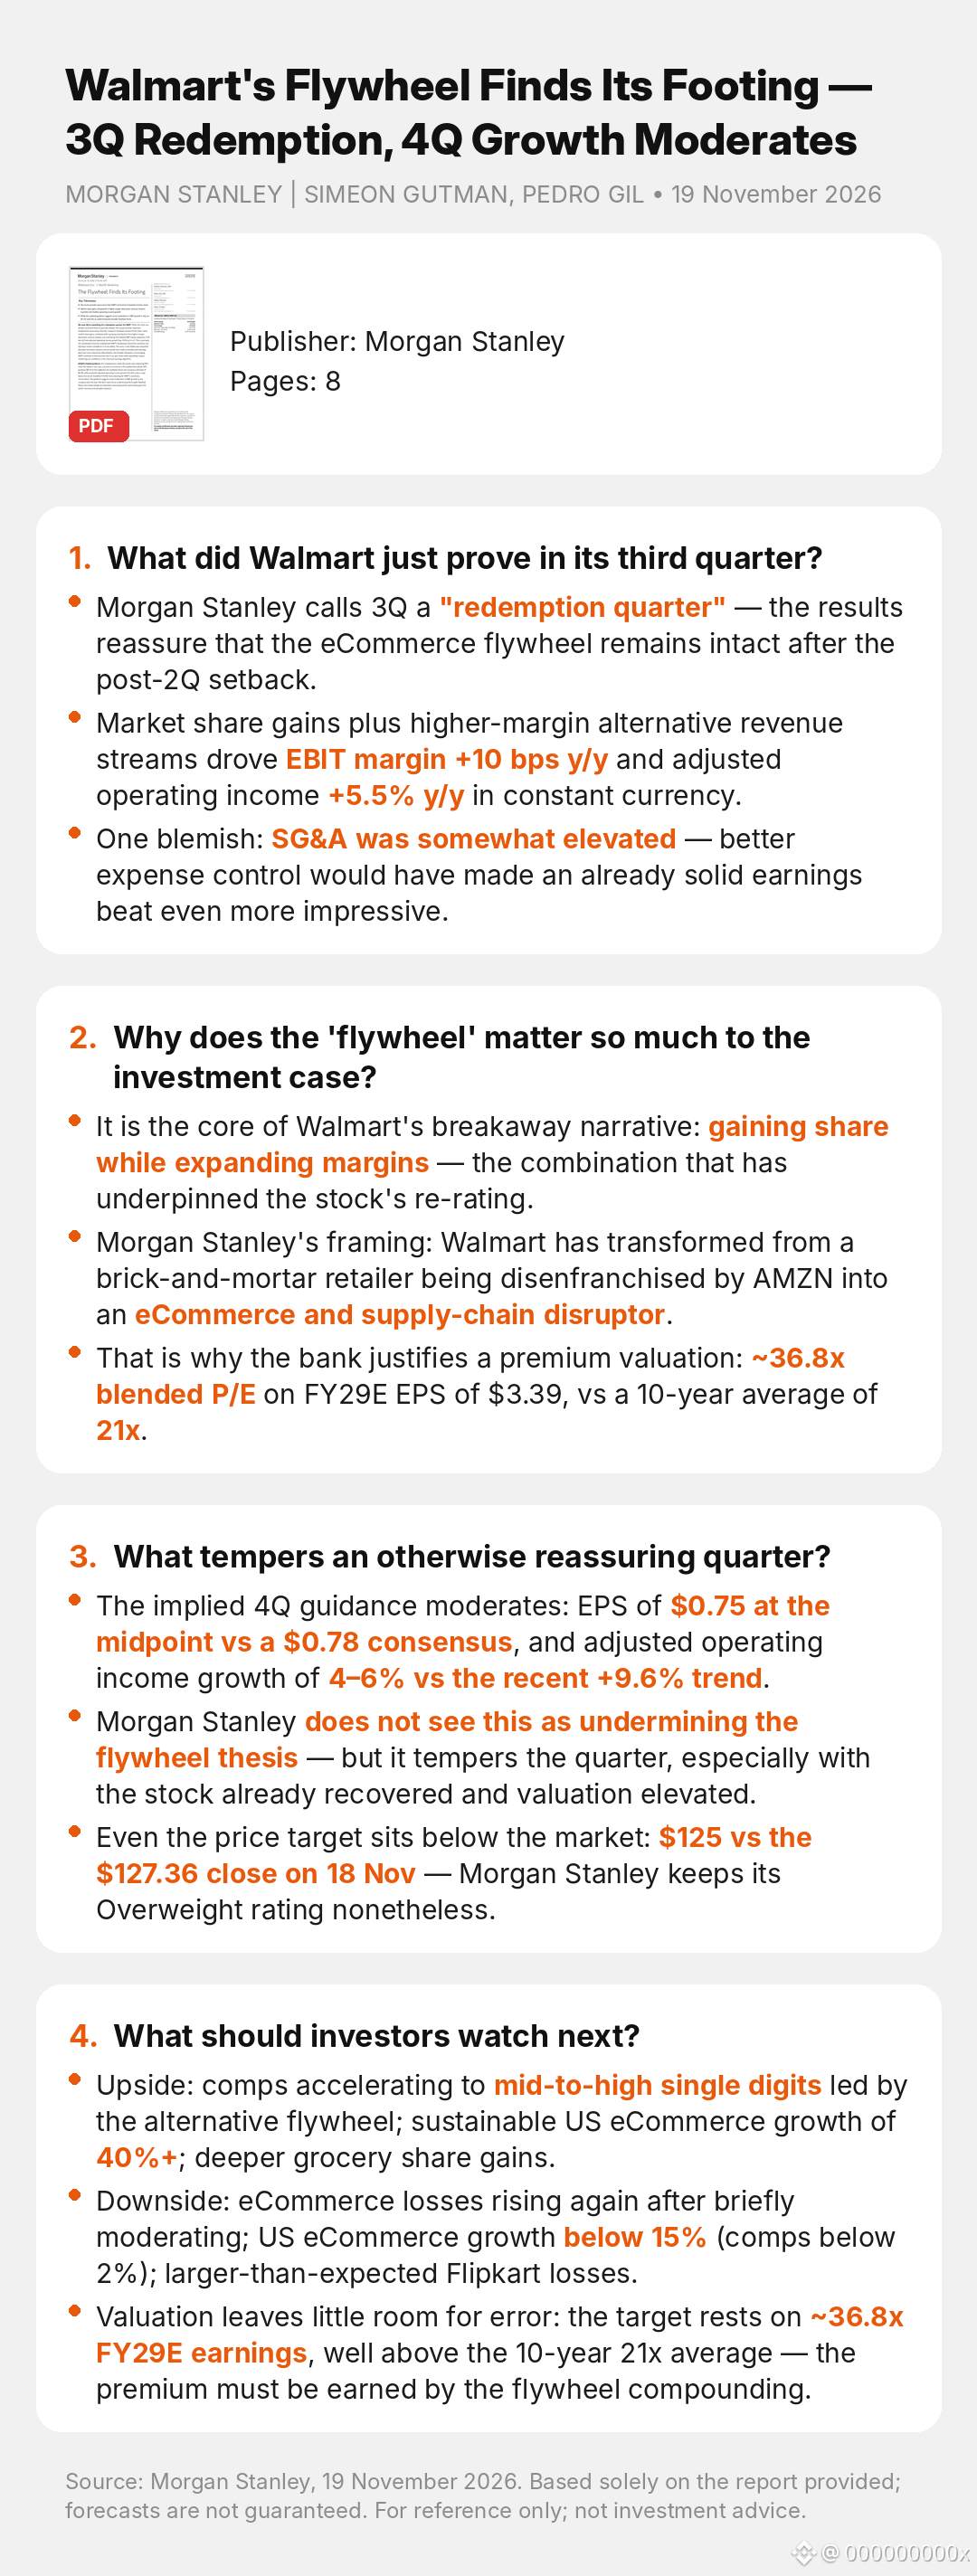
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth ModeratesWalmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
62

·
--
美国10月零售销售核心增长超预期,工业产出意外下滑
美国10月零售销售环比增长0.2%,至7,482亿美元,同比增长6.8%。核心零售销售(剔除汽车、汽油、建材和餐饮)增长0.6%,高于预期,9月数据上修至0.5%。汽车经销商销售额下降1.6%,拖累整体数据。
工业产出环比下降0.4%,低于预期的增长0.1%,主要受公用事业产出大降4.3%拖累;制造业产出增长0.3%,好于预期;产能利用率为76.4%。
建筑商信心降至14年低点:11月NAHB住宅建筑商信心指数降至25,低于预期的29,为2012年4月以来最低;46%的建筑商正在降价。
市场方面,美元指数升至103.6附近,创4月以来新高;10年期美债收益率维持在5.14%附近。截至今晨,CME FedWatch显示,12月加息25个基点的概率为96.8%。美联储10月会议纪要将于北京时间11月19日凌晨3点公布。
$BTC $ETH
#fed #retail
美国10月零售销售核心增长超预期,工业产出意外下滑
美国10月零售销售环比增长0.2%,至7,482亿美元,同比增长6.8%。核心零售销售(剔除汽车、汽油、建材和餐饮)增长0.6%,高于预期,9月数据上修至0.5%。汽车经销商销售额下降1.6%,拖累整体数据。
工业产出环比下降0.4%,低于预期的增长0.1%,主要受公用事业产出大降4.3%拖累;制造业产出增长0.3%,好于预期;产能利用率为76.4%。
建筑商信心降至14年低点:11月NAHB住宅建筑商信心指数降至25,低于预期的29,为2012年4月以来最低;46%的建筑商正在降价。
市场方面,美元指数升至103.6附近,创4月以来新高;10年期美债收益率维持在5.14%附近。截至今晨,CME FedWatch显示,12月加息25个基点的概率为96.8%。美联储10月会议纪要将于北京时间11月19日凌晨3点公布。
$BTC $ETH
#fed #retail
美国10月零售销售环比增长0.2%,至7,482亿美元,同比增长6.8%。核心零售销售(剔除汽车、汽油、建材和餐饮)增长0.6%,高于预期,9月数据上修至0.5%。汽车经销商销售额下降1.6%,拖累整体数据。
工业产出环比下降0.4%,低于预期的增长0.1%,主要受公用事业产出大降4.3%拖累;制造业产出增长0.3%,好于预期;产能利用率为76.4%。
建筑商信心降至14年低点:11月NAHB住宅建筑商信心指数降至25,低于预期的29,为2012年4月以来最低;46%的建筑商正在降价。
市场方面,美元指数升至103.6附近,创4月以来新高;10年期美债收益率维持在5.14%附近。截至今晨,CME FedWatch显示,12月加息25个基点的概率为96.8%。美联储10月会议纪要将于北京时间11月19日凌晨3点公布。
$BTC $ETH
#fed #retail
227
🌐 Institutional vs Retail: Who's Right About Crypto?
On July 1, 2026, the split between institutional and retail sentiment is striking. Institutions are pulling $345M from ETH ETFs while retail volume holds steady.
Historically, institutions are trend-followers while retail traders are contrarian. Neither group is right — they're playing different timeframes. Institutions manage risk; retail speculates on mean reversion. The most successful investors follow the data, not the crowd.
📌 Key Takeaway:
The institution-versus-retail split ($345M ETH ETF outflows vs steady retail volume) reflects different timeframes, not different convictions.
#Institutional #Retail #MarketSentiment
#BinanceAlphaAlert
🌐 Institutional vs Retail: Who's Right About Crypto?
On July 1, 2026, the split between institutional and retail sentiment is striking. Institutions are pulling $345M from ETH ETFs while retail volume holds steady.
Historically, institutions are trend-followers while retail traders are contrarian. Neither group is right — they're playing different timeframes. Institutions manage risk; retail speculates on mean reversion. The most successful investors follow the data, not the crowd.
📌 Key Takeaway:
The institution-versus-retail split ($345M ETH ETF outflows vs steady retail volume) reflects different timeframes, not different convictions.
#Institutional #Retail #MarketSentiment
#BinanceAlphaAlert
On July 1, 2026, the split between institutional and retail sentiment is striking. Institutions are pulling $345M from ETH ETFs while retail volume holds steady.
Historically, institutions are trend-followers while retail traders are contrarian. Neither group is right — they're playing different timeframes. Institutions manage risk; retail speculates on mean reversion. The most successful investors follow the data, not the crowd.
📌 Key Takeaway:
The institution-versus-retail split ($345M ETH ETF outflows vs steady retail volume) reflects different timeframes, not different convictions.
#Institutional #Retail #MarketSentiment
#BinanceAlphaAlert
54
🚨 STOCKS | SHEIN Just Crashed 14% — And Its Ultra-Cheap Fashion Model Is Under Pressure
One of the world’s biggest online retailers is getting a brutal reality check.
Shein shares plunged as much as 14% today in Hong Kong, hitting a record low after the company released its first quarterly results since going public on September 1.
The numbers explain the selloff:
Adjusted profit: $228M → down 67% YoY
Operating margin: 2.1% → down from 6.2%
Revenue growth: just 0.9%
And two of SHEIN’s most important markets are weakening:
Europe sales: −13.9%
U.S. sales: −6%
Why does this matter?
SHEIN built its global advantage around an extremely efficient formula:
Cheap products → direct shipping → massive volume
But that model is becoming more expensive.
Higher freight costs linked to Middle East tensions, changing import rules and weaker demand after price increases are now squeezing margins.
Fulfillment costs alone jumped 18.1%.
And today’s market reaction is significant.
SHEIN was valued around $26B at its September 1 IPO.
After today’s drop, its market value is roughly:
$17 BILLION.
That’s nearly $9B of value erased in less than a month.
What to watch next:
Black Friday + Christmas demand
European pricing
Freight costs
Profit margins
The bigger question:
Was SHEIN’s ultra-low-cost model built for a world of cheap global shipping — and what happens when that world disappears?
#Stocks #SHEIN #Retail
🚨 STOCKS | SHEIN Just Crashed 14% — And Its Ultra-Cheap Fashion Model Is Under Pressure
One of the world’s biggest online retailers is getting a brutal reality check.
Shein shares plunged as much as 14% today in Hong Kong, hitting a record low after the company released its first quarterly results since going public on September 1.
The numbers explain the selloff:
Adjusted profit: $228M → down 67% YoY
Operating margin: 2.1% → down from 6.2%
Revenue growth: just 0.9%
And two of SHEIN’s most important markets are weakening:
Europe sales: −13.9%
U.S. sales: −6%
Why does this matter?
SHEIN built its global advantage around an extremely efficient formula:
Cheap products → direct shipping → massive volume
But that model is becoming more expensive.
Higher freight costs linked to Middle East tensions, changing import rules and weaker demand after price increases are now squeezing margins.
Fulfillment costs alone jumped 18.1%.
And today’s market reaction is significant.
SHEIN was valued around $26B at its September 1 IPO.
After today’s drop, its market value is roughly:
$17 BILLION.
That’s nearly $9B of value erased in less than a month.
What to watch next:
Black Friday + Christmas demand
European pricing
Freight costs
Profit margins
The bigger question:
Was SHEIN’s ultra-low-cost model built for a world of cheap global shipping — and what happens when that world disappears?
#Stocks #SHEIN #Retail
One of the world’s biggest online retailers is getting a brutal reality check.
Shein shares plunged as much as 14% today in Hong Kong, hitting a record low after the company released its first quarterly results since going public on September 1.
The numbers explain the selloff:
Adjusted profit: $228M → down 67% YoY
Operating margin: 2.1% → down from 6.2%
Revenue growth: just 0.9%
And two of SHEIN’s most important markets are weakening:
Europe sales: −13.9%
U.S. sales: −6%
Why does this matter?
SHEIN built its global advantage around an extremely efficient formula:
Cheap products → direct shipping → massive volume
But that model is becoming more expensive.
Higher freight costs linked to Middle East tensions, changing import rules and weaker demand after price increases are now squeezing margins.
Fulfillment costs alone jumped 18.1%.
And today’s market reaction is significant.
SHEIN was valued around $26B at its September 1 IPO.
After today’s drop, its market value is roughly:
$17 BILLION.
That’s nearly $9B of value erased in less than a month.
What to watch next:
Black Friday + Christmas demand
European pricing
Freight costs
Profit margins
The bigger question:
Was SHEIN’s ultra-low-cost model built for a world of cheap global shipping — and what happens when that world disappears?
#Stocks #SHEIN #Retail
119

·
--
Bullish
DICK’S SPORTING GOODS SLIDES AFTER CUTTING 2026 OUTLOOK
📉 DICK’S Sporting Goods reported Q2 revenue of $5.59 billion, up 53.2% YoY, largely driven by the Foot Locker consolidation. Adjusted EPS came in at $3.53, below expectations of around $3.76.
👟 DICK’S core business remained resilient, with comparable sales up 4.9%, while Foot Locker posted a 3.6% decline. The divergence suggests that most of the current pressure is concentrated within the Foot Locker segment.
📊 The company lowered its full-year EPS outlook to $11–12 and operating income guidance to $1.45–1.55 billion. Foot Locker comparable sales guidance was also cut to -2% to 0% as the footwear and apparel market becomes increasingly promotional.
⚠️ DKS shares fell about 30% following the report. The sharp reaction reflects concerns over margin pressure and Foot Locker integration risks, even as DICK’S core operations continue to grow.
#Retail $DKS.US $BNB $ONDO
DICK’S SPORTING GOODS SLIDES AFTER CUTTING 2026 OUTLOOK
📉 DICK’S Sporting Goods reported Q2 revenue of $5.59 billion, up 53.2% YoY, largely driven by the Foot Locker consolidation. Adjusted EPS came in at $3.53, below expectations of around $3.76.
👟 DICK’S core business remained resilient, with comparable sales up 4.9%, while Foot Locker posted a 3.6% decline. The divergence suggests that most of the current pressure is concentrated within the Foot Locker segment.
📊 The company lowered its full-year EPS outlook to $11–12 and operating income guidance to $1.45–1.55 billion. Foot Locker comparable sales guidance was also cut to -2% to 0% as the footwear and apparel market becomes increasingly promotional.
⚠️ DKS shares fell about 30% following the report. The sharp reaction reflects concerns over margin pressure and Foot Locker integration risks, even as DICK’S core operations continue to grow.
#Retail $DKS.US $BNB $ONDO
📉 DICK’S Sporting Goods reported Q2 revenue of $5.59 billion, up 53.2% YoY, largely driven by the Foot Locker consolidation. Adjusted EPS came in at $3.53, below expectations of around $3.76.
👟 DICK’S core business remained resilient, with comparable sales up 4.9%, while Foot Locker posted a 3.6% decline. The divergence suggests that most of the current pressure is concentrated within the Foot Locker segment.
📊 The company lowered its full-year EPS outlook to $11–12 and operating income guidance to $1.45–1.55 billion. Foot Locker comparable sales guidance was also cut to -2% to 0% as the footwear and apparel market becomes increasingly promotional.
⚠️ DKS shares fell about 30% following the report. The sharp reaction reflects concerns over margin pressure and Foot Locker integration risks, even as DICK’S core operations continue to grow.
#Retail $DKS.US $BNB $ONDO
DKSUS-2.04%
142
·
--
🛒 COUCHE-TARD ANTICIPA PRESIÓN POR OFERTA DE ŻABKA 🏪
El CEO de Alimentation Couche-Tard anticipa que accionistas de Żabka Group SA exigirán una oferta superior a la propuesta actual de $8,700 millones de dólares, según reportó Bloomberg.
Pese a las tensiones esperadas sobre la valoración del activo, el ejecutivo canadiense confía en cerrar exitosamente la adquisición. El movimiento busca consolidar la expansión del gigante de conveniencia en Europa Central y Oriental, reforzando su red minorista.
La transacción queda sujeta al avance de las negociaciones de valor con la base de inversionistas de la cadena polaca.
#CoucheTard #Zabka #Retail #Finance
$BTC
{spot}(BTCUSDT)
$BNB
{spot}(BNBUSDT)
$ETH
{spot}(ETHUSDT)
🛒 COUCHE-TARD ANTICIPA PRESIÓN POR OFERTA DE ŻABKA 🏪
El CEO de Alimentation Couche-Tard anticipa que accionistas de Żabka Group SA exigirán una oferta superior a la propuesta actual de $8,700 millones de dólares, según reportó Bloomberg.
Pese a las tensiones esperadas sobre la valoración del activo, el ejecutivo canadiense confía en cerrar exitosamente la adquisición. El movimiento busca consolidar la expansión del gigante de conveniencia en Europa Central y Oriental, reforzando su red minorista.
La transacción queda sujeta al avance de las negociaciones de valor con la base de inversionistas de la cadena polaca.
#CoucheTard #Zabka #Retail #Finance
$BTC
$BNB
$ETH
El CEO de Alimentation Couche-Tard anticipa que accionistas de Żabka Group SA exigirán una oferta superior a la propuesta actual de $8,700 millones de dólares, según reportó Bloomberg.
Pese a las tensiones esperadas sobre la valoración del activo, el ejecutivo canadiense confía en cerrar exitosamente la adquisición. El movimiento busca consolidar la expansión del gigante de conveniencia en Europa Central y Oriental, reforzando su red minorista.
La transacción queda sujeta al avance de las negociaciones de valor con la base de inversionistas de la cadena polaca.
#CoucheTard #Zabka #Retail #Finance
$BTC
$BNB
$ETH
1
182
·
--
Bearish
🚨🔥 BALLENAS VS RETAIL 💣
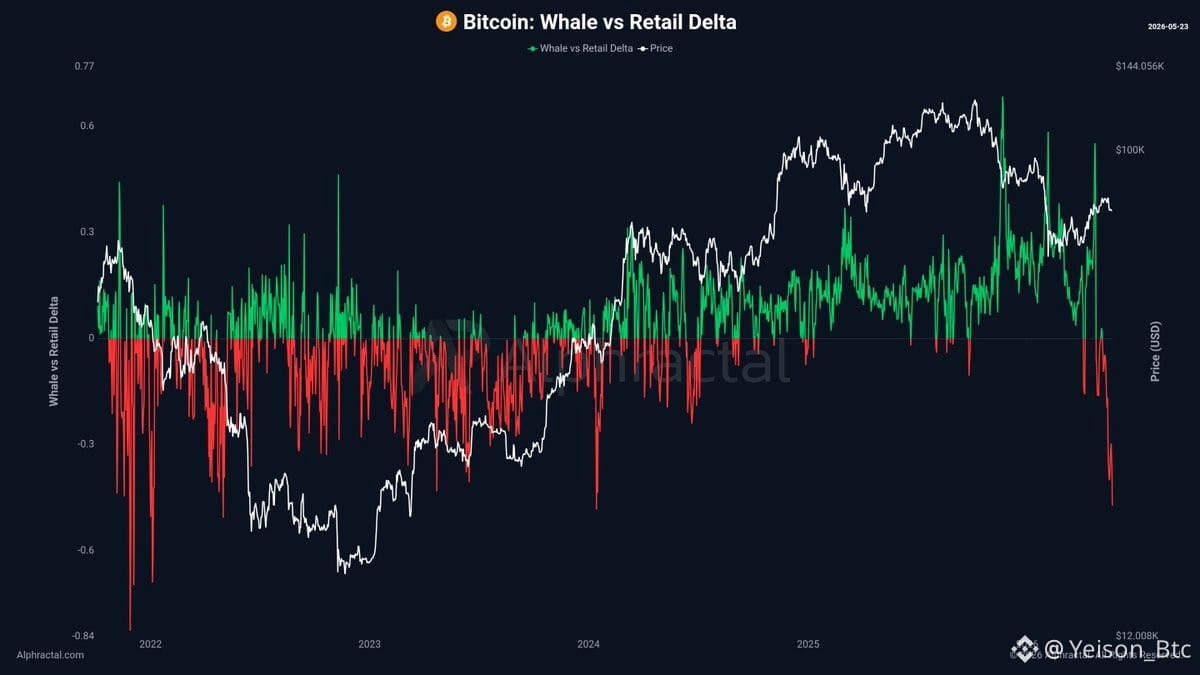
Si quieres ver la pelea real entre ballenas y retail antes que explote quédate por aquí parcero 👀💥 dale en la casilla amarilla para más
Mira este gráfico de #whale vs #retail Delta parce, las ballenas están acumulando posiciones cortas bien hijueputas mientras el retail sigue metido full #long como siempre 📉 no se cansan de perder dinero
🧠 Esto es clásico coño, las ballenas vendiendo o shorteando en la parte alta y dejando que los retail carguen el saco con apalancamiento
Cuando las ballenas se ponen en contra del retail el desenlace suele ser doloroso para los que están del lado equivocado 💀
El mercado está preparando una buena barrida de longs y va a doler verga
Tú crees que las ballenas van a liquidar a todo el retail pronto o esta vez se les revierte la jugada
Dime qué piensas abajo 👇🔥
{spot}(BTCUSDT)
🚨🔥 BALLENAS VS RETAIL 💣
Si quieres ver la pelea real entre ballenas y retail antes que explote quédate por aquí parcero 👀💥 dale en la casilla amarilla para más
Mira este gráfico de #whale vs #retail Delta parce, las ballenas están acumulando posiciones cortas bien hijueputas mientras el retail sigue metido full #long como siempre 📉 no se cansan de perder dinero
🧠 Esto es clásico coño, las ballenas vendiendo o shorteando en la parte alta y dejando que los retail carguen el saco con apalancamiento
Cuando las ballenas se ponen en contra del retail el desenlace suele ser doloroso para los que están del lado equivocado 💀
El mercado está preparando una buena barrida de longs y va a doler verga
Tú crees que las ballenas van a liquidar a todo el retail pronto o esta vez se les revierte la jugada
Dime qué piensas abajo 👇🔥
Si quieres ver la pelea real entre ballenas y retail antes que explote quédate por aquí parcero 👀💥 dale en la casilla amarilla para más
Mira este gráfico de #whale vs #retail Delta parce, las ballenas están acumulando posiciones cortas bien hijueputas mientras el retail sigue metido full #long como siempre 📉 no se cansan de perder dinero
🧠 Esto es clásico coño, las ballenas vendiendo o shorteando en la parte alta y dejando que los retail carguen el saco con apalancamiento
Cuando las ballenas se ponen en contra del retail el desenlace suele ser doloroso para los que están del lado equivocado 💀
El mercado está preparando una buena barrida de longs y va a doler verga
Tú crees que las ballenas van a liquidar a todo el retail pronto o esta vez se les revierte la jugada
Dime qué piensas abajo 👇🔥
1
2
1.2k

·
--
零售板块异动拉响警报!国芳集团一字板涨停,新华百货、东百集团等集体跟涨。这是消费复苏信号还是短期炒作?$CRO #ChineseStocks #Retail
Retail stocks heating up! Guofang Group surges to limit-up, Xinhua Dept and others follow. Retail recovery or just hype? $CRO #StockMarket #Retail
零售板块异动拉响警报!国芳集团一字板涨停,新华百货、东百集团等集体跟涨。这是消费复苏信号还是短期炒作?$CRO #ChineseStocks #Retail
Retail stocks heating up! Guofang Group surges to limit-up, Xinhua Dept and others follow. Retail recovery or just hype? $CRO #StockMarket #Retail
Retail stocks heating up! Guofang Group surges to limit-up, Xinhua Dept and others follow. Retail recovery or just hype? $CRO #StockMarket #Retail
21
·
--
📉 ÉXODO EN COREA: MINORISTAS LIQUIDAN $793 MDD EN ACCIONES EXTERNAS
La fuga de capital minorista en Corea del Sur se acelera. Durante la primera semana de junio, los inversores coreanos vendieron un neto de $793.67 millones de dólares en acciones extranjeras, prolongando una racha de retiros que inició en abril.
Lo esencial:
⚡ Presión en aumento: Las ventas de solo una semana ya superan los $469 millones de abril y rozan el récord de $939.77 millones de mayo.
🔄 Tercer mes de salida: De mantenerse el ritmo, junio consolidará el tercer mes consecutivo de abandono minorista al mercado de valores internacional.
🔥 El capital asiático huye de las bolsas tradicionales a velocidad récord, liberando una liquidez masiva que busca rendimientos alternativos.
#CoreaDelSur #StocksMarket #Retail #Binance
📊 ¿A DÓNDE VA ESA LIQUIDEZ?
La retirada de fondos de las acciones globales suele redirigir capital fresco hacia el mercado cripto, inyectando volumen en los principales soportes macro.
👇 Toca los gráficos aquí abajo para monitorear el flujo de dinero en tiempo real 👇
$ETH $BTC
{spot}(BTCUSDT)
{spot}(ETHUSDT)
📉 ÉXODO EN COREA: MINORISTAS LIQUIDAN $793 MDD EN ACCIONES EXTERNAS
La fuga de capital minorista en Corea del Sur se acelera. Durante la primera semana de junio, los inversores coreanos vendieron un neto de $793.67 millones de dólares en acciones extranjeras, prolongando una racha de retiros que inició en abril.
Lo esencial:
⚡ Presión en aumento: Las ventas de solo una semana ya superan los $469 millones de abril y rozan el récord de $939.77 millones de mayo.
🔄 Tercer mes de salida: De mantenerse el ritmo, junio consolidará el tercer mes consecutivo de abandono minorista al mercado de valores internacional.
🔥 El capital asiático huye de las bolsas tradicionales a velocidad récord, liberando una liquidez masiva que busca rendimientos alternativos.
#CoreaDelSur #StocksMarket #Retail #Binance
📊 ¿A DÓNDE VA ESA LIQUIDEZ?
La retirada de fondos de las acciones globales suele redirigir capital fresco hacia el mercado cripto, inyectando volumen en los principales soportes macro.
👇 Toca los gráficos aquí abajo para monitorear el flujo de dinero en tiempo real 👇
$ETH $BTC
La fuga de capital minorista en Corea del Sur se acelera. Durante la primera semana de junio, los inversores coreanos vendieron un neto de $793.67 millones de dólares en acciones extranjeras, prolongando una racha de retiros que inició en abril.
Lo esencial:
⚡ Presión en aumento: Las ventas de solo una semana ya superan los $469 millones de abril y rozan el récord de $939.77 millones de mayo.
🔄 Tercer mes de salida: De mantenerse el ritmo, junio consolidará el tercer mes consecutivo de abandono minorista al mercado de valores internacional.
🔥 El capital asiático huye de las bolsas tradicionales a velocidad récord, liberando una liquidez masiva que busca rendimientos alternativos.
#CoreaDelSur #StocksMarket #Retail #Binance
📊 ¿A DÓNDE VA ESA LIQUIDEZ?
La retirada de fondos de las acciones globales suele redirigir capital fresco hacia el mercado cripto, inyectando volumen en los principales soportes macro.
👇 Toca los gráficos aquí abajo para monitorear el flujo de dinero en tiempo real 👇
$ETH $BTC
1
136
#bestbuyq2revenuetopsestimatesliftsoutlook
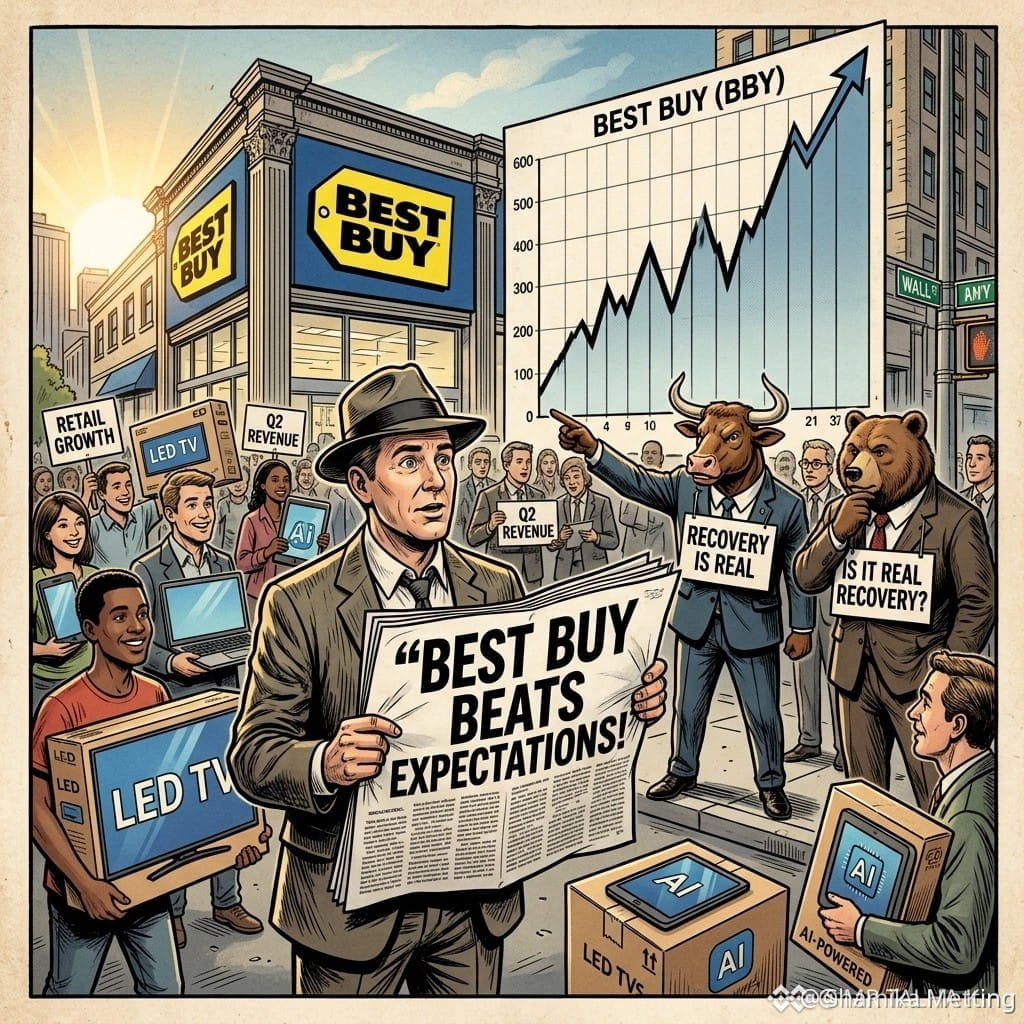
🚨 أفضل مشتريات تتفوق على التوقعات — هل انتعاش إلكترونيات المستهلك في الأفق؟ 📈🔥
قدّمت Best Buy نتائج أقوى من المتوقع للربع الثاني، إذ تجاوزت الإيرادات تقديرات وول ستريت مع ظهور بوادر تحسّن في الطلب عبر فئات إلكترونيات مهمة. 💻📺📱
🔥 أبرز النقاط:
💻 الطلب على الحوسبة يتحسن
📺 أجهزة التلفاز والأجهزة المنزلية تُظهر زخمًا
📱 منتجات الهاتف المحمول ما زالت مرنة
🤖 التكنولوجيا المدعومة بالذكاء الاصطناعي وتقنيات الجيل التالي تجذب الانتباه
📈 الإدارة رفعت توقعاتها للسنة بالكامل
🎯 ما الذي يجب أن يراقبه المتداولون بعد ذلك:
المبيعات المماثلة، هوامش الربح، طلب أجهزة AI-PC، اتجاهات التسوق خلال العطلات، والمنافسة في قطاع التجزئة.
إنّ التوجيهات المرفوعة تُعد إشارة ملحوظة بأن الإدارة ترى ظروفًا تتحسن في الفترة المقبلة. لكن السؤال الأكبر يبقى:
👀 هل هذه بداية تعافٍ أوسع في إلكترونيات المستهلك — أم مجرد ارتداد مؤقت؟
متابعة من فضلكم
#BBY #StockMarket #Retail
$BBY.US
$BTC
$BNB
#bestbuyq2revenuetopsestimatesliftsoutlook
🚨 أفضل مشتريات تتفوق على التوقعات — هل انتعاش إلكترونيات المستهلك في الأفق؟ 📈🔥
قدّمت Best Buy نتائج أقوى من المتوقع للربع الثاني، إذ تجاوزت الإيرادات تقديرات وول ستريت مع ظهور بوادر تحسّن في الطلب عبر فئات إلكترونيات مهمة. 💻📺📱
🔥 أبرز النقاط:
💻 الطلب على الحوسبة يتحسن
📺 أجهزة التلفاز والأجهزة المنزلية تُظهر زخمًا
📱 منتجات الهاتف المحمول ما زالت مرنة
🤖 التكنولوجيا المدعومة بالذكاء الاصطناعي وتقنيات الجيل التالي تجذب الانتباه
📈 الإدارة رفعت توقعاتها للسنة بالكامل
🎯 ما الذي يجب أن يراقبه المتداولون بعد ذلك:
المبيعات المماثلة، هوامش الربح، طلب أجهزة AI-PC، اتجاهات التسوق خلال العطلات، والمنافسة في قطاع التجزئة.
إنّ التوجيهات المرفوعة تُعد إشارة ملحوظة بأن الإدارة ترى ظروفًا تتحسن في الفترة المقبلة. لكن السؤال الأكبر يبقى:
👀 هل هذه بداية تعافٍ أوسع في إلكترونيات المستهلك — أم مجرد ارتداد مؤقت؟
متابعة من فضلكم
#BBY #StockMarket #Retail
$BBY.US
$BTC
$BNB
🚨 أفضل مشتريات تتفوق على التوقعات — هل انتعاش إلكترونيات المستهلك في الأفق؟ 📈🔥
قدّمت Best Buy نتائج أقوى من المتوقع للربع الثاني، إذ تجاوزت الإيرادات تقديرات وول ستريت مع ظهور بوادر تحسّن في الطلب عبر فئات إلكترونيات مهمة. 💻📺📱
🔥 أبرز النقاط:
💻 الطلب على الحوسبة يتحسن
📺 أجهزة التلفاز والأجهزة المنزلية تُظهر زخمًا
📱 منتجات الهاتف المحمول ما زالت مرنة
🤖 التكنولوجيا المدعومة بالذكاء الاصطناعي وتقنيات الجيل التالي تجذب الانتباه
📈 الإدارة رفعت توقعاتها للسنة بالكامل
🎯 ما الذي يجب أن يراقبه المتداولون بعد ذلك:
المبيعات المماثلة، هوامش الربح، طلب أجهزة AI-PC، اتجاهات التسوق خلال العطلات، والمنافسة في قطاع التجزئة.
إنّ التوجيهات المرفوعة تُعد إشارة ملحوظة بأن الإدارة ترى ظروفًا تتحسن في الفترة المقبلة. لكن السؤال الأكبر يبقى:
👀 هل هذه بداية تعافٍ أوسع في إلكترونيات المستهلك — أم مجرد ارتداد مؤقت؟
متابعة من فضلكم
#BBY #StockMarket #Retail
$BBY.US
$BTC
$BNB
1
189
·
--
Top 20 Firms Revolutionizing Retail Crypto Access: BeInCrypto Institutional 100 Awards
The BeInCrypto Institutional 100 Awards just dropped their Retail to Crypto Bridge shortlist, naming 20 heavy hitters. These are the companies actually getting everyday folks into digital assets, not just talking about it. Think neobanks with integrated staking, fintechs facilitating instant swaps, and brokers layering crypto onto traditional portfolios.
We're talking about giants like Revolut, which now boasts 14 million active crypto users and a MiCA license, alongside Nubank bringing crypto to over 4 million Brazilians. SoFi is even issuing its own retail stablecoin on Ethereum and Solana. These aren't small plays; they're institutional-grade infrastructure for the retail trader.
On the fintech front, Block's Cash App continues its Bitcoin dominance, while ChangeNOW handles millions of instant swaps. KAST is enabling stablecoin spending at 150 million Visa merchants. This is the real onramp and offramp action, moving billions in volume and making crypto a utility, not just a speculative asset.
Brokers are also stepping up. Fidelity is integrating spot ETFs like FBTC and FETH directly into IRAs, while Interactive Brokers offers direct crypto trading across the EEA. Swissquote is even providing staking options alongside traditional instruments. This integration is key to capturing the next wave of retail capital.
Finally, the infrastructure providers are the unsung heroes. Coinbase Onramp and MoonPay are powering fiat conversions for countless apps, with MoonPay even snagging a NY BitLicense and EU MiCA authorization. Stripe's Bridge platform, with OCC approval, is orchestrating stablecoin transactions at scale. These are the rails that will carry the retail flood.
#retail #adoption #fintech #neobanks #brokers
Top 20 Firms Revolutionizing Retail Crypto Access: BeInCrypto Institutional 100 Awards
The BeInCrypto Institutional 100 Awards just dropped their Retail to Crypto Bridge shortlist, naming 20 heavy hitters. These are the companies actually getting everyday folks into digital assets, not just talking about it. Think neobanks with integrated staking, fintechs facilitating instant swaps, and brokers layering crypto onto traditional portfolios.
We're talking about giants like Revolut, which now boasts 14 million active crypto users and a MiCA license, alongside Nubank bringing crypto to over 4 million Brazilians. SoFi is even issuing its own retail stablecoin on Ethereum and Solana. These aren't small plays; they're institutional-grade infrastructure for the retail trader.
On the fintech front, Block's Cash App continues its Bitcoin dominance, while ChangeNOW handles millions of instant swaps. KAST is enabling stablecoin spending at 150 million Visa merchants. This is the real onramp and offramp action, moving billions in volume and making crypto a utility, not just a speculative asset.
Brokers are also stepping up. Fidelity is integrating spot ETFs like FBTC and FETH directly into IRAs, while Interactive Brokers offers direct crypto trading across the EEA. Swissquote is even providing staking options alongside traditional instruments. This integration is key to capturing the next wave of retail capital.
Finally, the infrastructure providers are the unsung heroes. Coinbase Onramp and MoonPay are powering fiat conversions for countless apps, with MoonPay even snagging a NY BitLicense and EU MiCA authorization. Stripe's Bridge platform, with OCC approval, is orchestrating stablecoin transactions at scale. These are the rails that will carry the retail flood.
#retail #adoption #fintech #neobanks #brokers
The BeInCrypto Institutional 100 Awards just dropped their Retail to Crypto Bridge shortlist, naming 20 heavy hitters. These are the companies actually getting everyday folks into digital assets, not just talking about it. Think neobanks with integrated staking, fintechs facilitating instant swaps, and brokers layering crypto onto traditional portfolios.
We're talking about giants like Revolut, which now boasts 14 million active crypto users and a MiCA license, alongside Nubank bringing crypto to over 4 million Brazilians. SoFi is even issuing its own retail stablecoin on Ethereum and Solana. These aren't small plays; they're institutional-grade infrastructure for the retail trader.
On the fintech front, Block's Cash App continues its Bitcoin dominance, while ChangeNOW handles millions of instant swaps. KAST is enabling stablecoin spending at 150 million Visa merchants. This is the real onramp and offramp action, moving billions in volume and making crypto a utility, not just a speculative asset.
Brokers are also stepping up. Fidelity is integrating spot ETFs like FBTC and FETH directly into IRAs, while Interactive Brokers offers direct crypto trading across the EEA. Swissquote is even providing staking options alongside traditional instruments. This integration is key to capturing the next wave of retail capital.
Finally, the infrastructure providers are the unsung heroes. Coinbase Onramp and MoonPay are powering fiat conversions for countless apps, with MoonPay even snagging a NY BitLicense and EU MiCA authorization. Stripe's Bridge platform, with OCC approval, is orchestrating stablecoin transactions at scale. These are the rails that will carry the retail flood.
#retail #adoption #fintech #neobanks #brokers
1
66
📊 Weekend Market Patterns: How Saturdays Differ in Crypto Trading
On July 11, 2026, a Saturday, crypto volume of $59.81B demonstrates the 24/7 nature of digital asset markets. Weekend trading patterns often differ from weekdays, with lower institutional participation and more retail-driven moves.
$BTC at $64,088 and $ETH at $1,795 show that the major assets continue their week-long trends into the weekend. Lower liquidity can sometimes amplify price swings.
With the market cap at $2.28T, weekend trading offers opportunities for retail traders to position ahead of Monday's institutional flows.
📌 Key Takeaway:
Weekend crypto trading offers retail-driven opportunities — lower institutional participation can create mispricings.
#WeekendTrading #CryptoMarkets #Retail
#BinanceAlphaAlert
📊 Weekend Market Patterns: How Saturdays Differ in Crypto Trading
On July 11, 2026, a Saturday, crypto volume of $59.81B demonstrates the 24/7 nature of digital asset markets. Weekend trading patterns often differ from weekdays, with lower institutional participation and more retail-driven moves.
$BTC at $64,088 and $ETH at $1,795 show that the major assets continue their week-long trends into the weekend. Lower liquidity can sometimes amplify price swings.
With the market cap at $2.28T, weekend trading offers opportunities for retail traders to position ahead of Monday's institutional flows.
📌 Key Takeaway:
Weekend crypto trading offers retail-driven opportunities — lower institutional participation can create mispricings.
#WeekendTrading #CryptoMarkets #Retail
#BinanceAlphaAlert
On July 11, 2026, a Saturday, crypto volume of $59.81B demonstrates the 24/7 nature of digital asset markets. Weekend trading patterns often differ from weekdays, with lower institutional participation and more retail-driven moves.
$BTC at $64,088 and $ETH at $1,795 show that the major assets continue their week-long trends into the weekend. Lower liquidity can sometimes amplify price swings.
With the market cap at $2.28T, weekend trading offers opportunities for retail traders to position ahead of Monday's institutional flows.
📌 Key Takeaway:
Weekend crypto trading offers retail-driven opportunities — lower institutional participation can create mispricings.
#WeekendTrading #CryptoMarkets #Retail
#BinanceAlphaAlert
54
·
--
Bearish
Verified
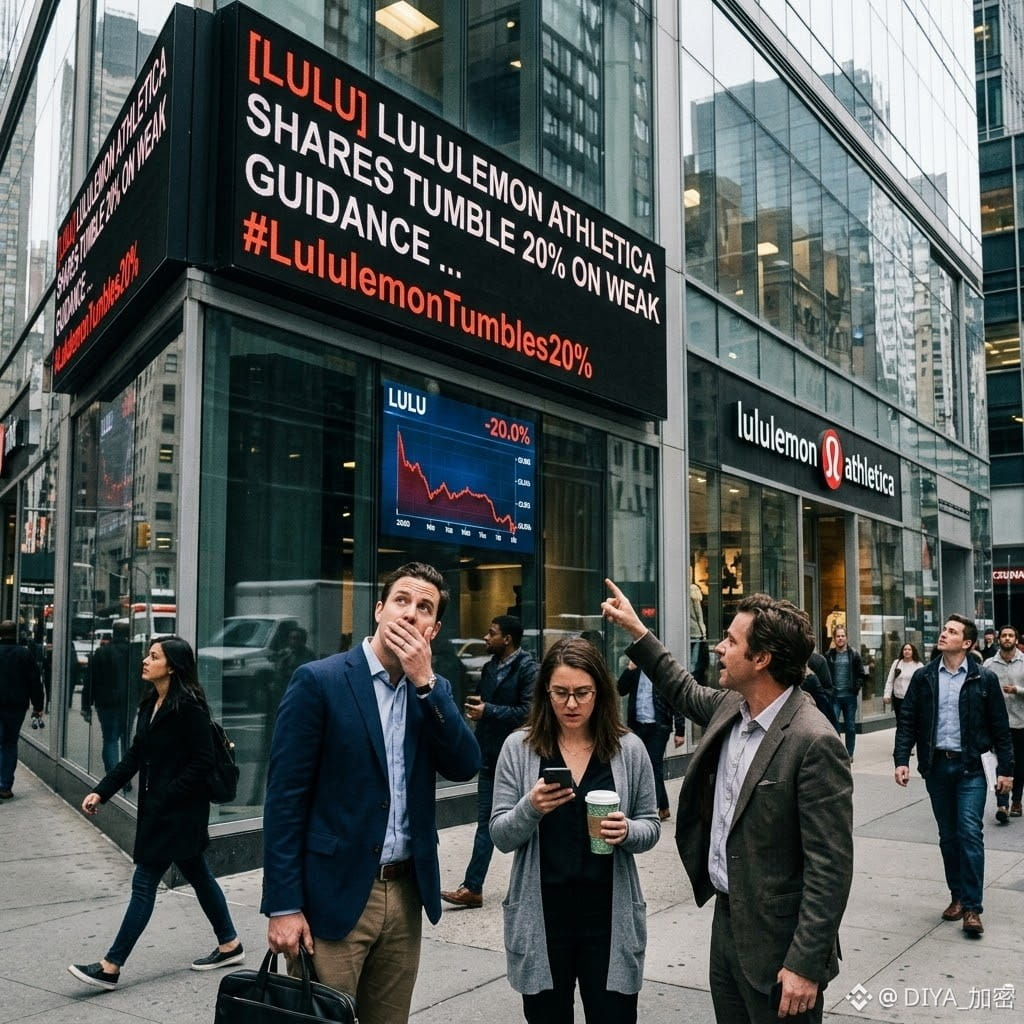
$LULU.US lemon just got hit hard. 📉
Shares tumbled nearly 20% after the company gave investors a weaker outlook, raising fresh concerns about slowing growth and consumer demand.
It’s a sharp reminder that even some of the strongest retail brands can feel pressure when expectations are high.
#LULU #Stocks #StockMarket #Investing #Retail
{stock_us}(LULU.US)
{future}(BTCUSDT)
{future}(DOTUSDT)
$LULU.US lemon just got hit hard. 📉
Shares tumbled nearly 20% after the company gave investors a weaker outlook, raising fresh concerns about slowing growth and consumer demand.
It’s a sharp reminder that even some of the strongest retail brands can feel pressure when expectations are high.
#LULU #Stocks #StockMarket #Investing #Retail
Shares tumbled nearly 20% after the company gave investors a weaker outlook, raising fresh concerns about slowing growth and consumer demand.
It’s a sharp reminder that even some of the strongest retail brands can feel pressure when expectations are high.
#LULU #Stocks #StockMarket #Investing #Retail
LULUUS-2.64%
1
725
Article
Best Buy Beats Expectations Is Consumer Demand Back?🚀 Best Buy Beats Expectations
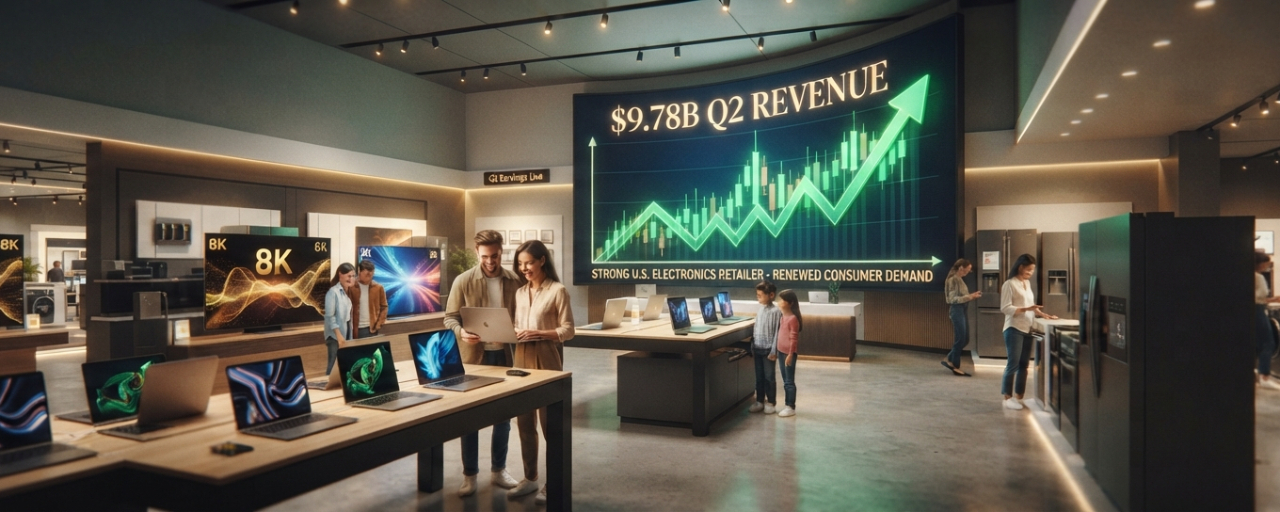
Best Buy posted $9.78B in Q2 revenue, helped by strong computer and electronics sales.
The company also raised its outlook.
Is consumer demand finally coming back? 👀
#BestBuy
{future}(ADAUSDT)
{future}(BTCUSDT)
{future}(ETHUSDT)
#Retail #Markets #Tech
Best Buy Beats Expectations Is Consumer Demand Back?
53
·
--
Bearish
🚨 LOS TIBURONES ESTÁN PONIENDO LAS REDES MÁS ABAJO 🐳🩸
👀 Ojo pues porque esta imagen muestra algo que muchos venden en pánico sin mirar
sigueme para más información
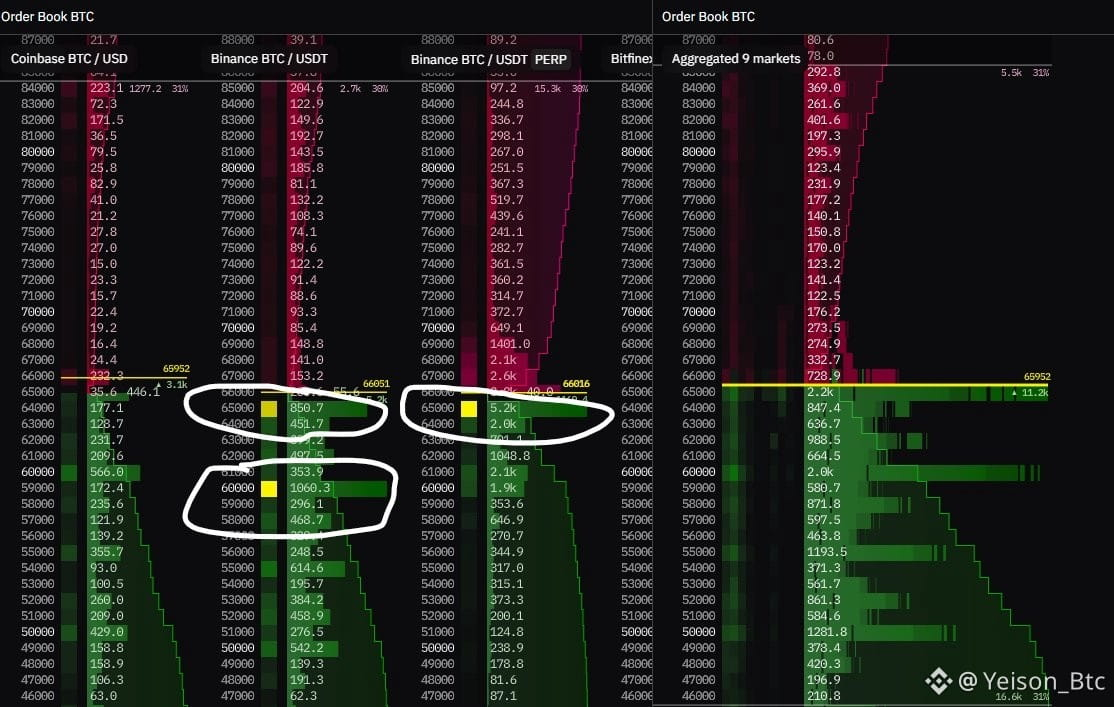
Las zonas marcadas alrededor de 64k-65k y 59k-60k tienen órdenes de compra enormes esperando ser ejecutadas 💰
🐳 En palabras simples:
Mientras el #retail entra en miedo extremo y vende desesperado 😨
Los grandes jugadores están dejando órdenes gigantes para recoger $BTC más barato 🔥
📊 Lo que veo en el mapa:
✅ Fuerte interés comprador en 64k-65k
✅ Otra piscina enorme en 59k-60k
✅ Liquidez adicional repartida incluso más abajo
⚠️ Pero ojo
Esto NO significa que #BTC tenga que llegar obligatoriamente a 60k
Las órdenes pueden moverse, cancelarse o aumentar en cualquier momento
🔥 Lo que sí significa es que hay jugadores con mucho capital dispuestos a comprar agresivamente en esas zonas
🐳 Históricamente los grandes compran cuando:
🩸 El miedo está en máximos
🩸 Los traders son liquidados
🩸 Twitter está lleno de pánico
🩸 Nadie quiere comprar
Y justamente eso es lo que estamos viendo ahora mismo 😳
💰 Lo que vendes por miedo hoy podría terminar en las billeteras de los mismos que luego te lo venderán mucho más caro durante el próximo rally
🔥 La verdadera pregunta no es quién está vendiendo
🐳 La verdadera pregunta es quién está absorbiendo todas esas ventas
👀 ¿Crees que los 60k serán el gran punto de acumulación o todavía falta una barrida hacia 55k-50k antes del próximo movimiento fuerte? 🚀🩸🐳🔥
{spot}(BTCUSDT)
🚨 LOS TIBURONES ESTÁN PONIENDO LAS REDES MÁS ABAJO 🐳🩸
👀 Ojo pues porque esta imagen muestra algo que muchos venden en pánico sin mirar
sigueme para más información
Las zonas marcadas alrededor de 64k-65k y 59k-60k tienen órdenes de compra enormes esperando ser ejecutadas 💰
🐳 En palabras simples:
Mientras el #retail entra en miedo extremo y vende desesperado 😨
Los grandes jugadores están dejando órdenes gigantes para recoger $BTC más barato 🔥
📊 Lo que veo en el mapa:
✅ Fuerte interés comprador en 64k-65k
✅ Otra piscina enorme en 59k-60k
✅ Liquidez adicional repartida incluso más abajo
⚠️ Pero ojo
Esto NO significa que #BTC tenga que llegar obligatoriamente a 60k
Las órdenes pueden moverse, cancelarse o aumentar en cualquier momento
🔥 Lo que sí significa es que hay jugadores con mucho capital dispuestos a comprar agresivamente en esas zonas
🐳 Históricamente los grandes compran cuando:
🩸 El miedo está en máximos
🩸 Los traders son liquidados
🩸 Twitter está lleno de pánico
🩸 Nadie quiere comprar
Y justamente eso es lo que estamos viendo ahora mismo 😳
💰 Lo que vendes por miedo hoy podría terminar en las billeteras de los mismos que luego te lo venderán mucho más caro durante el próximo rally
🔥 La verdadera pregunta no es quién está vendiendo
🐳 La verdadera pregunta es quién está absorbiendo todas esas ventas
👀 ¿Crees que los 60k serán el gran punto de acumulación o todavía falta una barrida hacia 55k-50k antes del próximo movimiento fuerte? 🚀🩸🐳🔥
👀 Ojo pues porque esta imagen muestra algo que muchos venden en pánico sin mirar
sigueme para más información
Las zonas marcadas alrededor de 64k-65k y 59k-60k tienen órdenes de compra enormes esperando ser ejecutadas 💰
🐳 En palabras simples:
Mientras el #retail entra en miedo extremo y vende desesperado 😨
Los grandes jugadores están dejando órdenes gigantes para recoger $BTC más barato 🔥
📊 Lo que veo en el mapa:
✅ Fuerte interés comprador en 64k-65k
✅ Otra piscina enorme en 59k-60k
✅ Liquidez adicional repartida incluso más abajo
⚠️ Pero ojo
Esto NO significa que #BTC tenga que llegar obligatoriamente a 60k
Las órdenes pueden moverse, cancelarse o aumentar en cualquier momento
🔥 Lo que sí significa es que hay jugadores con mucho capital dispuestos a comprar agresivamente en esas zonas
🐳 Históricamente los grandes compran cuando:
🩸 El miedo está en máximos
🩸 Los traders son liquidados
🩸 Twitter está lleno de pánico
🩸 Nadie quiere comprar
Y justamente eso es lo que estamos viendo ahora mismo 😳
💰 Lo que vendes por miedo hoy podría terminar en las billeteras de los mismos que luego te lo venderán mucho más caro durante el próximo rally
🔥 La verdadera pregunta no es quién está vendiendo
🐳 La verdadera pregunta es quién está absorbiendo todas esas ventas
👀 ¿Crees que los 60k serán el gran punto de acumulación o todavía falta una barrida hacia 55k-50k antes del próximo movimiento fuerte? 🚀🩸🐳🔥
3
5
4.9k
After halving the rate from 28% over the past year due to aggressive disinflation, the central bank paused due to global energy pressures and exchange rate movements impacting transport and food. Less aggressive rate cuts mean local fiat liquidity might remain tight, which heavily influences how retail users interact with digital assets and peer-to-peer (P2P) markets.
#centralbank
#retail
$BTC $BNB $ETH
After halving the rate from 28% over the past year due to aggressive disinflation, the central bank paused due to global energy pressures and exchange rate movements impacting transport and food. Less aggressive rate cuts mean local fiat liquidity might remain tight, which heavily influences how retail users interact with digital assets and peer-to-peer (P2P) markets.
#centralbank
#retail
$BTC $BNB $ETH
#centralbank
#retail
$BTC $BNB $ETH
1
186
·
--
Bullish
Shein comes under pressure after its first earnings report since IPO
📉 Shein shares fell more than 6% in early trading on September 29 after the company reported Q2 adjusted net profit of just $228 million, down nearly 67% year over year, while revenue increased only 0.9%.
📦 Pressure was concentrated in key markets, with revenue in Europe down 13.9% and the US down 6%. Fulfillment costs also rose 18.1%, pushing the adjusted net margin down from 6.2% to 2.1%.
🧾 IFRS net profit reached $2.4 billion, but most of the increase came from a revaluation gain on preferred shares related to the IPO, meaning it did not directly reflect the strength of core operations.
🌍 The report highlights growing pressure on Shein’s low-cost, cross-border logistics model from higher shipping costs and changing tax and e-commerce fee structures in the US and EU.
#Retail $SHEIN $BNB
Shein comes under pressure after its first earnings report since IPO
📉 Shein shares fell more than 6% in early trading on September 29 after the company reported Q2 adjusted net profit of just $228 million, down nearly 67% year over year, while revenue increased only 0.9%.
📦 Pressure was concentrated in key markets, with revenue in Europe down 13.9% and the US down 6%. Fulfillment costs also rose 18.1%, pushing the adjusted net margin down from 6.2% to 2.1%.
🧾 IFRS net profit reached $2.4 billion, but most of the increase came from a revaluation gain on preferred shares related to the IPO, meaning it did not directly reflect the strength of core operations.
🌍 The report highlights growing pressure on Shein’s low-cost, cross-border logistics model from higher shipping costs and changing tax and e-commerce fee structures in the US and EU.
#Retail $SHEIN $BNB
📉 Shein shares fell more than 6% in early trading on September 29 after the company reported Q2 adjusted net profit of just $228 million, down nearly 67% year over year, while revenue increased only 0.9%.
📦 Pressure was concentrated in key markets, with revenue in Europe down 13.9% and the US down 6%. Fulfillment costs also rose 18.1%, pushing the adjusted net margin down from 6.2% to 2.1%.
🧾 IFRS net profit reached $2.4 billion, but most of the increase came from a revaluation gain on preferred shares related to the IPO, meaning it did not directly reflect the strength of core operations.
🌍 The report highlights growing pressure on Shein’s low-cost, cross-border logistics model from higher shipping costs and changing tax and e-commerce fee structures in the US and EU.
#Retail $SHEIN $BNB
72
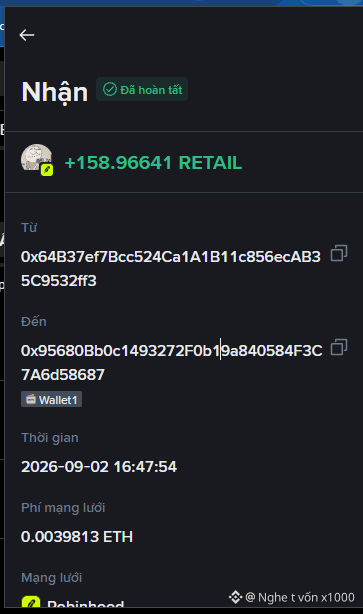
Nói là làm, không có 2 lời!
Một token mới phát hành trên Robinhood [Retail](https://web3.binance.com/vi/token/robinhood/0xe766b582fb90511c923bb28f1c9574170bcb2ac4?ref=MM0ZZF2V) với mục tiêu airdrop cho tất cả những ai đã từng trade những token được ra mắt trên Pons, theo tổng khối lượng đã trade.
Họ vừa airdrop cho tôi 0.012 đô la dựa trên tổng khối lượng 1ETH tôi đã trade.
Điều đáng nói là phí gửi đến ví của tôi tận 9.53 đô la
Đúng là nói là làm, không có nhưng mà hay là gì hết sất !
Uy tín 100%!
Nhập mã giới thiệu của tôi trên web 3 Binance để được giảm 30% phí giao dịch: MM0ZZF2V
#memecoin🚀🚀🚀 #meme板块关注热点 #Robinhood #retail
Nói là làm, không có 2 lời!
Một token mới phát hành trên Robinhood Retail với mục tiêu airdrop cho tất cả những ai đã từng trade những token được ra mắt trên Pons, theo tổng khối lượng đã trade.
Họ vừa airdrop cho tôi 0.012 đô la dựa trên tổng khối lượng 1ETH tôi đã trade.
Điều đáng nói là phí gửi đến ví của tôi tận 9.53 đô la
Đúng là nói là làm, không có nhưng mà hay là gì hết sất !
Uy tín 100%!
Nhập mã giới thiệu của tôi trên web 3 Binance để được giảm 30% phí giao dịch: MM0ZZF2V
#memecoin🚀🚀🚀 #meme板块关注热点 #Robinhood #retail
Một token mới phát hành trên Robinhood Retail với mục tiêu airdrop cho tất cả những ai đã từng trade những token được ra mắt trên Pons, theo tổng khối lượng đã trade.
Họ vừa airdrop cho tôi 0.012 đô la dựa trên tổng khối lượng 1ETH tôi đã trade.
Điều đáng nói là phí gửi đến ví của tôi tận 9.53 đô la
Đúng là nói là làm, không có nhưng mà hay là gì hết sất !
Uy tín 100%!
Nhập mã giới thiệu của tôi trên web 3 Binance để được giảm 30% phí giao dịch: MM0ZZF2V
#memecoin🚀🚀🚀 #meme板块关注热点 #Robinhood #retail
1
1.2k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#CanBTCReboundAfterFallingBelow60K?
418,790 views
1,779 Discussing
2
#GlobalStocksFaceLongestLosingStreakSince2023
140,649 views
1,251 Discussing
3
#BlackRockIBITPostsRecord$541MSingleDayOutflow
2,976 views
36 Discussing
4
#AnthropicPlungesTowardIPOPriceonDay2
67,063 views
700 Discussing
5
#TwentyOneCapitalAdds172.25BTC
18,667 views
247 Discussing
6
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
2,139 views
26 Discussing
7
#BNBDropsBelow540USDTWith8.46%DailyDecline
39,003 views
341 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
1,328 views
19 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
2,356 views
24 Discussing
10
#StrategyReports$35BNetReserves
2,248 views
18 Discussing