

七月哈哈
1.6k Posts
七月哈哈
 Square Verified+
Report
Block User
X: @ChenJuly777 | 欲望不要大于能力
2.1K+ Following
43.6K+ Followers
31.5K+ Liked
Posts
All
Quotes
Videos
·
--
NVIDIA: $NVDAB
{spot}(NVDABUSDT)
DRAM prices are already extremely high, and they may continue to rise.
SK Hynix: $SKHY
{future}(SKHYUSDT)
It is expected that memory supply and demand will not rebalance until at least 2030.
Micron: $MU
{future}(MUUSDT)
Micron’s 2026 HBM capacity is already sold out, and it is now moving forward with HBM4E.
So, based on the public statements from these upstream and downstream companies, market expectations for Micron’s next-quarter results still lean toward the possibility of continuing to beat expectations.
The real controversy isn’t whether there is demand for memory right now.
It’s whether the memory demand driven by this AI wave will be a sustained multi-year structural growth cycle, or just another cyclical peak that ultimately leads to large-scale capacity expansion.
NVIDIA: $NVDAB
DRAM prices are already extremely high, and they may continue to rise.
SK Hynix: $SKHY
It is expected that memory supply and demand will not rebalance until at least 2030.
Micron: $MU
Micron’s 2026 HBM capacity is already sold out, and it is now moving forward with HBM4E.
So, based on the public statements from these upstream and downstream companies, market expectations for Micron’s next-quarter results still lean toward the possibility of continuing to beat expectations.
The real controversy isn’t whether there is demand for memory right now.
It’s whether the memory demand driven by this AI wave will be a sustained multi-year structural growth cycle, or just another cyclical peak that ultimately leads to large-scale capacity expansion.
436
·
--
SOL has once again held above $100 this time—I still think there’s something here.
On-chain fundamentals aren’t as bad as people imagined. TVL is already close to $5.9 billion. DEX 7-day trading volume has returned to $17.3 billion. RWA has also risen to $4.3 billion, and XStocks trading volume has even surpassed $1 billion.
Plus, expectations around ETF inflows, regulatory frameworks, and tokenized stocks mean Solana’s application scenarios are still expanding.
The issue right now isn’t that there’s no demand on-chain, but that interest rates are still compressing valuations.
If later on $100 can hold steadily, and on top of that RWA, ETFs, and tokenized stocks continue to scale up in volume, personally I would remain bullish on SOL. Pullbacks are actually worth paying attention to.
Look for opportunities in pullbacks—don’t wait for it to start rising and then chase.
$SOL
{future}(SOLUSDT)
SOL has once again held above $100 this time—I still think there’s something here.
On-chain fundamentals aren’t as bad as people imagined. TVL is already close to $5.9 billion. DEX 7-day trading volume has returned to $17.3 billion. RWA has also risen to $4.3 billion, and XStocks trading volume has even surpassed $1 billion.
Plus, expectations around ETF inflows, regulatory frameworks, and tokenized stocks mean Solana’s application scenarios are still expanding.
The issue right now isn’t that there’s no demand on-chain, but that interest rates are still compressing valuations.
If later on $100 can hold steadily, and on top of that RWA, ETFs, and tokenized stocks continue to scale up in volume, personally I would remain bullish on SOL. Pullbacks are actually worth paying attention to.
Look for opportunities in pullbacks—don’t wait for it to start rising and then chase.
$SOL
527
·
--
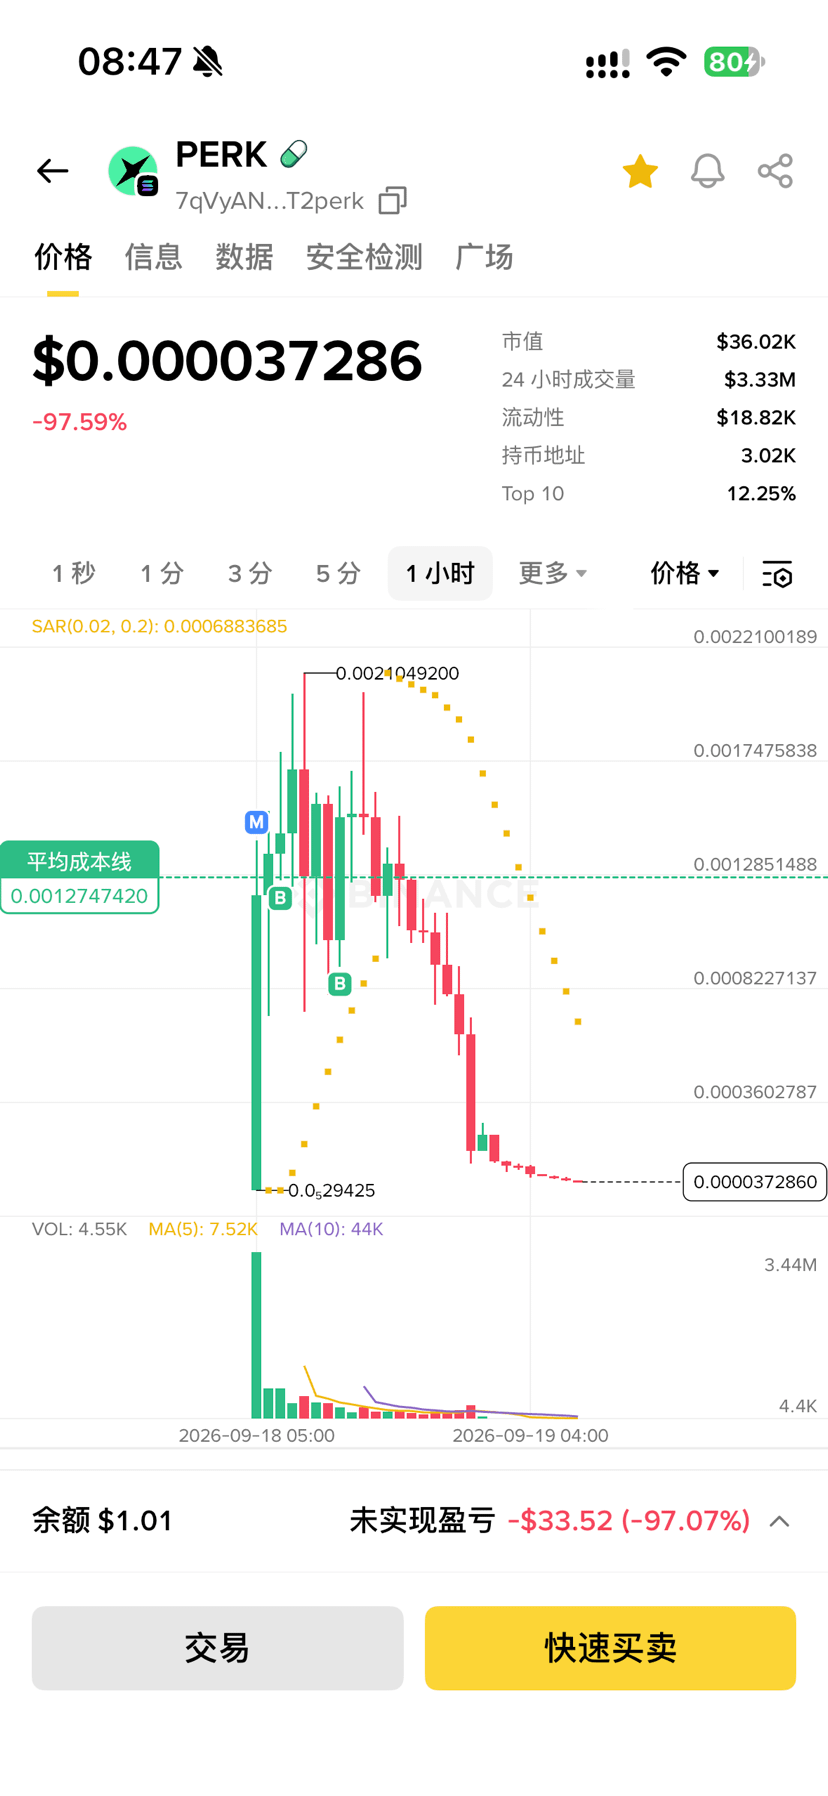
I shouldn’t have had any hope for you!
If you drop it, you drop it—how could a phone at 37.5° possibly have someone as cold as you? If you drop it, you drop it.
I shouldn’t have had any hope for you!
If you drop it, you drop it—how could a phone at 37.5° possibly have someone as cold as you? If you drop it, you drop it.
If you drop it, you drop it—how could a phone at 37.5° possibly have someone as cold as you? If you drop it, you drop it.
1
527
·
--
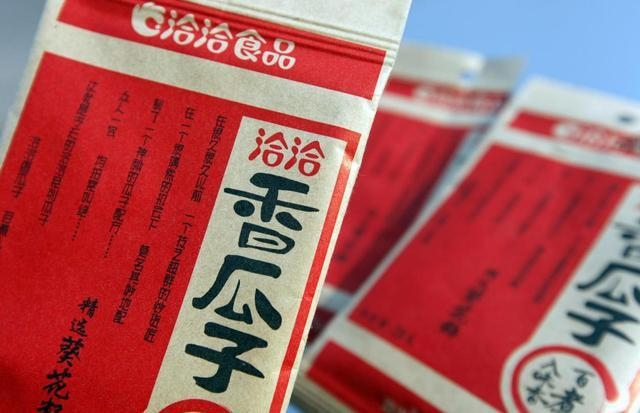
Why would Trump ban Chacha melon seeds—was it because there’s no cola flavor? Or is he afraid Americans will snack on melon seeds and get overheated?
On August 3, the U.S. added Chinese companies such as Chacha and Simin to its sanctions list. Netizens are making jokes, wondering if the U.S. is worried that U.S. troops might crack their teeth on melon seeds.
But this round of sanctions isn’t really targeting just a few bags of melon seeds.
Chacha’s dependence on the U.S. market is almost negligible. In 2025, overseas revenue accounted for less than 9% of total revenue, and the U.S. share isn’t even disclosed separately in its financial reports. What truly supports the company is the domestic market.
Look at the industry chain, too. Chacha has built a large number of sunflower bases in Xinjiang, Inner Mongolia, and Gansu. It doesn’t just source raw materials—it also provides seeds, technology, and contract farming arrangements, partnering with more than 20,000 planting households. This is an entire industry chain, not something as simple as just buying and selling melon seeds.
So, the damage from the U.S. sanctions this time is actually limited. It won’t affect American consumers, nor will it put Chacha in serious trouble. It’s more like the U.S. is sending a political signal.
What’s truly worth paying attention to is something else.
More and more Chinese consumer brands are no longer following the old model of “made in China, exported worldwide.” Instead, they’re building supply chains globally. For example, Chacha has set up a plant in Thailand, while Simin has already acquired factories in the United States and produces and sells locally.
Once these global supply chains mature, the effectiveness of many of the U.S.’s traditional sanctions will keep weakening.
This time, what the U.S. is trying to block isn’t melon seeds—it’s the new supply-chain system that Chinese companies are forming.
Even more interestingly, when the sanctions took effect, Chacha actually released a forecast of its earnings: in the first half of the year, net profit was expected to increase by more than 170% year over year, and the chairman has continued to buy additional shares.
So I think the biggest significance of this is not whether someone can or can’t sell melon seeds, but that the global supply chain is being reshuffled.
In the future, companies won’t just compete on products. The one who can build supply chains worldwide will have stronger resilience to risks.
The market will never stop just because of a sanctions notice. The melon seeds that should be sold will keep being sold, and the factories that should be opened will keep opening. What really determines how far a company can go is still its own industrial chain and global layout capabilities.
Eat Chacha while keeping an eye on the market.
$AAPLB $NVDAB $DOGE
{future}(DOGEUSDT)
{spot}(NVDABUSDT)
{spot}(AAPLBUSDT)
Why would Trump ban Chacha melon seeds—was it because there’s no cola flavor? Or is he afraid Americans will snack on melon seeds and get overheated?
On August 3, the U.S. added Chinese companies such as Chacha and Simin to its sanctions list. Netizens are making jokes, wondering if the U.S. is worried that U.S. troops might crack their teeth on melon seeds.
But this round of sanctions isn’t really targeting just a few bags of melon seeds.
Chacha’s dependence on the U.S. market is almost negligible. In 2025, overseas revenue accounted for less than 9% of total revenue, and the U.S. share isn’t even disclosed separately in its financial reports. What truly supports the company is the domestic market.
Look at the industry chain, too. Chacha has built a large number of sunflower bases in Xinjiang, Inner Mongolia, and Gansu. It doesn’t just source raw materials—it also provides seeds, technology, and contract farming arrangements, partnering with more than 20,000 planting households. This is an entire industry chain, not something as simple as just buying and selling melon seeds.
So, the damage from the U.S. sanctions this time is actually limited. It won’t affect American consumers, nor will it put Chacha in serious trouble. It’s more like the U.S. is sending a political signal.
What’s truly worth paying attention to is something else.
More and more Chinese consumer brands are no longer following the old model of “made in China, exported worldwide.” Instead, they’re building supply chains globally. For example, Chacha has set up a plant in Thailand, while Simin has already acquired factories in the United States and produces and sells locally.
Once these global supply chains mature, the effectiveness of many of the U.S.’s traditional sanctions will keep weakening.
This time, what the U.S. is trying to block isn’t melon seeds—it’s the new supply-chain system that Chinese companies are forming.
Even more interestingly, when the sanctions took effect, Chacha actually released a forecast of its earnings: in the first half of the year, net profit was expected to increase by more than 170% year over year, and the chairman has continued to buy additional shares.
So I think the biggest significance of this is not whether someone can or can’t sell melon seeds, but that the global supply chain is being reshuffled.
In the future, companies won’t just compete on products. The one who can build supply chains worldwide will have stronger resilience to risks.
The market will never stop just because of a sanctions notice. The melon seeds that should be sold will keep being sold, and the factories that should be opened will keep opening. What really determines how far a company can go is still its own industrial chain and global layout capabilities.
Eat Chacha while keeping an eye on the market.
$AAPLB $NVDAB $DOGE
1
582
·
--
Honestly, the market isn’t quite the same as it was a few years ago.
Back then, once you opened a group, it was all questions like: "When will it surge like crazy?" and "Can it still multiply a few times?"
Now I’m seeing more and more people discussing something else.
So much BTC just lying in wallets—doesn’t that feel a bit of a waste?
After all, BTC is no longer some small asset.
With such a huge global scale, if its only purpose is to be held and wait for appreciation, it feels like something is missing.
I’ve had a picture in my mind for a while.
Many people treat BTC like gold bars in a safe—lock it up, put it away, and don’t touch it.
It’s safe, sure, but it never participates in creating new value.
Recently I came across the views of Charles d'Haussy, CEO of the dYdX Foundation, who said that BTC is very suitable as collateral because market depth, liquidity, and consensus are strong enough.
I think the key isn’t really that statement by itself.
It’s that more and more industries are starting to assume by default that BTC can take on more financial functions.
Of course, the biggest contradiction in all of this has never changed.
Everyone wants to improve the capital efficiency of BTC, but nobody wants to sacrifice its most important safety.
That’s also why Babylon’s Trustless Bitcoin Vaults made me take a closer look.
At least it attempts to answer one question: is there a way to keep BTC’s underlying properties unchanged, while still enabling it to be used in more real-world applications.
My own view is pretty simple.
BTC’s real growth shouldn’t depend only on round after round of bull markets.
The real incremental change is that more and more scenarios start actively needing BTC.
When it shifts from being hoarded for the long term to being used for the long term—that, I think, is the most exciting change for the whole ecosystem.
#Baby $BABY @babylonlabs_io
Honestly, the market isn’t quite the same as it was a few years ago.
Back then, once you opened a group, it was all questions like: "When will it surge like crazy?" and "Can it still multiply a few times?"
Now I’m seeing more and more people discussing something else.
So much BTC just lying in wallets—doesn’t that feel a bit of a waste?
After all, BTC is no longer some small asset.
With such a huge global scale, if its only purpose is to be held and wait for appreciation, it feels like something is missing.
I’ve had a picture in my mind for a while.
Many people treat BTC like gold bars in a safe—lock it up, put it away, and don’t touch it.
It’s safe, sure, but it never participates in creating new value.
Recently I came across the views of Charles d'Haussy, CEO of the dYdX Foundation, who said that BTC is very suitable as collateral because market depth, liquidity, and consensus are strong enough.
I think the key isn’t really that statement by itself.
It’s that more and more industries are starting to assume by default that BTC can take on more financial functions.
Of course, the biggest contradiction in all of this has never changed.
Everyone wants to improve the capital efficiency of BTC, but nobody wants to sacrifice its most important safety.
That’s also why Babylon’s Trustless Bitcoin Vaults made me take a closer look.
At least it attempts to answer one question: is there a way to keep BTC’s underlying properties unchanged, while still enabling it to be used in more real-world applications.
My own view is pretty simple.
BTC’s real growth shouldn’t depend only on round after round of bull markets.
The real incremental change is that more and more scenarios start actively needing BTC.
When it shifts from being hoarded for the long term to being used for the long term—that, I think, is the most exciting change for the whole ecosystem.
#Baby $BABY @BabylonLabs_io
1
4
424
·
--
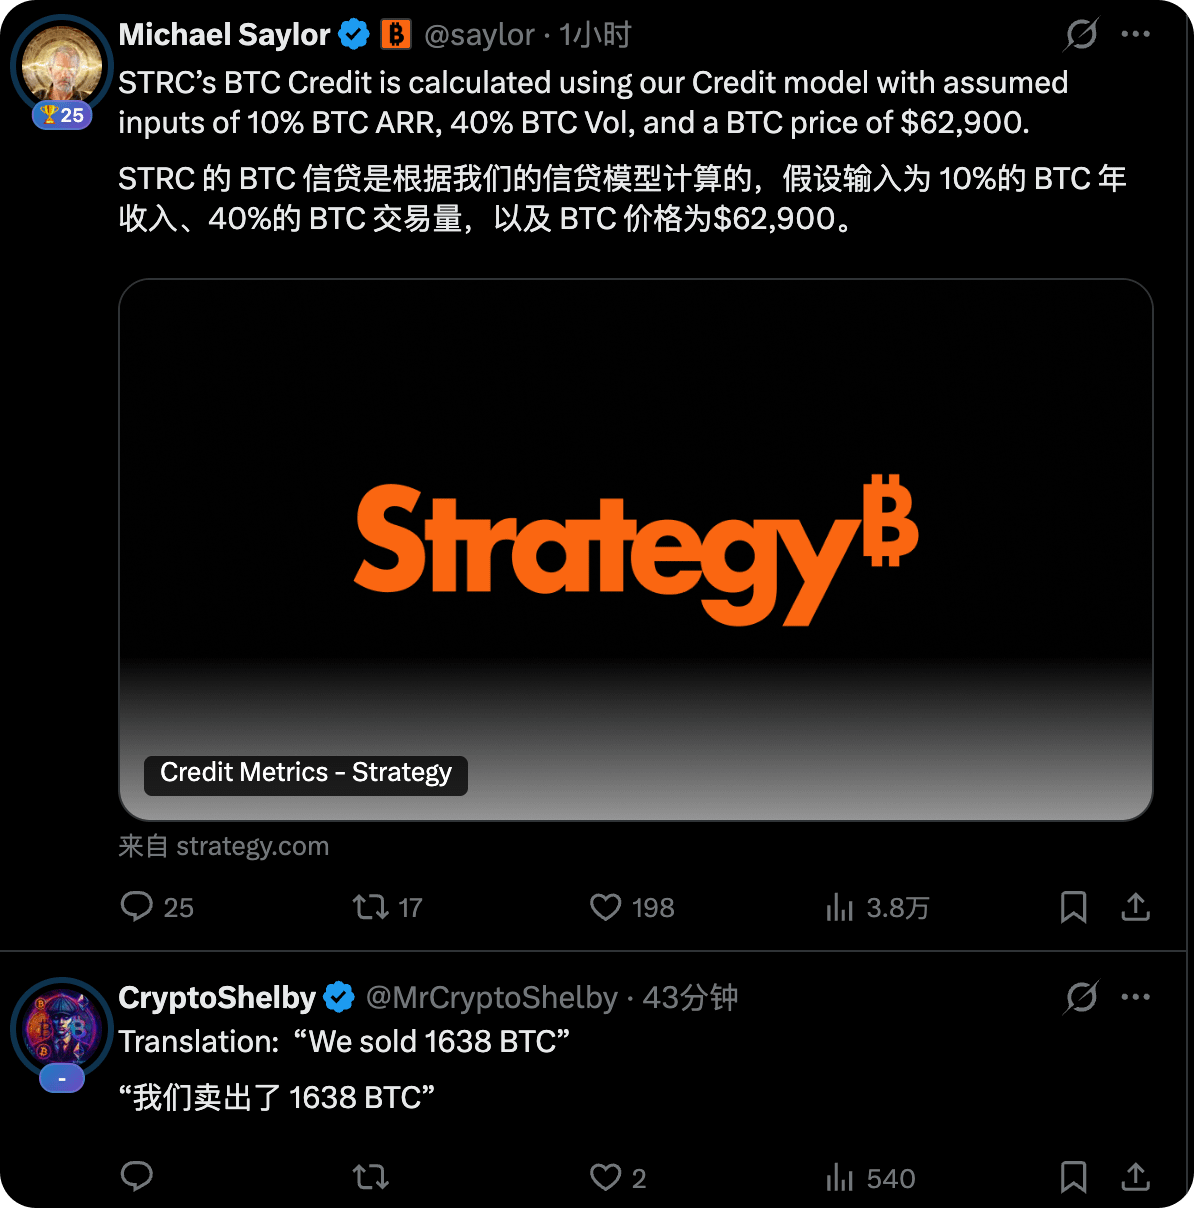
I just saw a tweet from MicroStrategy, and the comments section is already blowing up.
Someone even translated it into one sentence: “We sold 1,638 BTC.”
While it’s more like a joke, it also reflects that people in the market are a bit on edge.
Whenever Strategy posts anything about credit, financing, or models, the first reaction from everyone is: “Did they sell coins again?” “Are they under pressure with their funding chain?” The emotion spreads even faster than the news itself.
From the perspective of small retail investors like us, this market really is quite confusing right now. On one side, more and more institutions are treating BTC as part of their balance sheets. All kinds of financing, bond issuance, and credit instruments are getting more and more sophisticated. It looks like Bitcoin is slowly being integrated into the traditional financial system—this is a long-term positive. It suggests it’s not just a speculative asset, but that it’s genuinely starting to have financial attributes.
But there are also worries. The macro environment still isn’t very calm. Global liquidity hasn’t moved into a particularly loose phase, and market sentiment often swings back and forth due to policy, geopolitical events, or economic data. BTC is a high-volatility asset, and once a credit model is built on assumptions about a certain price and volatility, if the market deviates from those assumptions, the risk gets magnified quickly.
So I think this tweet is essentially telling the market: “Our credit model has a basis.”
But what the market hears is a different message: “Are you planning to move BTC?” That’s the most real state of the market right now—everyone is already a bit on edge, being tossed around by all kinds of bad news and good news.
That said, over the years, Strategy has been steadily accumulating BTC all the way, so it has deeply bound itself to Bitcoin.
Their biggest advantage is that the consensus is strong and the execution is strong, and the community’s influence is big enough—every time they speak, it affects market sentiment.
But conversely, this level of binding is also a risk. Once the cost of financing rises, the credit environment tightens, or BTC experiences a major swing, the market will amplify its concerns about them.
Don’t chase or panic-sell because of a single tweet. And don’t lie awake worrying just because someone in the comments said “we sold 1,638 BTC.” In the short term, the market always looks at sentiment; in the long term, it’s still about capital and trends.
$BTC
{future}(BTCUSDT)
I just saw a tweet from MicroStrategy, and the comments section is already blowing up.
Someone even translated it into one sentence: “We sold 1,638 BTC.”
While it’s more like a joke, it also reflects that people in the market are a bit on edge.
Whenever Strategy posts anything about credit, financing, or models, the first reaction from everyone is: “Did they sell coins again?” “Are they under pressure with their funding chain?” The emotion spreads even faster than the news itself.
From the perspective of small retail investors like us, this market really is quite confusing right now. On one side, more and more institutions are treating BTC as part of their balance sheets. All kinds of financing, bond issuance, and credit instruments are getting more and more sophisticated. It looks like Bitcoin is slowly being integrated into the traditional financial system—this is a long-term positive. It suggests it’s not just a speculative asset, but that it’s genuinely starting to have financial attributes.
But there are also worries. The macro environment still isn’t very calm. Global liquidity hasn’t moved into a particularly loose phase, and market sentiment often swings back and forth due to policy, geopolitical events, or economic data. BTC is a high-volatility asset, and once a credit model is built on assumptions about a certain price and volatility, if the market deviates from those assumptions, the risk gets magnified quickly.
So I think this tweet is essentially telling the market: “Our credit model has a basis.”
But what the market hears is a different message: “Are you planning to move BTC?” That’s the most real state of the market right now—everyone is already a bit on edge, being tossed around by all kinds of bad news and good news.
That said, over the years, Strategy has been steadily accumulating BTC all the way, so it has deeply bound itself to Bitcoin.
Their biggest advantage is that the consensus is strong and the execution is strong, and the community’s influence is big enough—every time they speak, it affects market sentiment.
But conversely, this level of binding is also a risk. Once the cost of financing rises, the credit environment tightens, or BTC experiences a major swing, the market will amplify its concerns about them.
Don’t chase or panic-sell because of a single tweet. And don’t lie awake worrying just because someone in the comments said “we sold 1,638 BTC.” In the short term, the market always looks at sentiment; in the long term, it’s still about capital and trends.
$BTC
2
418
·
--
August 3 (Reuters) — American Bitcoin, supported by two of U.S. President Donald Trump’s sons, announced on Monday, reporting a swing to a loss in the second quarter due to a decline in the price of bitcoin.
As geopolitical tensions intensified, risk-averse sentiment grew in the market, prompting investors to reduce allocations to risk assets and putting broad pressure on cryptocurrency prices.
The key points from this earnings report are as follows:
1. At the end of the second quarter, the company held more than 8,000 bitcoins, up 14% from the previous quarter.
2. The company continued to increase investment in its bitcoin mining business. In the second quarter, it mined about 932 bitcoins, setting a record high for a single quarter.
3. From April to June this year, the price of bitcoin fell cumulatively by more than 11%.
4. CEO Mike Ho said: “Despite headwinds in the bitcoin market in the second quarter, we remain focused on doing what we can control.”
5. The company posted a net loss of $57.2 million in the second quarter, compared with a net profit of $3.4 million in the same period last year.
6. Second-quarter revenue was approximately $67 million, up from $30.3 million in the same period last year.
Despite a sharp year-over-year increase in revenue, the value of the company’s bitcoin assets was affected as the bitcoin price fell noticeably in the second quarter, ultimately leading to an overall performance that turned to a loss.
$BTC
{future}(BTCUSDT)
August 3 (Reuters) — American Bitcoin, supported by two of U.S. President Donald Trump’s sons, announced on Monday, reporting a swing to a loss in the second quarter due to a decline in the price of bitcoin.
As geopolitical tensions intensified, risk-averse sentiment grew in the market, prompting investors to reduce allocations to risk assets and putting broad pressure on cryptocurrency prices.
The key points from this earnings report are as follows:
1. At the end of the second quarter, the company held more than 8,000 bitcoins, up 14% from the previous quarter.
2. The company continued to increase investment in its bitcoin mining business. In the second quarter, it mined about 932 bitcoins, setting a record high for a single quarter.
3. From April to June this year, the price of bitcoin fell cumulatively by more than 11%.
4. CEO Mike Ho said: “Despite headwinds in the bitcoin market in the second quarter, we remain focused on doing what we can control.”
5. The company posted a net loss of $57.2 million in the second quarter, compared with a net profit of $3.4 million in the same period last year.
6. Second-quarter revenue was approximately $67 million, up from $30.3 million in the same period last year.
Despite a sharp year-over-year increase in revenue, the value of the company’s bitcoin assets was affected as the bitcoin price fell noticeably in the second quarter, ultimately leading to an overall performance that turned to a loss.
$BTC
1
256
·
--
A few days ago, I sat down with some friends who work on nodes and we went through the Babylon whitepaper. We got to the part about withdrawal review under extreme conditions, and I was honestly shocked. The protocol makes a hardcore guarantee: even if every node running the PoS chain all defect and team up to impose a shutdown—if you follow the rules, the BTC should still be unbonded/withdrawable. No getting blocked at all!
After mixing in this space for so many years, who doesn’t know what PoS chains are like? If the big node set collectively does evil, or the chain itself can’t produce a block, our assets are essentially just being held hostage. I originally assumed this was just another project’s hype. But once I dug deeper, I found out they’ve written the rules into Bitcoin’s mainnet using cryptography.
It’s like going to an arcade, putting your coins into the boss’s safe. Under the old rules, if the boss runs off with the money or locks up the place and shuts the door, you can only take the loss. Here’s where Babylon is impressive: it directly locks our coins behind its own tamper-proof “door” on-chain. In the arcade, what’s sitting there is just a digital counter. Even if the arcade burns down to ashes, you can still go back to your own home, turn the key, and retrieve the coins exactly as they were—no changes.
My argument is extremely simple: the safety of your exit doesn’t depend on whether that PoS chain lives or dies at all—it only depends on whether the Bitcoin network is reliable. It’s like wrapping risk assets with an unbeatable shield. Previously, participating in staking on a new chain was basically “using principal to earn interest.” With this mechanism, it directly exposes the key safety of the principal and separates it from the systemic risks of the new chain.
Going forward, when evaluating staking projects like this, don’t just listen to how grand the project team’s narrative is. Whether they can truly do: “the chain is broken, but the money is still there”—that is the toughest test of whether it’s real. This is the most genuine thought I have, and in the future I’ll evaluate things using this theory as well.
@babylonlabs_io #baby $BABY
(Ad.Do Your Own Research.)
{spot}(BABYUSDT)
A few days ago, I sat down with some friends who work on nodes and we went through the Babylon whitepaper. We got to the part about withdrawal review under extreme conditions, and I was honestly shocked. The protocol makes a hardcore guarantee: even if every node running the PoS chain all defect and team up to impose a shutdown—if you follow the rules, the BTC should still be unbonded/withdrawable. No getting blocked at all!
After mixing in this space for so many years, who doesn’t know what PoS chains are like? If the big node set collectively does evil, or the chain itself can’t produce a block, our assets are essentially just being held hostage. I originally assumed this was just another project’s hype. But once I dug deeper, I found out they’ve written the rules into Bitcoin’s mainnet using cryptography.
It’s like going to an arcade, putting your coins into the boss’s safe. Under the old rules, if the boss runs off with the money or locks up the place and shuts the door, you can only take the loss. Here’s where Babylon is impressive: it directly locks our coins behind its own tamper-proof “door” on-chain. In the arcade, what’s sitting there is just a digital counter. Even if the arcade burns down to ashes, you can still go back to your own home, turn the key, and retrieve the coins exactly as they were—no changes.
My argument is extremely simple: the safety of your exit doesn’t depend on whether that PoS chain lives or dies at all—it only depends on whether the Bitcoin network is reliable. It’s like wrapping risk assets with an unbeatable shield. Previously, participating in staking on a new chain was basically “using principal to earn interest.” With this mechanism, it directly exposes the key safety of the principal and separates it from the systemic risks of the new chain.
Going forward, when evaluating staking projects like this, don’t just listen to how grand the project team’s narrative is. Whether they can truly do: “the chain is broken, but the money is still there”—that is the toughest test of whether it’s real. This is the most genuine thought I have, and in the future I’ll evaluate things using this theory as well.
@BabylonLabs_io #baby $BABY
(Ad.Do Your Own Research.)
4
4
259
·
--
Article
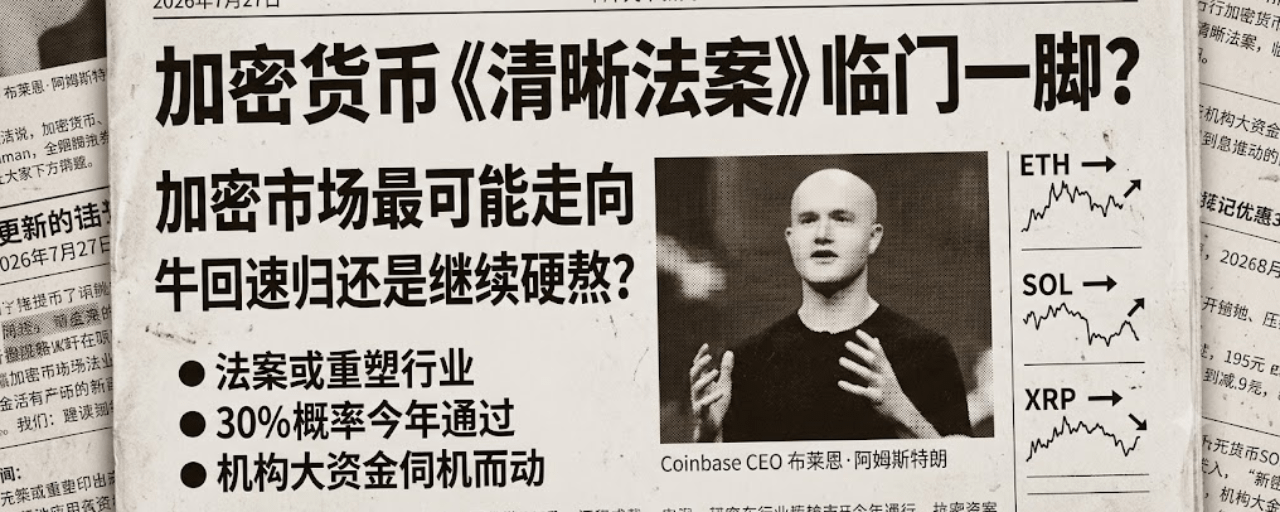
The (clear act) “right at the doorstep”? Institutions won’t move in, retail traders end up hurting each other—how much longer will this bear market just play dead?Why keep talking about the (clear act) every day? What exactly is this bill?
Coinbase’s big boss, Armstrong, recently went on CNBC to fan the flames and said that the (clear act) has already reached the “last step.” If this actually gets passed, then our ETH, XRP, and SOL definitely can cash in on a big red-bag windfall—short-term and long-term alike, it’s all real gold and silver you can actually get your hands on!
But! Institutional projections say there’s only a 30% chance it can pass this year… That’s just too depressing, right?!
A lot of people are wondering: didn’t the SEC and CFTC issue statements not long ago saying that Bitcoin, Ethereum, SOL, XRP—this bunch of hard currencies—are “commodities,” not “securities”? Then why are they still pushing for this bill?
The (clear act) “right at the doorstep”? Institutions won’t move in, retail traders end up hurting each other—how much longer will this bear market just play dead?
Why keep talking about the (clear act) every day? What exactly is this bill?
Coinbase’s big boss, Armstrong, recently went on CNBC to fan the flames and said that the (clear act) has already reached the “last step.” If this actually gets passed, then our ETH, XRP, and SOL definitely can cash in on a big red-bag windfall—short-term and long-term alike, it’s all real gold and silver you can actually get your hands on!
But! Institutional projections say there’s only a 30% chance it can pass this year… That’s just too depressing, right?!
A lot of people are wondering: didn’t the SEC and CFTC issue statements not long ago saying that Bitcoin, Ethereum, SOL, XRP—this bunch of hard currencies—are “commodities,” not “securities”? Then why are they still pushing for this bill?
1
5
1.3k
·
--
Partly True
Your performance this year has been too bad—$NVDA . In past years, the first half was just casually outperforming the market index, but this year—so far—it’s only up 2%. It hasn’t even beaten the S&P 500’s 7% gain.
There’s a saying that once the earnings report drops on August 26, NVIDIA might really take off—skyrocket. The logic is pretty simple: in AI computing power, it’s still “hard currency.” All the big players are going on a buying spree for capacity. And the forward P/E ratio is only 21x right now, which makes it cheap—basically priced like an ordinary large-cap stock. If Q2 revenue breaks 100 and the Q3 guidance beats expectations, then this upswing is absolutely solid. I’d urge everyone to hurry and pick up shares on the cheap.
NVIDIA really does have strong fundamentals. In this wave of AI, compute power is a necessity. The “leather jacket yellow” GPUs are an industry-wide consensus as unbeatable—if the big companies aren’t buying it, then who would they buy? The fundamentals are still scorching hot. If the earnings report delivers a genuine upside surprise and really ramps up, it can absolutely rip a huge green candle in minutes and blow up the shorts.
But the risks are there too. If it can’t move higher this year, doesn’t that just mean the money is still hesitating? If the macro economy even gets a slight change in tone, or if the earnings guidance misses Wall Street’s picky expectations by even a tiny bit, it could turn into an immediate sell-off—bearish pressure. And that script of “good news being followed by bad news once it’s already out”—haven’t we retail investors been getting cut enough already?
On August 26, this big test—are you planning to set up early positions and wait for takeoff, or continue working and watching from the sidelines?
$NVDAB $NVDA.US
{stock_us}(NVDA.US)
{spot}(NVDABUSDT)
Your performance this year has been too bad—$NVDA . In past years, the first half was just casually outperforming the market index, but this year—so far—it’s only up 2%. It hasn’t even beaten the S&P 500’s 7% gain.
There’s a saying that once the earnings report drops on August 26, NVIDIA might really take off—skyrocket. The logic is pretty simple: in AI computing power, it’s still “hard currency.” All the big players are going on a buying spree for capacity. And the forward P/E ratio is only 21x right now, which makes it cheap—basically priced like an ordinary large-cap stock. If Q2 revenue breaks 100 and the Q3 guidance beats expectations, then this upswing is absolutely solid. I’d urge everyone to hurry and pick up shares on the cheap.
NVIDIA really does have strong fundamentals. In this wave of AI, compute power is a necessity. The “leather jacket yellow” GPUs are an industry-wide consensus as unbeatable—if the big companies aren’t buying it, then who would they buy? The fundamentals are still scorching hot. If the earnings report delivers a genuine upside surprise and really ramps up, it can absolutely rip a huge green candle in minutes and blow up the shorts.
But the risks are there too. If it can’t move higher this year, doesn’t that just mean the money is still hesitating? If the macro economy even gets a slight change in tone, or if the earnings guidance misses Wall Street’s picky expectations by even a tiny bit, it could turn into an immediate sell-off—bearish pressure. And that script of “good news being followed by bad news once it’s already out”—haven’t we retail investors been getting cut enough already?
On August 26, this big test—are you planning to set up early positions and wait for takeoff, or continue working and watching from the sidelines?
$NVDAB $NVDA .US
1
509
·
--
$BTC Since last year’s peak at 126,000, it was cut in half by 50%. The drawdown in a bear market is gradually becoming shallower: it fell 94% in 11 years, 86% in 13 years, 78% in 22 years, and so far this year it’s down only 54%. So some people think the selling pressure is easing, and a rebound is on the way.
The community’s “four-year halving” consensus for BTC is really like a mark burned into everyone’s mind. Even if it drops terribly, that emotion and belief in the community can’t be extinguished. Plus, the drawdown really does seem to be getting smaller now—it looks like there’s genuine confidence at the bottom.
But for a bigger part of people, the heart is both itchy and panicked.
Why do everyone feel so uneasy?
Because these analyses are all based on historical patterns. But can history really represent the future? Can today’s macro environment be the same as before? What if this time it doesn’t follow the script? A 50% cut looks like a discount, but if you try to buy in halfway down, the remaining 50% can still make you bleed.
So when you’re itching to buy the dip, you also end up second-guessing: is the bottom really in for real? If you buy the dip, you’re afraid it’ll keep dropping. If you don’t buy, you’re afraid your legs get crushed.
Brothers, right now are you lying flat and pretending to be dead, preparing to build positions in batches, or are you continuing to watch from the sidelines? Leave a comment—when there’s money, we all make it together.
$BTC
{future}(BTCUSDT)
$BTC Since last year’s peak at 126,000, it was cut in half by 50%. The drawdown in a bear market is gradually becoming shallower: it fell 94% in 11 years, 86% in 13 years, 78% in 22 years, and so far this year it’s down only 54%. So some people think the selling pressure is easing, and a rebound is on the way.
The community’s “four-year halving” consensus for BTC is really like a mark burned into everyone’s mind. Even if it drops terribly, that emotion and belief in the community can’t be extinguished. Plus, the drawdown really does seem to be getting smaller now—it looks like there’s genuine confidence at the bottom.
But for a bigger part of people, the heart is both itchy and panicked.
Why do everyone feel so uneasy?
Because these analyses are all based on historical patterns. But can history really represent the future? Can today’s macro environment be the same as before? What if this time it doesn’t follow the script? A 50% cut looks like a discount, but if you try to buy in halfway down, the remaining 50% can still make you bleed.
So when you’re itching to buy the dip, you also end up second-guessing: is the bottom really in for real? If you buy the dip, you’re afraid it’ll keep dropping. If you don’t buy, you’re afraid your legs get crushed.
Brothers, right now are you lying flat and pretending to be dead, preparing to build positions in batches, or are you continuing to watch from the sidelines? Leave a comment—when there’s money, we all make it together.
$BTC
2
4
898
·
--
Still, here’s the same saying: making slow money is nothing to be ashamed of!
Dividend stocks can be a very powerful investment tool. Thanks to the compounding effect, even an initial amount of money that isn’t very large can, over time, grow like a snowball into a substantial asset.
Dividends within the S&P 500 $SPY index have an average annual total return of 9.2% over the past 50 years—more than double the return of non-dividend stocks (4.2%).
First, we have to admit: this traditional U.S. stock strategy of “lying back and living off dividends” really does have its tricks. Look at an index like VYM—it holds shares of more than 600 high-quality large companies, with cash flow supporting it every day. It’s rock-solid.
What you’re selling is “strong consensus” and “low risk,” relying on time and compounding to slowly grow a snowball.
The emotional payoff is plenty—at least it lets you sleep soundly at night. You don’t have to be like us in crypto, where you wake up at 3 a.m. to check the market with your phone, worrying that your position will be wiped out and there won’t be a trace left!
But don’t forget: in the crypto world, people can’t make slow money—they’ll get driven crazy!
Honestly, an annualized return of a bit over 9% is considered pretty good on the U.S. stock market, but in the eyes of crypto people, this pace is so slow it’s like a turtle crawling. What are we getting into for? Aren’t we all here for 100x coins, 1,000x coins? If you really let crypto people put $1,000 in and wait 20 years to turn it into $6,000, they’d probably be so anxious they’d start scratching their ears and cheeks. $VYM.ETF $SPY.ETF
{etf_us}(SPY.ETF)
{etf_us}(VYM.ETF)
Still, here’s the same saying: making slow money is nothing to be ashamed of!
Dividend stocks can be a very powerful investment tool. Thanks to the compounding effect, even an initial amount of money that isn’t very large can, over time, grow like a snowball into a substantial asset.
Dividends within the S&P 500 $SPY index have an average annual total return of 9.2% over the past 50 years—more than double the return of non-dividend stocks (4.2%).
First, we have to admit: this traditional U.S. stock strategy of “lying back and living off dividends” really does have its tricks. Look at an index like VYM—it holds shares of more than 600 high-quality large companies, with cash flow supporting it every day. It’s rock-solid.
What you’re selling is “strong consensus” and “low risk,” relying on time and compounding to slowly grow a snowball.
The emotional payoff is plenty—at least it lets you sleep soundly at night. You don’t have to be like us in crypto, where you wake up at 3 a.m. to check the market with your phone, worrying that your position will be wiped out and there won’t be a trace left!
But don’t forget: in the crypto world, people can’t make slow money—they’ll get driven crazy!
Honestly, an annualized return of a bit over 9% is considered pretty good on the U.S. stock market, but in the eyes of crypto people, this pace is so slow it’s like a turtle crawling. What are we getting into for? Aren’t we all here for 100x coins, 1,000x coins? If you really let crypto people put $1,000 in and wait 20 years to turn it into $6,000, they’d probably be so anxious they’d start scratching their ears and cheeks. $VYM.ETF $SPY .ETF
154
·
--
Let’s take a look back at how $SPCX % came out with what was described as the biggest IPO in history. The offering price was $135, and it shot up to $225—holy wow. But now it’s directly kept sliding all the way down to $109, which is 19% below the offering price.!
Everyone compares it to $TSLA from back then. When Tesla first went public, it also crashed by 18%, but didn’t it eventually turn around? SpaceX is after all Musk’s own child, so the fundamentals are still solid. If Starship really gets going, launch costs will come down significantly, and Starlink satellites will be deployed at full speed. The storytelling and “vision-casting” capabilities here are top-tier—arguably among the best across the entire U.S. stock market and even the crypto world. Consensus and belief are basically maxed out!
It’s absolutely worth putting on your watchlist and keeping a close eye on. Once it has fallen enough, or if Starship’s tests truly succeed and performance shows a turnaround, then we can consider buying the dip—no rush.
{future}(TSLAUSDT)
{future}(SPCXUSDT)
Let’s take a look back at how $SPCX % came out with what was described as the biggest IPO in history. The offering price was $135, and it shot up to $225—holy wow. But now it’s directly kept sliding all the way down to $109, which is 19% below the offering price.!
Everyone compares it to $TSLA from back then. When Tesla first went public, it also crashed by 18%, but didn’t it eventually turn around? SpaceX is after all Musk’s own child, so the fundamentals are still solid. If Starship really gets going, launch costs will come down significantly, and Starlink satellites will be deployed at full speed. The storytelling and “vision-casting” capabilities here are top-tier—arguably among the best across the entire U.S. stock market and even the crypto world. Consensus and belief are basically maxed out!
It’s absolutely worth putting on your watchlist and keeping a close eye on. Once it has fallen enough, or if Starship’s tests truly succeed and performance shows a turnaround, then we can consider buying the dip—no rush.
5
3
2.5k
·
--
Monster drinks—yes, that monster energy. It’s announced it will “split” into 1 and 2. For just $200, you can get on board. Friends who want to try a small test finally have a chance to buy.
$MNST.US
{stock_us}(MNST.US)
It really does kind of look like the “100x black horse” from our crypto circle. Look at its consensus—it’s extremely terrifying. Backed by Coca-Cola, the world’s biggest top-tier player, it gets the pipeline built, traffic delivered, and people all over the world are buying its orders. You can buy it anywhere.
And its marketing is super good at understanding young people—everything is covered: esports, extreme sports, and racing. The emotional value gets maxed out directly. The brand loyalty is rock solid. Honestly, that’s impressive. This level of consensus is ten thousand times stronger than most “air coins,” okay?
New products are also being released nonstop—just like the project teams in our crypto circle updating the roadmap every day—so the buzz stays strong all the time.
If you treat it as a leading asset with real business support, extremely strong community consensus, and steady expansion, then taking $200 as pocket money to buy some spot and hold it is definitely more solid than all those tiny air-coin projects we’re always trading that can go to zero at any moment.
(Not investment advice)
Monster drinks—yes, that monster energy. It’s announced it will “split” into 1 and 2. For just $200, you can get on board. Friends who want to try a small test finally have a chance to buy.
$MNST.US
It really does kind of look like the “100x black horse” from our crypto circle. Look at its consensus—it’s extremely terrifying. Backed by Coca-Cola, the world’s biggest top-tier player, it gets the pipeline built, traffic delivered, and people all over the world are buying its orders. You can buy it anywhere.
And its marketing is super good at understanding young people—everything is covered: esports, extreme sports, and racing. The emotional value gets maxed out directly. The brand loyalty is rock solid. Honestly, that’s impressive. This level of consensus is ten thousand times stronger than most “air coins,” okay?
New products are also being released nonstop—just like the project teams in our crypto circle updating the roadmap every day—so the buzz stays strong all the time.
If you treat it as a leading asset with real business support, extremely strong community consensus, and steady expansion, then taking $200 as pocket money to buy some spot and hold it is definitely more solid than all those tiny air-coin projects we’re always trading that can go to zero at any moment.
(Not investment advice)
641
·
--
They say the first sip of Coca-Cola is worth half the price of the whole bottle.
Coca-Cola—do you pick Coca-Cola or Pepsi?
Recently, when Coca-Cola released its Q2 earnings report, the stock price shot up immediately.
Some people came to look at the numbers, saying Pepsi’s P/E ratio is only 19x and its dividend yield is 4%, while Coca-Cola’s P/E is 27x and its dividend yield is just 2.3%. Why is it so expensive? Isn’t this just cutting into shareholders?
Coca-Cola, if you boil it down, is basically good at one thing: light assets and pure focus.
It outsources the most cash-burning and labor-intensive bottling, trucking, and delivery to third parties. It only sells concentrate and takes the lion’s share of the profits.
And it commits to beverages. Unlike Pepsi, which also has a whole bunch of snacks like Lay’s potato chips and Quaker oats. These days, everyone is chasing health and eating less processed food. Pepsi’s snack business has higher costs and more pressure. Coca-Cola, with its light-asset model, has a profit margin that’s honestly frightening.
Don’t forget what’s most powerful of all: consensus. From 1990 to now, Coca-Cola’s long-term return has nearly always outperformed Pepsi. If you’ve spent enough time in crypto, you know how valuable “consensus” is—it’s basically a belief premium.
By the way: I pick Coca-Cola.
When you usually buy drinks, which one do you choose?
$KOon
{alpha}(560x405f38b90bebf1259062cf29da299f3398662bcb)
{alpha}(560x2d739dd563609c39a1ae1546a03e8b469361175f)
They say the first sip of Coca-Cola is worth half the price of the whole bottle.
Coca-Cola—do you pick Coca-Cola or Pepsi?
Recently, when Coca-Cola released its Q2 earnings report, the stock price shot up immediately.
Some people came to look at the numbers, saying Pepsi’s P/E ratio is only 19x and its dividend yield is 4%, while Coca-Cola’s P/E is 27x and its dividend yield is just 2.3%. Why is it so expensive? Isn’t this just cutting into shareholders?
Coca-Cola, if you boil it down, is basically good at one thing: light assets and pure focus.
It outsources the most cash-burning and labor-intensive bottling, trucking, and delivery to third parties. It only sells concentrate and takes the lion’s share of the profits.
And it commits to beverages. Unlike Pepsi, which also has a whole bunch of snacks like Lay’s potato chips and Quaker oats. These days, everyone is chasing health and eating less processed food. Pepsi’s snack business has higher costs and more pressure. Coca-Cola, with its light-asset model, has a profit margin that’s honestly frightening.
Don’t forget what’s most powerful of all: consensus. From 1990 to now, Coca-Cola’s long-term return has nearly always outperformed Pepsi. If you’ve spent enough time in crypto, you know how valuable “consensus” is—it’s basically a belief premium.
By the way: I pick Coca-Cola.
When you usually buy drinks, which one do you choose?
$KOon
可口可乐
100%
百事可乐
0%
4 votes • Voting closed
4
1
654
·
--
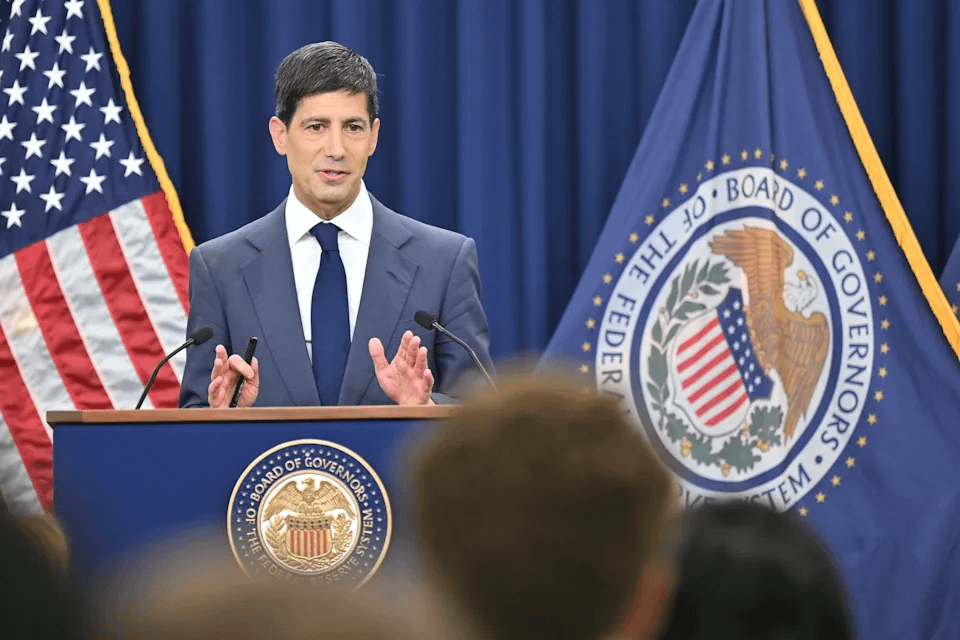
I thought that if the Federal Reserve had a new chair, they could roll out some big rescue-market moves. But in the first press conference after Waller took office, he managed to throw the bond market into chaos!
Interest rates haven’t changed—still 3.5%~3.75%—but his remarks were hesitant and contradictory, and he basically couldn’t clearly explain whether they’ll keep raising rates afterward.
Wall Street was left completely dumbfounded.
In plain terms, what the market fears most is “uncertainty.” When those old foxes in the bond market see the Fed’s stance is so vague, they don’t believe the Fed can bring inflation down. They immediately start wildly selling off and dumping Treasuries.
So what happened? The yield on 30-year U.S. Treasuries shot up straight to 5.23%, hitting a 19-year high. With interest rates that high, borrowing gets more expensive for the government, businesses, and ordinary people alike—hurting long-term Treasury funds they hold as well.
In this macro environment, with inflation not coming down and the Fed playing ping-pong with its communications, the risk of blindly jumping into tools with a long duration is just too high. Instead of betting that the long-term trend will reverse, it’s better to stick with some intermediate-to-short-term products first to protect your principal.
482
·
--
$BABY Want to uphold the fundamentals—the key lies in whether its Trustless Bitcoin Vaults (TBV) can, while ensuring the safety of BTC assets, establish a predictable ecosystem order.
Did some of you previously misunderstand that once BTC is locked in a vault, the Vault Provider might “raise the price on the spot” and temporarily jack up commissions when users redeem and exit? That is a complete misreading of the underlying technology.
TBV’s actual operating mechanism is very hardcore: in the very second the vault is initially created, the pre-signed Payout transaction already permanently locks the provider’s profit-sharing ratio into the contract parameters. At final settlement, the system automatically deducts directly according to the pre-established code.
What does this mean for our real operations? First, the node absolutely cannot backstab you with a price increase when you’re preparing to exit; second, it also means “one vote until the end”—once the vault is generated, you lose the power to switch vehicles halfway, i.e., to switch providers.
So my current pool-selection strategy has changed: I absolutely won’t just look at which one takes a lower cut—I have to closely track the node’s historical availability rate and resilience under pressure. Just because it runs smoothly on the testnet doesn’t mean it won’t fall behind chains under extreme conditions on the mainnet. Only mechanisms that clearly spell out the restrictions in the rules truly have long-term value.
#baby @babylonlabs_io
$BABY Want to uphold the fundamentals—the key lies in whether its Trustless Bitcoin Vaults (TBV) can, while ensuring the safety of BTC assets, establish a predictable ecosystem order.
Did some of you previously misunderstand that once BTC is locked in a vault, the Vault Provider might “raise the price on the spot” and temporarily jack up commissions when users redeem and exit? That is a complete misreading of the underlying technology.
TBV’s actual operating mechanism is very hardcore: in the very second the vault is initially created, the pre-signed Payout transaction already permanently locks the provider’s profit-sharing ratio into the contract parameters. At final settlement, the system automatically deducts directly according to the pre-established code.
What does this mean for our real operations? First, the node absolutely cannot backstab you with a price increase when you’re preparing to exit; second, it also means “one vote until the end”—once the vault is generated, you lose the power to switch vehicles halfway, i.e., to switch providers.
So my current pool-selection strategy has changed: I absolutely won’t just look at which one takes a lower cut—I have to closely track the node’s historical availability rate and resilience under pressure. Just because it runs smoothly on the testnet doesn’t mean it won’t fall behind chains under extreme conditions on the mainnet. Only mechanisms that clearly spell out the restrictions in the rules truly have long-term value.
#baby @BabylonLabs_io
1
2
293
·
--
Saw $AMZN shares and it was pulled up by 10% right before the opening bell. In a single quarter, AWS revenue hit $42.2 billion, and the unfulfilled orders have piled up to nearly $500 billion. What’s the most hardcore part? Their CEO said it directly: the compute demand for 2027 has already been booked through reservations for 2028.
The biggest value that this kind of performance from traditional tech giants provides to the market is a sense of “security.” In an environment full of uncertainty, people with a bit of money don’t dare to invest recklessly. But Amazon has backed the real AI and cloud-computing deployment needs with hard cash—by delivering performance and orders.
This real demand also helps to lay the groundwork for AI or decentralized compute projects in our crypto circle (for example, DePIN). The logic is simple: if even the top-tier traditional giants can’t supply enough compute capacity, then it shows the industry truly has demand for compute throughput—not some bubble being inflated out of thin air.
That said, we still need to stay clear-headed. Don’t get carried away and start placing buy orders for all kinds of “AI concept coins” just because you’re excited. US stock giants have extremely powerful cash flows and tough hardware moats—they earn real, tangible profits. Meanwhile, many projects in our space are still at the stage of telling stories and selling emotions, with significant limitations and bubbles.
So, look at the giants’ financial reports—mainly to help you see the big direction ahead. Whether it’s the US stock market or the crypto market, at the end of the day you still need to focus on things that have real demand and real deployment capability. Listen less to slogans, protect your principal. When the market is good, don’t miss the move; when the market is volatile, you can still sleep at night. That’s the most practical—right, guys?
$AMZN
{future}(AMZNUSDT)
Saw $AMZN shares and it was pulled up by 10% right before the opening bell. In a single quarter, AWS revenue hit $42.2 billion, and the unfulfilled orders have piled up to nearly $500 billion. What’s the most hardcore part? Their CEO said it directly: the compute demand for 2027 has already been booked through reservations for 2028.
The biggest value that this kind of performance from traditional tech giants provides to the market is a sense of “security.” In an environment full of uncertainty, people with a bit of money don’t dare to invest recklessly. But Amazon has backed the real AI and cloud-computing deployment needs with hard cash—by delivering performance and orders.
This real demand also helps to lay the groundwork for AI or decentralized compute projects in our crypto circle (for example, DePIN). The logic is simple: if even the top-tier traditional giants can’t supply enough compute capacity, then it shows the industry truly has demand for compute throughput—not some bubble being inflated out of thin air.
That said, we still need to stay clear-headed. Don’t get carried away and start placing buy orders for all kinds of “AI concept coins” just because you’re excited. US stock giants have extremely powerful cash flows and tough hardware moats—they earn real, tangible profits. Meanwhile, many projects in our space are still at the stage of telling stories and selling emotions, with significant limitations and bubbles.
So, look at the giants’ financial reports—mainly to help you see the big direction ahead. Whether it’s the US stock market or the crypto market, at the end of the day you still need to focus on things that have real demand and real deployment capability. Listen less to slogans, protect your principal. When the market is good, don’t miss the move; when the market is volatile, you can still sleep at night. That’s the most practical—right, guys?
$AMZN
203
·
--
Article
Buying an iPhone later will become more expensive. Tim Cook’s AI killer move left behind before stepping down: Edge computing cuts costs and boosts efficiency—can it overturn the rules of the cloud computing giants’ game?Before stepping down, Apple CEO Tim Cook delivered remarks: Edge AI is Apple’s core competitive advantage
The following are the core points I summarized for you:
Edge AI strategy advantages: In the last earnings call before taking on the role of executive chairman on September 1, Apple CEO Tim Cook emphasized that running part of the AI requests locally on the device is Apple’s “extremely high strategic advantage and competitive edge” compared with cloud-based competitors. Apple’s focus is on a hybrid architecture—lightweight tasks are handled locally by its built-in chips, while complex tasks are routed to the cloud.
Low capital expenditure and cost advantages: Compared with the massive capital expenditures of over $10 billion this year from Alphabet, Amazon, Meta, and Microsoft, Apple’s capital expenditure in the June quarter was only $2.46 billion. Cook said Apple is increasing its operational expense investment related to AI. He used Disney as an example, noting that its team is running edge-AI workflows on Macs, effectively lowering cloud token costs and ensuring IP security.
Buying an iPhone later will become more expensive. Tim Cook’s AI killer move left behind before stepping down: Edge computing cuts costs and boosts efficiency—can it overturn the rules of the cloud computing giants’ game?
Before stepping down, Apple CEO Tim Cook delivered remarks: Edge AI is Apple’s core competitive advantage
The following are the core points I summarized for you:
Edge AI strategy advantages: In the last earnings call before taking on the role of executive chairman on September 1, Apple CEO Tim Cook emphasized that running part of the AI requests locally on the device is Apple’s “extremely high strategic advantage and competitive edge” compared with cloud-based competitors. Apple’s focus is on a hybrid architecture—lightweight tasks are handled locally by its built-in chips, while complex tasks are routed to the cloud.
Low capital expenditure and cost advantages: Compared with the massive capital expenditures of over $10 billion this year from Alphabet, Amazon, Meta, and Microsoft, Apple’s capital expenditure in the June quarter was only $2.46 billion. Cook said Apple is increasing its operational expense investment related to AI. He used Disney as an example, noting that its team is running edge-AI workflows on Macs, effectively lowering cloud token costs and ensuring IP security.
1
270
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
EtherGains70.9%InQ3
58,789 views
709 Discussing
One of the best third quarters in history 💰
September closed out last night, and with it, the quarter. For the quarter, BTC is up 42%—the second-best Q3 on record. ETH had a record-breaking Q3 overall, up 70%.
Looking at the chart, things are still looking good: we’re holding support, but we’re testing it more and more often. Plus, ETF momentum is weakening — inflows are gradually declining, and yesterday saw outflows for the first time in a long while.
Yes, historically, October has been a good month for crypto — it’s not called “Uptober” for nothing. But it’s also one of the most volatile months. Last year, for example, we managed to hit a new all-time high (ATH) and experience a flash crash.
🚀 High Accuracy Trades.
$BTC
$ETH
$SOL
#EtherGains70.9%InQ3 #DollarIndexHitsHighestSinceMay2025 #CFTCSubmitsTwoEventContractRulesToWhiteHouse #MicronBeatsEarningsLiftsGuidance
Knowledge is Power
·0 Likes
·144 views
TreasuryLetsStatesFileStablecoinCertificationsEarly
2,338 views
31 Discussing
US10YearYieldNears5.3%
91,120 views
860 Discussing