

币圈女菩萨
1k Posts

币圈女菩萨
 Square Verified
Report
Block User
我瞎说我的,您随意看

マクロ経済KOL
22 Following
522 Followers
496 Liked
1 Badges
Posts
·
--
UPS completed planned reductions with its largest customer in the second quarter, and in the third quarter both revenue and adjusted operating profit in its U.S. domestic business increased. After handling fewer packages, has the business improved? Tonight’s earnings report provides new evidence.
Average daily package volume in the U.S. domestic segment fell by about 3.3% year over year, yet revenue rose 4.5%, and adjusted operating profit margin increased from 6.4% to 7%. I think this round of adjustments is starting to pay off. The decline in volume has not prevented this segment from generating more profit, and the support it provides for UPS’s stock price is more convincing than simply increasing package volume.
However, the group’s adjusted operating profit was still lower than the same period last year. In the supply chain solutions business, last year included a gain from a sale-leaseback transaction, which boosted the comparison base.
Restructuring still comes at a cost. The company expects related adjustment expenses of $1.4 billion to $1.6 billion this year, and the efficiency transformation is expected to continue through the fourth quarter of 2027. When assessing how much profit this round of adjustments can leave for shareholders, these expenses excluded from adjusted metrics also need to be taken into account.
36
·
--
Bitmine bought another 10,452 ETH last week and also repurchased 2.04 million of its own shares. It is still adding buying pressure to ETH, but the company is also willing to spend money on its own stock.
According to its October 26 announcement, as of the 25th it held about 6.05 million ETH, or 4.95% of the total supply, putting it within reach of its 5% target. Continued accumulation is good for ETH, but that target doesn’t tell us how much more it will buy once it gets there, and the announcement doesn’t say it will stop buying at 5%.
Management says it will consider repurchases when it believes the company’s stock is relatively undervalued. I think we need to keep judging this crypto treasury company’s support for ETH by how many coins it actually buys, rather than focusing only on its holdings nearing 5%. Buybacks don’t add buying pressure to ETH, but we also can’t conclude from this repurchase alone that it means the company bought that much less ETH. The company is spending money on both ETH and buybacks, and the announcement doesn’t say how much it plans to spend on ETH going forward.
67
·
--
Celestica (CLS) has set a revenue target of $40 billion for next year, nearly double this year’s expected revenue, while preparing to invest $1.5 billion to $2 billion in capital expenditures. The company is preparing capacity in advance based on customers’ demand forecasts for this year and next, but those forecasts should not yet be treated as revenue already secured.
In the third quarter, revenue from its cloud and connectivity business doubled year over year, while the company’s overall adjusted operating margin rose to 8.5% from 7.6% a year earlier. This expansion is backed by businesses that are already growing.
The company also lowered its free cash flow forecast for this year from $600 million to $460 million, explaining that the main reason was increased working-capital investment ahead of next year’s growth. Proceeds from its August share offering are also earmarked for working capital and capital expenditures. I think this cash flow downgrade looks more like spending in advance to support expansion, and is not inconsistent with the revenue already delivered and the improvement in adjusted operating margins.
The share offering increased the number of shares outstanding, so future profits will also have to be divided among more shares. If customers delay deployments, the additional capacity could sit idle and cash collection could slow. For expansion to benefit CLS’s share price, it will need to translate into higher deliveries and growth in earnings per share; the near-doubling of the revenue target alone is not enough to justify that.
1
112
·
--
Franklin plans to turn U.S. stock dividends into $BTC exposure. The two new ETFs are tickered FBEQ and FIBT. Investors who are primarily invested in stocks can gradually add Bitcoin exposure within the same portfolio, without having to reinvest dividends in stocks.
The indexes tracked by both funds initially allocate 5% to Bitcoin, then continue directing stock dividends into Bitcoin. At quarterly rebalancing, however, if BTC exposure exceeds 5%, it is reduced to 4.5%; if it has not exceeded 5%, it remains unchanged. If BTC rises more than stocks, that could trigger a reduction in the allocation, so reinvesting dividends won’t make the position grow indefinitely.
The funds will gain exposure through instruments such as Bitcoin ETPs, futures, and options, and may not buy Bitcoin directly. How much capital the products attract and which instruments they actually use will affect how much they contribute to demand for spot BTC. The filing submitted on October 22 confirms the product design, but it isn’t enough to determine how much additional buying demand has already been created.
If the funds can attract people who previously bought only stocks and are willing to allocate a small portion of their money to BTC, I think this design could help support Bitcoin’s long-term demand. But that support will depend on the funds growing over time. The fact that dividends will be invested continuously shouldn’t lead us to overlook the potential offsetting adjustments from quarterly reductions in the allocation.
167
·
--
BNB Chain is preparing to build another L1. Under the current plan, fees and staking will continue to use $BNB, with no new tradable token being issued. I think this choice is more beneficial to existing holders. If the new chain can build up trading and payment activity, demand for the token will still accrue to BNB.
For now, the chain is called New L1. It aims to support activities that require high speeds, such as high-frequency trading and real-time payments. The current development network has a block time of 200 milliseconds, but neither the public testnet nor the mainnet is open yet, and the bridge connecting it to BSC is still under development. Since public network data is not yet available, we can’t judge how much activity it will attract based on this speed metric alone.
To assess how much it could benefit BNB, we also need to distinguish where the activity comes from. If BSC’s existing users simply move over, BNB will be used on another chain, but overall demand may not increase. Attracting new applications and capital is more likely to increase demand for fees and staking. So I support continuing to use BNB, but once the new chain launches, if it mainly takes on trading that already takes place on BSC, we shouldn’t count demand on both chains twice.
BNB Chain is preparing to build another L1. Under the current plan, fees and staking will continue to use $BNB , with no new tradable token being issued. I think this choice is more beneficial to existing holders. If the new chain can build up trading and payment activity, demand for the token will still accrue to BNB.
For now, the chain is called New L1. It aims to support activities that require high speeds, such as high-frequency trading and real-time payments. The current development network has a block time of 200 milliseconds, but neither the public testnet nor the mainnet is open yet, and the bridge connecting it to BSC is still under development. Since public network data is not yet available, we can’t judge how much activity it will attract based on this speed metric alone.
To assess how much it could benefit BNB, we also need to distinguish where the activity comes from. If BSC’s existing users simply move over, BNB will be used on another chain, but overall demand may not increase. Attracting new applications and capital is more likely to increase demand for fees and staking. So I support continuing to use BNB, but once the new chain launches, if it mainly takes on trading that already takes place on BSC, we shouldn’t count demand on both chains twice.
217
·
--
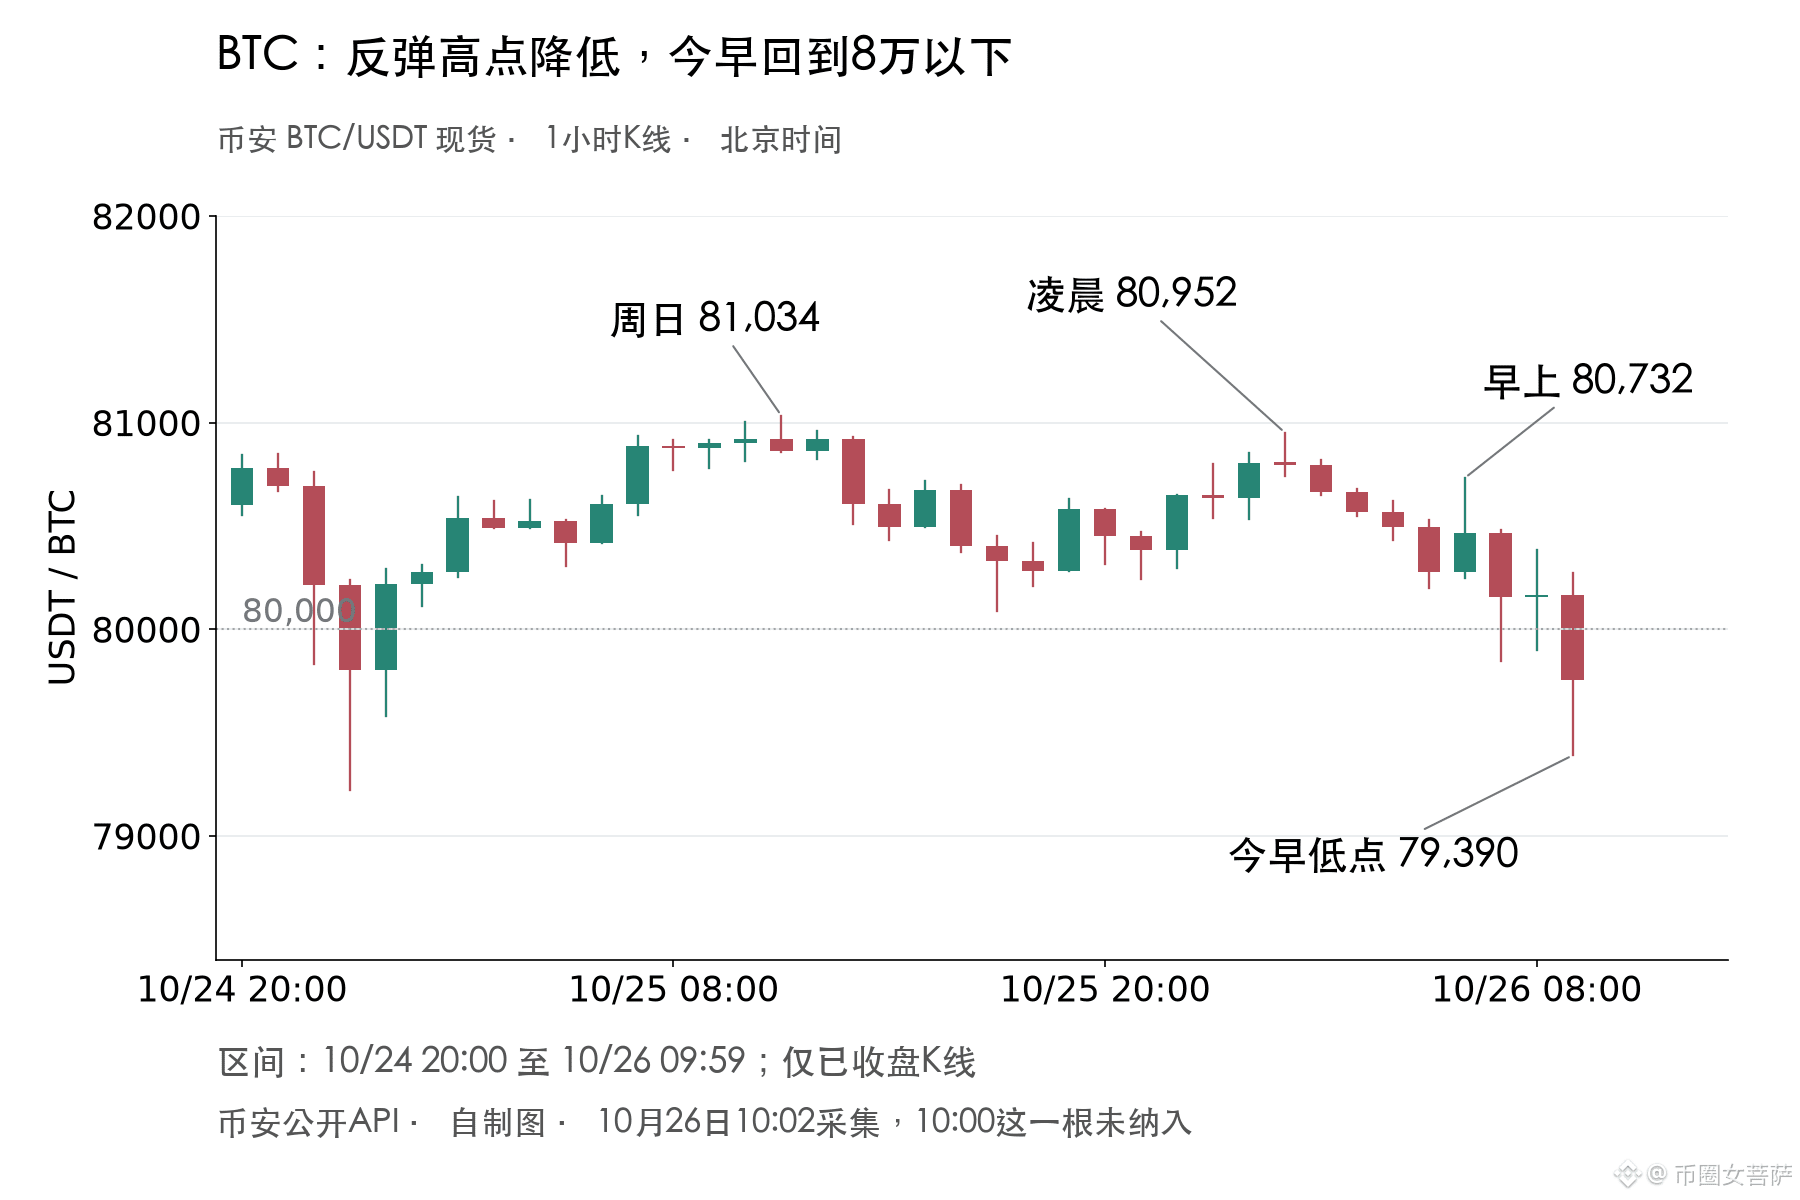
The Fed meets first this week, with U.S. GDP and PCE data released afterward. That timing is a bit tricky for $BTC . The decision is due at 2 a.m. Beijing time on Thursday, followed by a press conference at 2:30 a.m. GDP and PCE data won’t be released until 8:30 p.m. that evening. Even if prices rise first in the early hours, the evening data could prompt the market to reassess.
BTC’s rebound has also failed to hold. It returned to around 81,000 on Sunday, reached a high of 80,950 in the early hours today, and its morning rebound only got as far as 80,730 before it fell back to 79,390. It’s still below 80,000. I think the next day or two will remain weak, with rebounds likely to run into selling pressure. However, Saturday’s low hasn’t been breached, so it’s too soon to say that the decline is accelerating. If BTC can reclaim and hold around today’s early-hours rebound high of 80,950, this short-term view would need to be reconsidered.
If the press conference suggests there’s no rush to keep raising rates, BTC could rebound at first. But if tonight’s PCE data shows inflation accelerating again, concerns about interest rates that had just eased could return. With these two events only a little over a dozen hours apart, I think it’s too early to assume that the early-hours rally has fully priced in the bad news.
222
·
--
Western Digital spent about $1 billion on share buybacks this quarter, and on October 22 announced a 17% increase in its quarterly dividend. The buybacks were supported by operating cash flow, so I think it’s a good thing that money earned from selling hard drives is making its way back to shareholders.
It sold more storage capacity to cloud customers than in the same period last year, and the average selling price per unit of capacity rose by about 25%. Meanwhile, costs for its next-generation products are coming down, and the company’s overall adjusted gross margin has reached 58.1%. Customers are paying more while production costs are improving, so this wave of storage demand is already helping Western Digital earn more.
After capital expenditures, the company generated about $1.38 billion in free cash flow this quarter, enough to cover its buybacks and dividends paid during the period. It also repaid some convertible notes, however, and its cash balance actually fell from the previous quarter, so the entire $1.38 billion shouldn’t be treated as spare cash.
The company is targeting an adjusted gross margin of 60% to 61% next quarter. Price increases may not continue at this pace indefinitely, but if cost reductions for new products keep pace, the profits Western Digital earns from this demand cycle will be more sustainable—and its share price will have stronger earnings support.
77
·
--
South Korea was originally set to begin taxing crypto income next January, but a delay is now being discussed. Newsis quoted the presidential office today as saying that the matter is still under review and no decision has been made. If the tax is postponed, I think that would be good for South Korean investors who want to keep trading assets such as $BTC .
Under the National Tax Service’s current guidance, for coins already held before 2027, the tax basis can be whichever is higher: the actual purchase price or the market price at the end of 2026. If the year-end market price is higher, that price will be used as the basis when calculating taxable gains later, rather than carrying forward the lower cost basis from before the price increase. So it’s not possible to conclude, based solely on the fact that the tax is due to take effect next year, that South Korean holders will have to sell their coins en masse at the end of this year.
If the delay goes ahead, South Korean investors can put off taking on this tax burden, which would help them continue trading BTC. But continuing to trade is a far cry from putting new money into crypto, so I wouldn’t overestimate the impact of the delay news on coin prices.
With just over two months to go before the originally scheduled implementation, and the rules potentially changing, it’s quite a hassle for traders to plan around. If the tax is indeed postponed, it also needs to be made clear whether the provision using the market price at the end of 2026 as the tax basis will change as well.
1
526
·
--
On October 23, American Express announced that it would lay off about 3,500 employees alongside its earnings report. Layoffs can raise concerns about weakening consumer spending, but cardmember spending still grew 8% this quarter. Customers are still spending, while American Express is preparing to cut costs in its own operations. I think these layoffs need to be considered alongside the cost of cardmember benefits.
American Express’s net card fee revenue grew 16% in the third quarter, thanks both to higher fees on premium cards and to an increase in the number of customers with these cards. The premium card business remains attractive, but some of the additional annual fee revenue also has to go toward paying for cardmember benefits.
Companywide spending on cardmember services rose 36% this quarter. The company said this was mainly related to upgrades to the U.S. Platinum Card and customers using their benefits more. While we can’t use these two companywide figures to calculate Platinum Card profitability directly, the rapid growth in service costs still gives me some concern. As customers use more benefits, the company incurs higher costs, eating into some of the profit gains from annual fee increases.
The savings from layoffs have yet to show up in future results, so for now I wouldn’t translate the headcount reduction directly into additional profit. The company expects year-over-year growth in customer-related expenses to slow next quarter, partly because last year’s Platinum Card upgrade raised the comparison base. If card spending and fees continue to grow, slower expense growth could leave more room for profits—and give the stock an additional source of support from sustained earnings growth.
1
137
·
--
HOKA’s parent company, Deckers, lowered its sales target for this fiscal year. Management also acknowledged that updates to some product lines this year failed to resonate with consumers and wholesale partners, and said it plans to make improvements starting next spring. Slowing growth can no longer be blamed entirely on consumers’ reluctance to spend.
Promotions on athletic shoes are becoming more widespread in the U.S., but Deckers is sticking to full-price sales, putting pressure on its U.S. e-commerce business. I understand why it doesn’t want to trade discounts for sales volume, and even excluding the impact of tariff refunds, the company’s gross margin is indeed higher than last year. HOKA’s wholesale channel still grew 9% this quarter, showing that the brand remains in demand. Next, it needs to get product updates right so that direct-to-consumer sales can keep pace.
The earnings-per-share target for this fiscal year was raised by $0.45, but tariff refunds and related interest are expected to contribute about $0.52. Excluding that contribution, the new target is still slightly lower than before. For the stock to regain support from growth expectations, the company needs to sell more shoes. Deckers expects new HOKA products early next year to drive a pickup in growth, and that will be a more meaningful test than an earnings target that includes tariff refunds.
57
·
--
When finalizing its stablecoin rule, the U.S. banking regulator OCC removed a provision that would automatically extend the redemption period during heavy redemption pressure. The original draft said that if redemption requests within 24 hours exceeded 10% of the amount issued, the deadline would automatically extend to seven calendar days. The final rule keeps the requirement to report to regulators, but any extension must be decided by the regulator.
If holders know that many others are redeeming, they may have more reason to rush to get out first, knowing they could otherwise have to wait several more days. An arrangement that gives issuers time to manage their assets could trigger redemptions sooner and lead impatient holders to sell at a discount on exchanges. Removing the automatic extension may help ease this pressure, which is good for stablecoins’ ability to maintain their peg.
The rule was published on October 23, applies only to issuers under OCC jurisdiction, and takes effect on January 18, 2027. The usual redemption deadline remains two business days, counted from when a request is received and compliance requirements are met. Issuers must process the request and initiate payment; this does not guarantee that the funds have already arrived in the holder’s bank account.
70
·
--
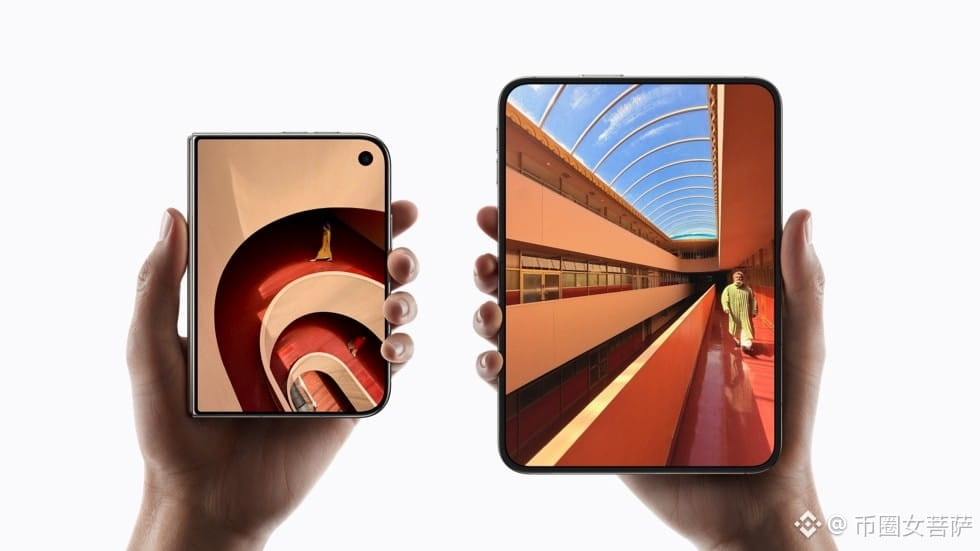
Yesterday, Apple brought its first foldable iPhone, the Duo, to stores, starting at $1,999. More than the launch-day queues, I’m interested in the monthly payment plan it has for U.S. customers: choose 24 months, and payments start at $57.99 a month, before tax. Apple has kept the price high while giving people eager to try it a way to avoid paying nearly $2,000 upfront.
The lease is offered by Klarna. At the end of the term, you can return the phone, upgrade to a new one, or pay extra to buy it outright. Paying the monthly installments doesn’t mean you own the phone. Apple hasn’t disclosed the Duo’s gross margin, and a higher price doesn’t necessarily mean it will make proportionally more money.
Still, if monthly payments persuade more people to switch from a regular iPhone to the Duo, Apple could boost iPhone revenue even if the total number of phones sold changes little.
182
·
--
Verified
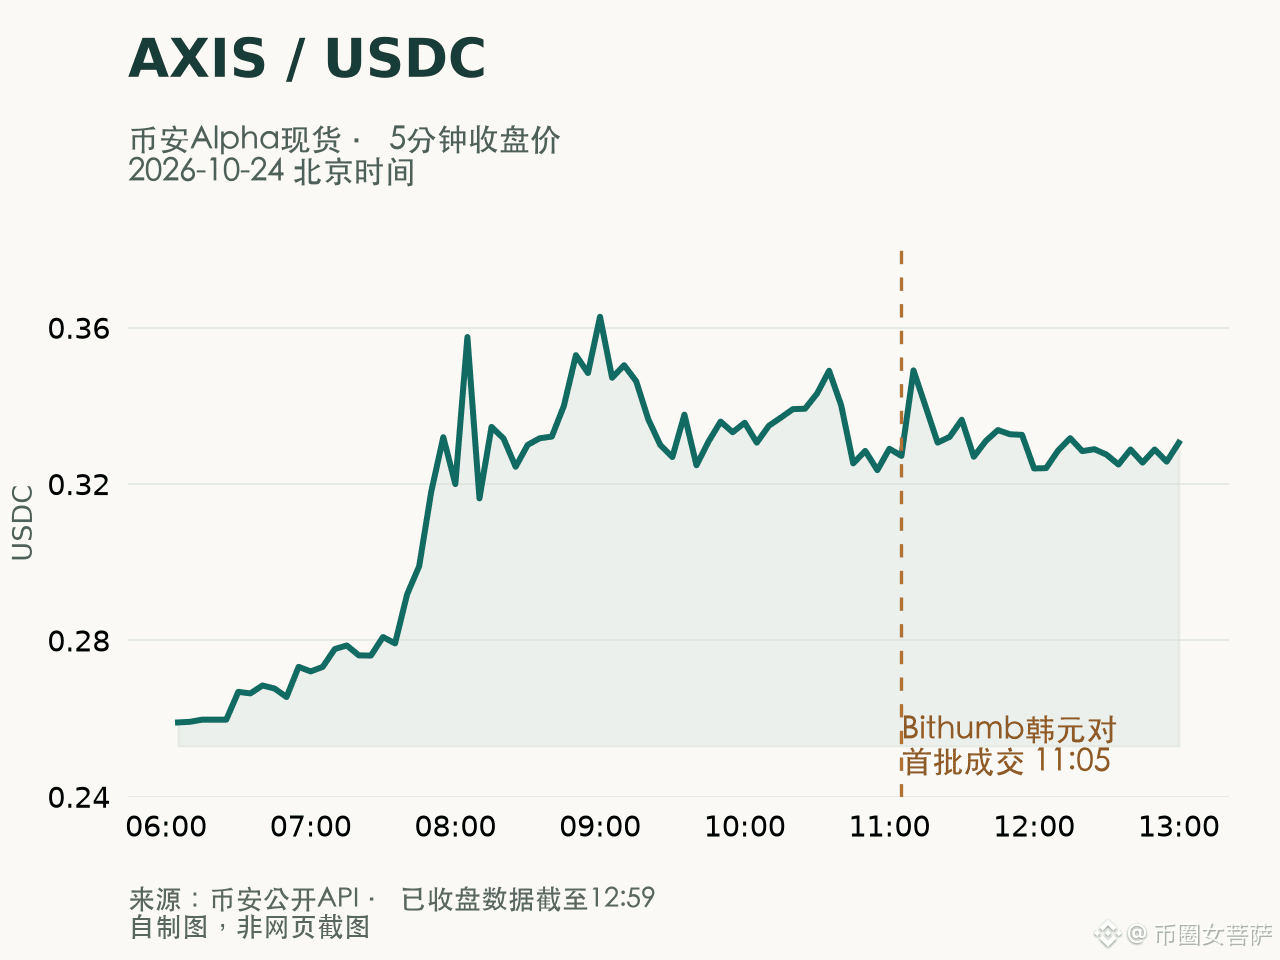
$AXIS Today, it gained another KRW spot market on Bithumb, and it can already be traded on Upbit as well. This new coin is expanding its trading channels pretty quickly, so over the next day or two, I’m more inclined to think its rebound can continue.
In the first two hours after trading began on Bithumb, AXIS/KRW recorded about 6 billion KRW in trading volume. However, the rally on Alpha had already started before Bithumb opened. It briefly surged to around 0.36 USDC this morning and has since pulled back to around 0.34. It has bounced back each time it returned to around 0.32 over the past few hours. If it falls below that level again, the rebound could easily give back more of its gains.
I haven’t found an AXIS trading pair or listing announcement for Binance Futures yet. The spot listings on two Korean exchanges and the perpetual futures market on MEXC are developments that make me more inclined to watch for a Binance Futures announcement, but they’re not enough to say a listing in the near term is likely.
284
·
--
Initia halted its mainnet and Rollup last night following a security incident, but $INIT rebounded from a sharp drop. Binance spot trading has it near $0.14 this morning. The rebound has some justification, but the project is still far from being out of danger.
Co-founder Zon’s preliminary assessment is that the attacker exploited a MoveVM vulnerability to mint additional tokens, but the vulnerability did not affect native INIT. That eases one concern for holders: an uncontrolled increase in supply. That’s good news. However, according to Bitquery’s on-chain tracking, the attacker has already taken about $2.73 million in assets through cross-chain transfers. Those cross-chain reserves are now short, and who will make up the shortfall—and how—will affect whether affected users are willing to put their assets back.
Kraken’s status page still shows INIT deposits and withdrawals as suspended, so over the next day or two, I expect the price to continue fluctuating in response to developments in the incident. The rebound will be more likely to hold if the network returns to normal and a concrete plan is put in place to handle the affected funds.
369
·
--
SpaceX wants to connect satellites and ground-based cell towers into a single mobile network. The latest news today is that it’s in talks to secure access to at least 80,000 U.S. cell towers, with Crown Castle among the companies it’s talking to.
This potential new customer couldn’t come at a better time for Crown Castle. The U.S. tower company has been hurt by DISH ending its leases, and rental revenue in the third quarter was still down 4.5% year over year. It could certainly use new tenants to make up the shortfall.
But 80,000 is SpaceX’s nationwide target; those towers won’t all belong to Crown Castle. Management has only confirmed that it’s in talks with various parties. It hasn’t disclosed how many towers might be leased or when the leases might begin.
If SpaceX leases Crown Castle’s towers, the additional rent and cash flow could help fill some of the gap, giving the stock another reason to rise. And Crown Castle wouldn’t have to compete for mobile subscribers: its revenue would increase as soon as the leases start generating payments.
75
·
--
Verified
Ethereum had originally planned to advance Glamsterdam on the Hoodi testnet on October 26, but paused the upgrade as the date approached. A new date hasn’t been set yet. $ETH ’s scaling progress will have to wait again, but this time, the reason developers hit the brakes really isn’t something they can afford to overlook.
The new rules will change how gas is charged, and some older contracts rely on the remaining gas to determine why an operation failed. Security researchers found that after the rules change, some operations that could previously be retried might be recorded as permanent failures. The contracts themselves won’t have changed a single line, yet their original safeguards could stop working. That does worry me.
So I think slowing down this time is necessary. Applications already running on mainnet also need to be able to handle the new rules. What’s been canceled is the testnet schedule; there was never a set mainnet launch date, so don’t take this to mean that mainnet has already run into problems.
We’ve recently lost a scaling milestone that was supposed to arrive as soon as next week, which weakens the case for ETH rising on upgrade news alone. But it won’t be enough to simply announce a new date later. They’ll also need to explain what will happen to affected older contracts and whether testing has passed after the fix.
5
2.5k
·
--
To keep raising money for its AI expansion, Meta is now changing its share structure too. The company plans to create a new class of non-voting Class C shares, initially distributing one share for every existing Class A and Class B share. It could then use them to raise funds, make acquisitions, and issue stock to employees.
This means that when the company issues Class C shares to raise money in the future, existing shareholders’ voting power won’t be diluted, making it easier for Zuckerberg to retain control. However, after the initial distribution, everyone’s ownership stake in the company will remain unchanged. If more Class C shares are issued later, each shareholder’s ownership stake will still be diluted—including Zuckerberg’s. The new charter is scheduled to take effect on January 19 next year, but the record and distribution dates for the shares have not yet been set.
Meta’s advertising revenue is still growing, but its free cash flow was already negative $2.12 billion in the third quarter. Although the company still has a large amount of cash and securities on its books, it is preparing more ways to fund future AI investments.
I can understand why Meta would want to rely less on its cash reserves to fund expansion. But for the stock price to benefit too, future investments will need to increase earnings per share. If the number of shares grows faster than profits, earnings per share will actually fall—so easier access to financing may not necessarily be good news for ordinary shareholders.
77
·
--
NeoSoul announced last night that it would integrate with predict.fun via API, letting AI research prediction markets on users’ behalf and place orders with their authorization. I think $DNA choosing this as a starting point makes sense: events have settlement outcomes, so if the bot gets something wrong, you can look back and investigate why.
NeoTrade is its desktop AI trading tool. The markets currently listed in its documentation include predict.fun and Polymarket. The team also intends DNA to be used for payments, skills, and data access. If users keep spending DNA on these services, that could provide stronger long-term support for the token’s price. Unfortunately, there’s no data yet on paid usage resulting from this integration, so it’s too early to estimate how much it might increase demand for DNA.
DNA is already available for spot trading on Bitget and KuCoin, and for perpetuals on OKX. However, I couldn’t find any DNA trading pairs on Upbit or Bithumb, or an announcement that it had been listed for futures trading on Binance. Active trading in its perpetuals on other exchanges and in Alpha gives exchanges a reason to keep an eye on it, but isn’t enough to conclude that it will be listed for Binance futures anytime soon.
The first DNA trading competition also ends on October 27 at 9 p.m. Beijing time. After signing up, participants are ranked among the top 2,000 based on eligible buy volume, with 255 DNA per person. This afternoon, DNA/USDT on Alpha was trading at around 0.216, putting the reward’s estimated value at about 55 USDT. Rewards will be distributed after the competition, so their value at the time of receipt will depend on the token’s price then.
378
·
--
These more than 60,000 coins, $BTC , have once again been trending, but the Tianjin court accepted the forfeiture application on September 28, and the notice was issued on October 13. English-language media reported on it again yesterday, still focusing on the acceptance of the application.
These coins had already been seized by UK law enforcement. What the UK court first clarified on October 12 was that whether the victims have property rights to these assets must be determined under Chinese law. How the assets will ultimately be divided remains unresolved, and the ruling did not order the coins to be sold.
So based on this news alone, I think the short-term bearish impact on BTC has been overstated. If specific plans for liquidating the assets are announced later, we can then see how much will be sold and how. Counting all 60,000-plus coins as immediate selling pressure at this point seems premature.
The money lost to the scam was later turned into Bitcoin. After all these years of gains, the victims still have to fight over how much they can get back. It leaves me feeling a little uneasy, and I hope the recovery process reaches a resolution soon.
165
·
--
Nvidia (NASDAQ: NVDA) is even paying upfront to lock in testing capacity ahead of time so it can deliver more AI chips. On October 21, it announced an arrangement to provide King Yuan Electronics with an $1.1 billion capacity prepayment to support a new U.S. testing facility, which is targeted to begin mass production in April 2027.
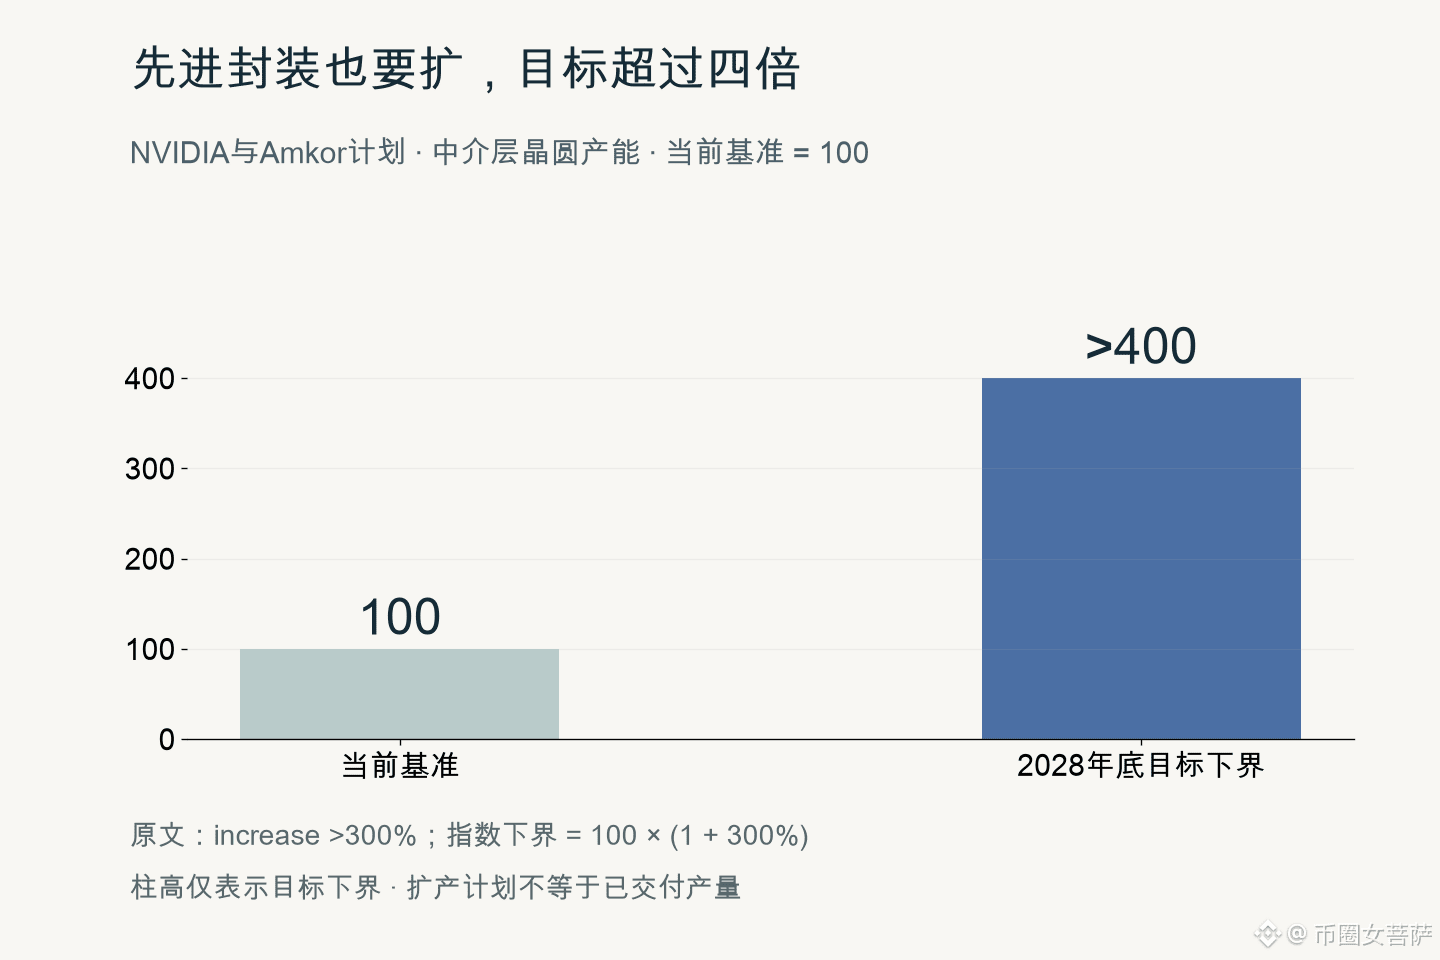
And King Yuan Electronics isn’t the only supplier involved in this expansion. Samsung Electro-Mechanics has joined its substrate supply chain, and Amkor is also preparing to increase its advanced packaging capacity. Once an order comes in, all these stages have to be in place before chips can become products customers can actually use.
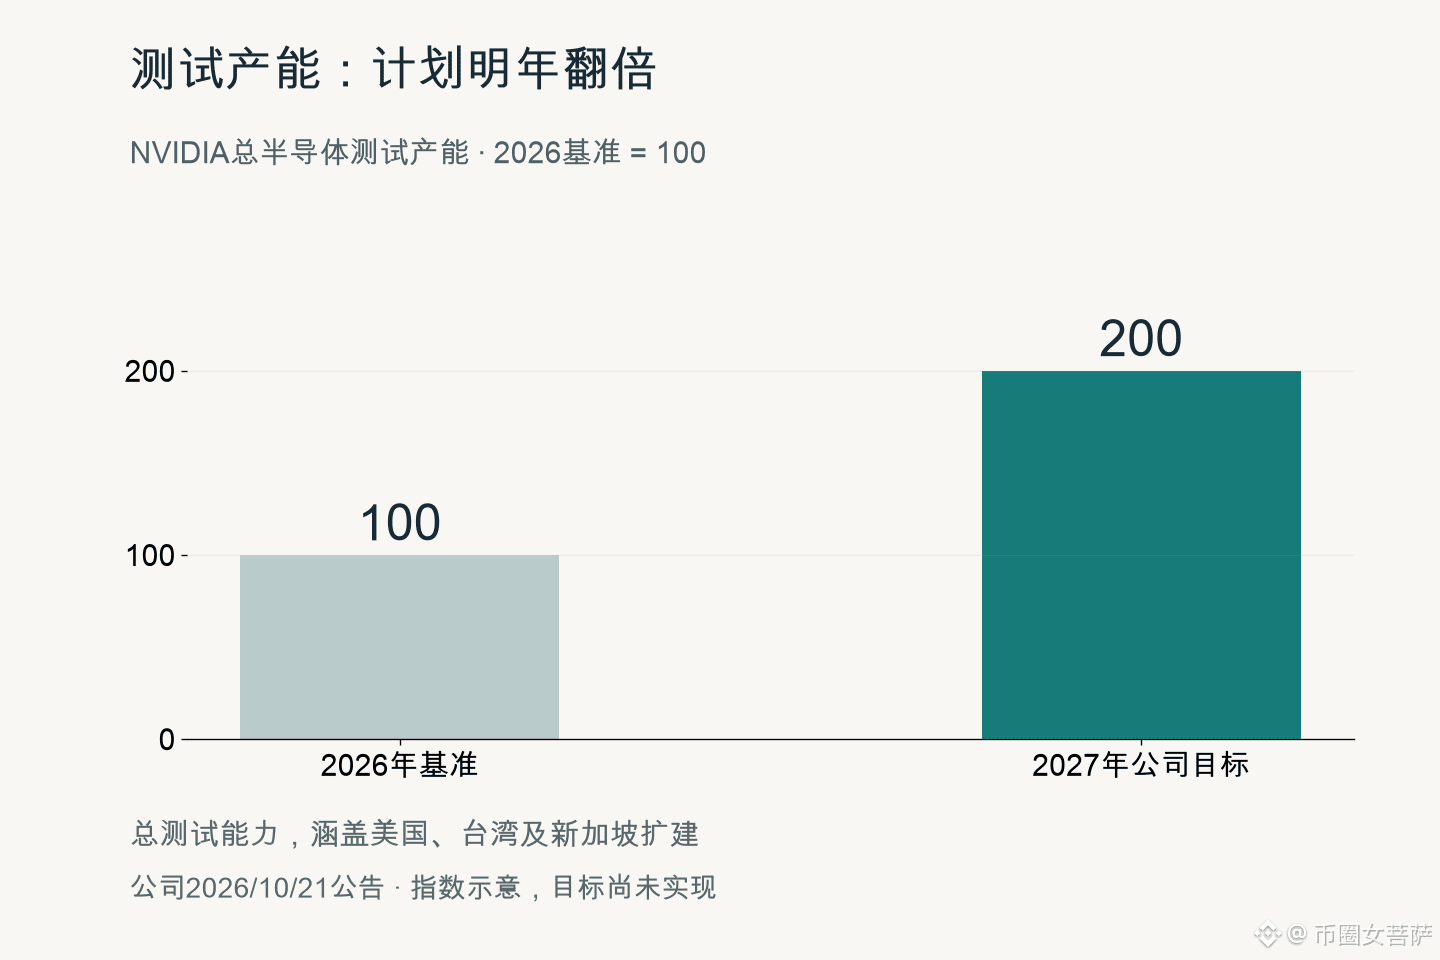
The company expects its total testing capacity in 2027 to be double what it was in 2026. This arrangement gives me more confidence in NVDA’s deliveries over the next few quarters. If capacity comes online as planned, it should reduce the risk of having orders but being unable to ship, and make it easier to turn demand into revenue, supporting the stock price.
That said, the new King Yuan facility is targeted to begin mass production next year, so it shouldn’t be counted as additional output this quarter. The prepayment will also tie up cash upfront, and if customer demand slows, locking in capacity ahead of time won’t be so straightforward.
What matters more to me is that this expansion advances substrates, packaging, and testing all at once. If only one stage is addressed while the others remain bottlenecks, Nvidia still won’t be able to deliver. For a company like Nvidia that makes money from complete AI systems, this kind of supply-chain preparation matters more than simply announcing a new partnership.
93
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number