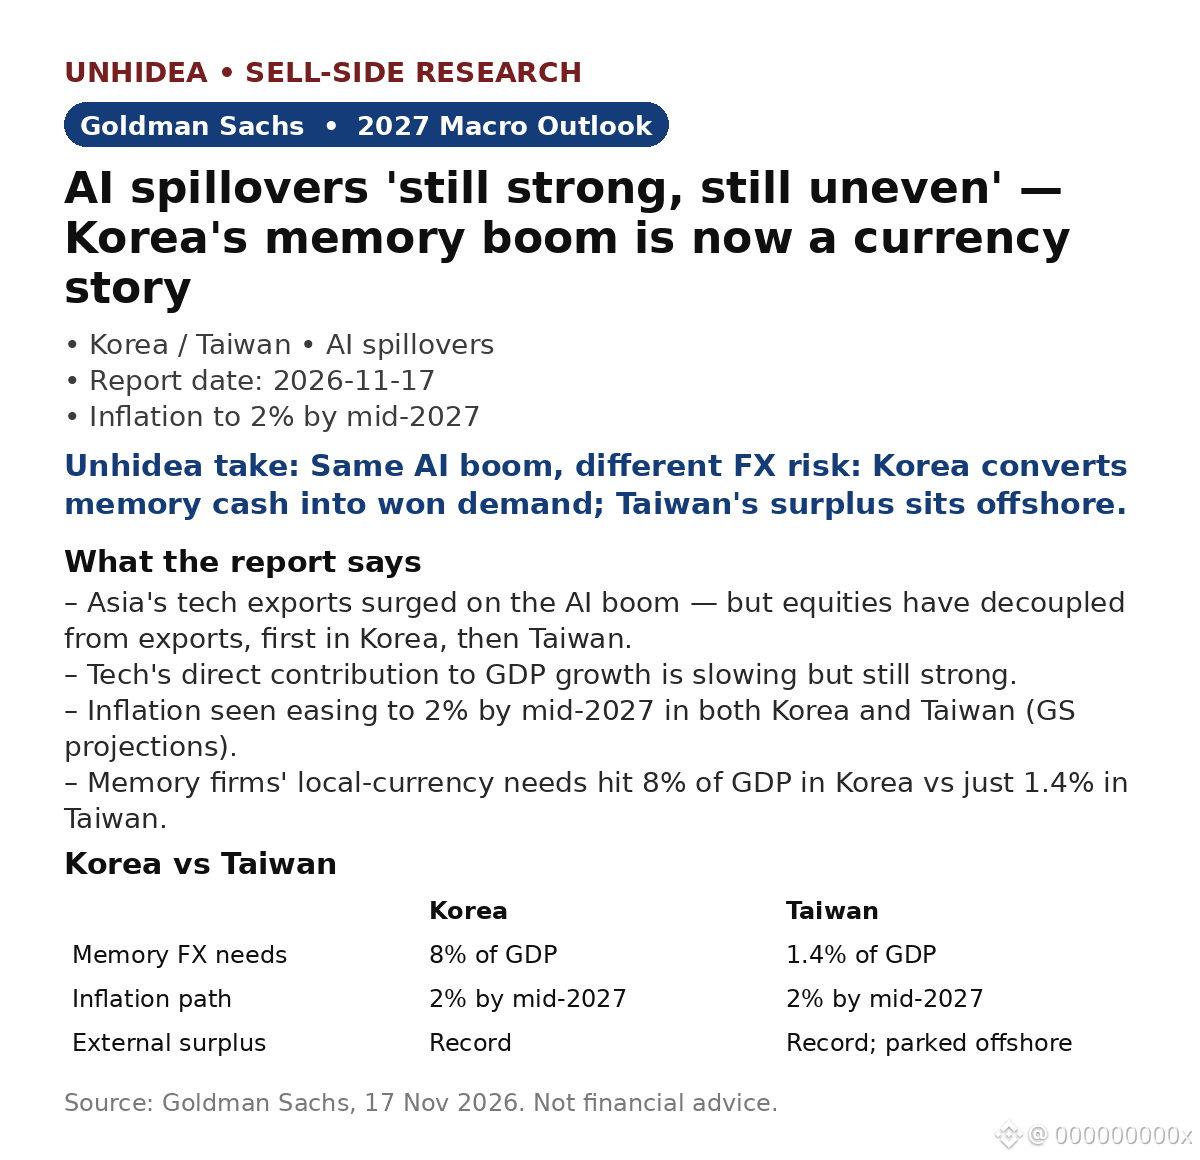
AI spillovers "still strong, still uneven": Goldman Sachs' 2027 Korea/Taiwan outlook — Samsung's memory windfall is now a currency story
- Asia's tech exports surged on the AI boom, but equities have decoupled from exports — first in Korea, then Taiwan. The index is no longer a clean read on the export cycle.
- Tech's direct contribution to GDP growth is slowing but still strong. Inflation is seen easing to 2% by mid-2027 in both Korea and Taiwan (GS projections).
- Memory companies' local-currency needs reach 8% of GDP in Korea vs just 1.4% in Taiwan. Korea converts the boom into won demand; Taiwan's record surplus is parked offshore.
- Post-report market news: Nvidia's FQ3 revenue was $115.84bn, +103% YoY vs ~$109bn expected, guiding ~$130bn vs ~$125bn expected — and Samsung and SK Hynix rallied in Korea after the print.
Unhidea take: the decoupling is the signal — Korea/Taiwan equities now trade the AI narrative and memory pricing, not export volumes. A soft export print no longer means a soft index, and vice versa.
Unhidea take: the 8% vs 1.4% gap is the real trade. Korea's won faces structural demand from memory cash conversion while Taiwan's surplus sits offshore — same AI boom, opposite FX pressure. Watch KRW, not just KOSPI.
Risks: AI capex cuts, memory price reversal, FX volatility, US-China export controls.
Source: Goldman Sachs, 17 Nov 2026. Not financial advice.
- Asia's tech exports surged on the AI boom, but equities have decoupled from exports — first in Korea, then Taiwan. The index is no longer a clean read on the export cycle.
- Tech's direct contribution to GDP growth is slowing but still strong. Inflation is seen easing to 2% by mid-2027 in both Korea and Taiwan (GS projections).
- Memory companies' local-currency needs reach 8% of GDP in Korea vs just 1.4% in Taiwan. Korea converts the boom into won demand; Taiwan's record surplus is parked offshore.
- Post-report market news: Nvidia's FQ3 revenue was $115.84bn, +103% YoY vs ~$109bn expected, guiding ~$130bn vs ~$125bn expected — and Samsung and SK Hynix rallied in Korea after the print.
Unhidea take: the decoupling is the signal — Korea/Taiwan equities now trade the AI narrative and memory pricing, not export volumes. A soft export print no longer means a soft index, and vice versa.
Unhidea take: the 8% vs 1.4% gap is the real trade. Korea's won faces structural demand from memory cash conversion while Taiwan's surplus sits offshore — same AI boom, opposite FX pressure. Watch KRW, not just KOSPI.
Risks: AI capex cuts, memory price reversal, FX volatility, US-China export controls.
Source: Goldman Sachs, 17 Nov 2026. Not financial advice.