
""Strong growth data can push bond yields higher because both demand and inflation may remain firm. But if inflation is soft alongside growth, the market reaction may be more balanced.""
I didn't understand this point. What does it mean? Explain it again—how does this work, and what role does it play?
Let's understand it again through a role-play. Absolutely—let's understand it with a role-play.
Imagine the economy is a marketplace, and the bond market looks at that marketplace to decide what return it wants in exchange for lending money to the government—that return is called the yield.
Scenario 1: Growth is strong and inflation is also heating up
The data comes in:
factories are producing more,
people are buying more,
jobs and salaries are improving.
Economy: “Demand is strong. People are spending.”
Businesses: “We have lots of customers, so we can raise prices.”
Inflation: “There is a risk that prices will rise quickly.”
Central bank: “We may need to keep interest rates high or raise them to keep inflation under control.”
Bond investor: “If interest rates stay high in the future, older bonds with low interest rates will become less attractive. I want a higher return to buy a new bond.”
Result: Bond sellers may have to accept a lower price to attract buyers.
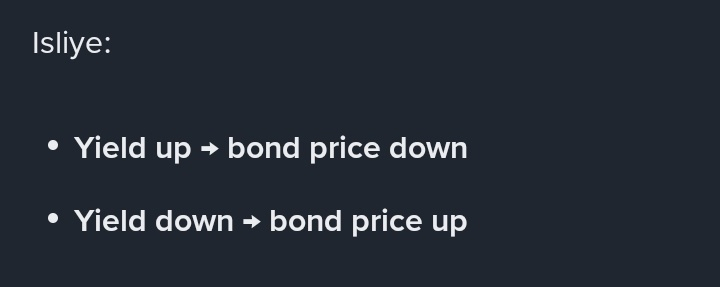
Bond price down → yield up.
In other words, when strong growth also pushes up inflation, the market thinks rates may stay high for longer. That's why yields may start to rise.
Scenario 2: Growth is strong, but inflation is soft
Now imagine that growth is still strong—jobs, output, and spending are all doing well—but prices are not rising rapidly.
Economy: “Growth is going well.”
Inflation: “I'm under control; prices aren't rising too quickly.”
Central bank: “Growth is good, but inflation is calm. We may not need to raise rates further.”
Bond investor: “Growth is certainly strong, but the risk of rate hikes or a prolonged period of very high rates is not as clear.”
Result:
Yields may rise slightly because the economy is strong and borrowing demand may be high;
or they may remain stable because the threat of inflation and tighter policy is low;
they may even fall if the market believes growth is sustainable and future inflation will remain under control.
That is why this reaction was called balanced: on one hand, growth is a positive signal, but on the other, soft inflation may keep the central bank from taking aggressive action.
A simple analogy: a car and its accelerator
Growth = the car's speed
Inflation = the engine's temperature
Central bank rates = the brakes
If a car is moving fast and the engine is overheating, the driver may brake harder.
Here: strong growth + high inflation → risk of rate hikes/high rates → yields rise.
If a car is moving fast but the engine temperature is normal, the driver does not need to brake hard.
Here: strong growth + soft inflation → lower risk of rate hikes → a limited or mixed response from yields.
The connection between bond prices and yields
A simple example:
An old bond costs ₹100 and pays ₹5 in interest every year.
Its yield is roughly 5%.
If the market expects interest rates to be higher in the future, a bond paying ₹5 in interest will not seem as attractive. Its price might fall to, say, ₹95.
Now that same ₹5 in interest is paid on a price of ₹95—the buyer's effective return goes up.
That's why the price fell and the yield rose.
The opposite is also true: when there is strong demand for bonds, their prices rise and yields fall.
A shortcut to remember
Strong growth + sticky/high inflation → concern about higher policy rates → upward pressure on yields.
Strong growth + soft inflation → less concern about policy tightening → a milder or mixed move in yields.
Weak growth + soft inflation → expectations of rate cuts/safe-haven demand → downward pressure on yields.
This is not a fixed rule, because government borrowing, RBI liquidity, crude oil, US Treasury yields, and foreign investment flows also influence yields at the same time.