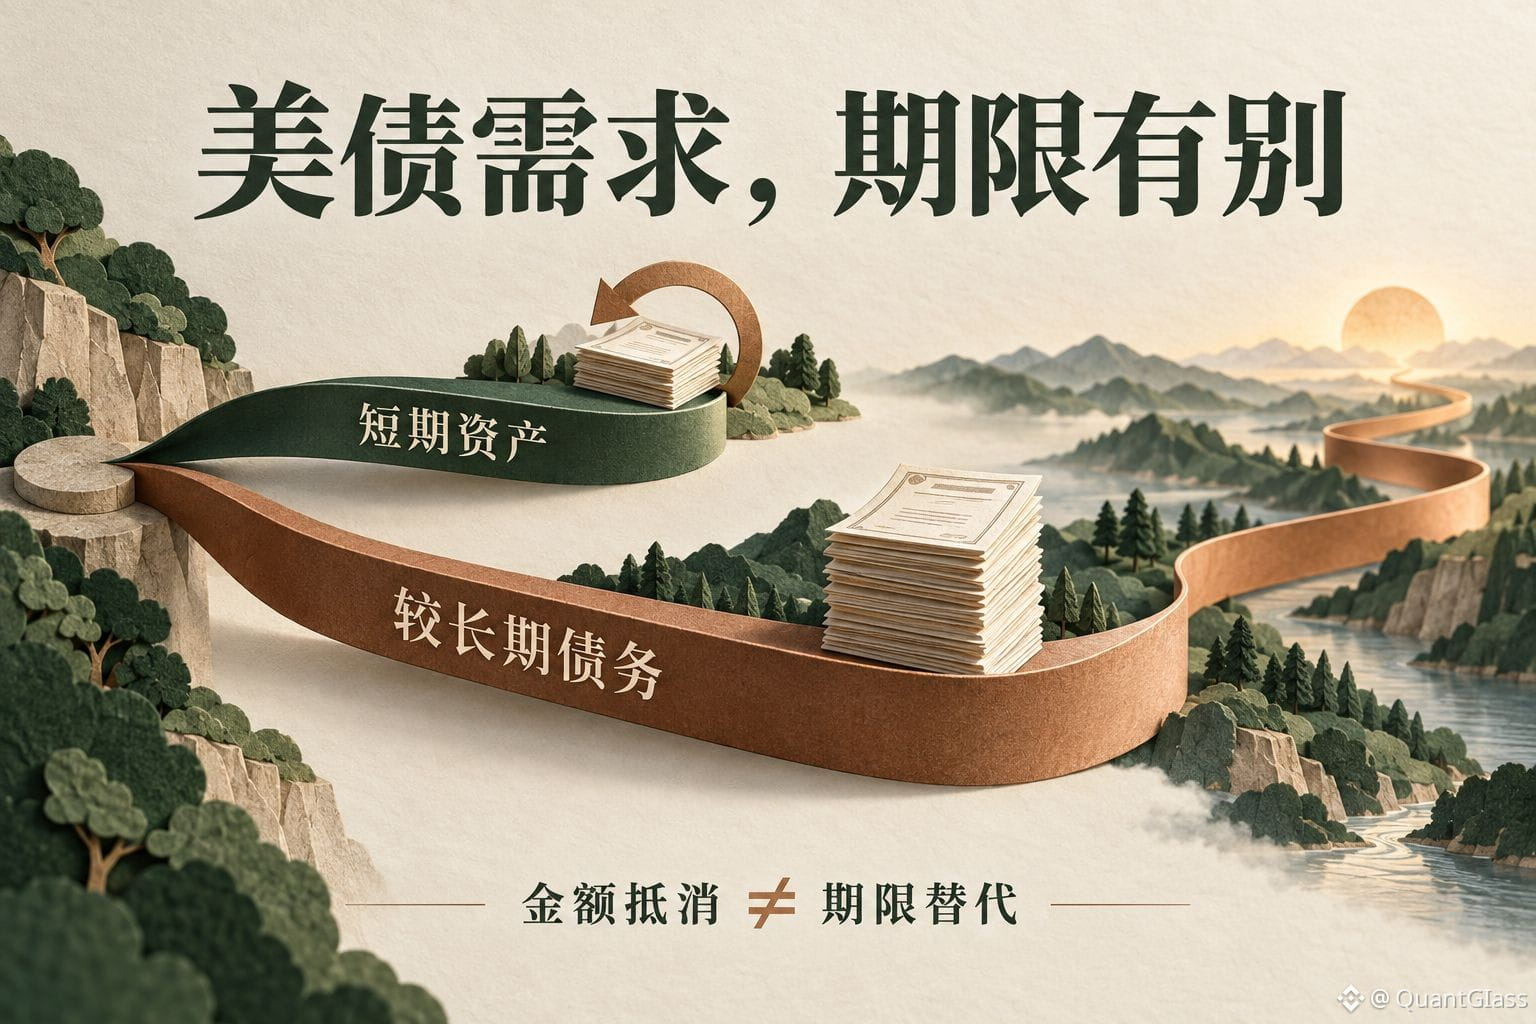
Invest stablecoins to buy US Treasuries—first, look at which maturity range they buy.
A San Francisco Fed research estimate dated September 28: Over the past five years, Tether and Circle-related US Treasury holdings increased by about $200 billion, equivalent to more than 40% of the decline in China’s US Treasury holdings over the same period. But the chart’s definition includes Treasury bills and repurchase agreements, so it can’t all be attributed to direct purchases of government bonds.
More importantly, there are maturity differences: China’s reductions have mainly been in longer-dated debt, while stablecoin issuers have mainly added short-term assets to meet users’ demand to redeem at par value. Offsetting effects in amounts do not mean there is a direct fill-in for the same maturity segment’s buying.
My view: When analyzing this kind of news, you need to consider maturity, the instruments held, and the source of funds. Even if people who previously held US Treasuries switch to indirect exposure via stablecoins, the increase on issuers’ balance sheets may not necessarily represent entirely new demand.
The article’s statement of “about $400 billion by the end of 2030” is a projection that continues recent trends and carries substantial uncertainty; it is not an already-confirmed purchase plan.
Source: San Francisco Fed Economic Letter, September 28, 2026.
#Stablecoins