

Bitcoin is again in a very unusual spot.
As of September 23, 2026, BTC is trading at approximately:
$85 000–86 000
and recently reached a local high of about:
$87 359.
In September, Bitcoin had already risen by about 8.8%, after nearly 25% growth in August.
Meanwhile, only a week ago the market received two formally negative news items at once:
The U.S. Senate couldn’t advance the CLARITY Act;
The Federal Reserve raised the rate to 3.75–4.00%.
And Bitcoin didn’t just avoid crashing — it rose to the highest level roughly over eight months.
Does this mean the start of a new big bull run?
To answer that, it’s not enough to look at just the last few weeks.
You need to look at:
the entire monthly history of Bitcoin.
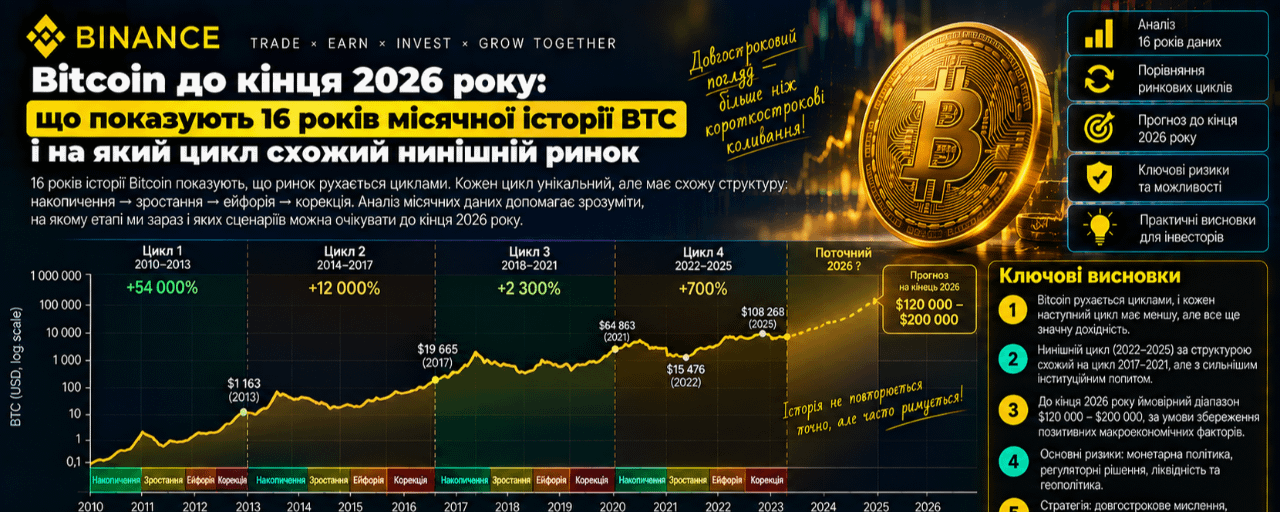
What all monthly BTC quotes since 2010 show
The full exchange-traded history of Bitcoin begins around the summer of 2010.
And the first thing you immediately see:
Bitcoin almost never moves uniformly.
Its history consists of short periods of extraordinarily strong growth, alternating with long consolidation phases or deep drops.
The strongest month across all available history remains:
November 2013: approximately +454%.
In 2013, BTC grew by more than 5,000%.
But already in December 2013, Bitcoin lost approximately:
33–35%.
So even the strongest bull market in history ended with a sharp reversal.
Cycle #1: 2012–2014
The first halving of Bitcoin happened:
November 28, 2012.
Block reward decreased from 50 to 25 BTC.
In 2013, after the halving, it turned explosive.
Especially:
March:
≈ +181%
October:
≈ +61%
November:
≈ +451%.
But already in December, Bitcoin fell by about 35%.
One of the reasons for the reversal was a regulatory attack in China.
In December 2013, Chinese financial institutions received a ban on working with Bitcoin, and BTC China was forced to stop accepting yuan deposits.
The price then was falling by about 40% over a very short period.
Main lesson:
when the market already has a huge profit, even a single regulatory headline can trigger mass profit-taking.
2014: the first true post-peak year
In 2014, the year ended at approximately:
-58%.
Especially interesting is the fourth quarter specifically:
October:
≈ -13%
November:
≈ +12%
December:
≈ -15%.
So even short, strong bounces didn’t change the main bearish regime.
This will become important when we return to 2026.
Cycle #2: 2016–2018
Second halving:
July 9, 2016.
Reward:
12.5 BTC.
2016 was a year of accumulation.
Especially strong was the end of the year:
October:
+15%
November:
+6%
December:
+31%.
Then came 2017.
2017: the classic bull market
Over 2017, Bitcoin grew by approximately:
+1,369%.
Especially strong were:
May:
≈ +66–70%
August:
≈ +64–66%
October:
≈ +48%
November:
≈ +56%
December:
≈ +39%.
At first glance it seems:
December was +39%, meaning the bull market was still going.
But that’s exactly where there’s an important trap on the monthly chart.
Bitcoin formed an all-time high roughly in mid-December, after which it started falling.
So:
A green monthly candle can contain the cycle top inside it.
By the end of 2017, regulated Bitcoin futures on Cboe and CME also started trading.
2018: repeating 2014
The next post-peak year:
-73%.
And again, the worst happened toward the end of the year.
October:
≈ -4.5%
November:
≈ -37%
December:
≈ -7%.
This is one of the most important historical patterns of Bitcoin:
after a big cyclical peak, the fourth quarter is not necessarily strong, even if historically Q4 is considered bullish.
2019: recovery, but not a new bull market
In 2019, it delivered approximately:
+92%.
Bitcoin rose strongly in the spring:
April:
+29%
May:
+62%
June:
+27%.
But then:
September:
-14%
November:
-17%
December:
-5%.
This is another important lesson:
a strong annual recovery doesn’t guarantee a strong finish to the year.
Cycle #3: 2020–2022
Third halving:
May 11, 2020.
Reward:
6.25 BTC.
And that’s exactly where we got, probably, the cleanest example of the impact of global liquidity.
2020: an ideal environment for Bitcoin
After the COVID crisis, rates fell to nearly zero.
Central banks flooded the financial system with liquidity.
Fiscal stimulus was huge.
And Bitcoin finished 2020 like this:
October:
+28%
November:
+42%
December:
+48%.
This is one of the strongest Q4s in BTC history.
The main reason wasn’t only the halving.
There was a combination of:
a reduction in new supply + an excess of global liquidity.
This is critically important for comparing with 2026.
2021: institutionals come into Bitcoin
In 2021, Bitcoin received a huge mainstream adoption wave.
Tesla bought Bitcoin for $1.5 billion.
Mastercard, banks, and institutional investors started entering the sector more actively.
Back then, Reuters described the rally as the result of a combination of:
institutional capital;
corporate adoption;
of low rates;
large-scale stimulus.
Bitcoin formed the second big peak of the year in November 2021.
And the monthly structure looked like this:
October:
+40%
November:
-7%
December:
-19%.
And again:
a seasonally strong Q4 didn’t save the market after the formation of a top.
2022: macroeconomics beat the halving cycle
Over 2022, BTC lost approximately:
64%.
This year is very important for the current forecast.
Reasons:
an aggressive rise in Fed rates;
a more expensive dollar;
disappearance of cheap liquidity;
the collapse of Terra/LUNA;
Celsius;
FTX.
Reuters described 2022 as the moment when Bitcoin lost its previous “cocktail of cheap money and leverage.”
During the Terra crash, Bitcoin fell to the lows for 16 months amid a simultaneous crypto shock and fear of the Fed’s aggressive tightening.
Q4:
October:
+5%
November:
-16%
December:
-4%.
Cycle #4: 2024–2026
The fourth halving has occurred:
April 20, 2024.
Reward has decreased to:
3.125 BTC.
But this cycle has a fundamentally new element:
spot Bitcoin ETF.
2024 changed Bitcoin’s structure
In January 2024, spot Bitcoin ETFs were launched in the U.S.
Already in March, BTC set a new historical high again:
leading up to the halving.
This hadn’t happened before.
Reuters directly linked the rally to large ETF capital flows and expectations for future supply reduction.
The year 2024 ended at approximately:
+121%.
And in December, BTC first exceeded:
$100,000.
2025: the old cycle is starting to break
And this is where the situation became unusual.
In the classic four-year model, 2025 was supposed to be an analog of:
2013;
2017;
2021.
So the main bull year.
Bitcoin truly set an ATH:
above $126,000
in October 2025.
But the whole year ended at approximately:
-6%.
So for the first time after the halving, we didn’t get the classic vertical cycle ending.
The reasons were very telling.
Bitcoin has become much more correlated with:
Nasdaq;
global rates;
tariffs;
AI stocks;
liquidity conditions.
Reuters noted that during 2025, BTC has increasingly moved alongside traditional risk assets.
October 2025 is especially important
Bitcoin set an ATH above $126,000.
A few days later, a sharp correction began after a new escalation of the U.S.–China trade conflict.
More than was liquidated:
$19 billion leveraged positions.
Bitcoin fell roughly to:
$104,783.
And for the first time since 2018, October ended negative.
This is an important reminder:
even “Uptober” stops working if the macro shock is strong enough.
And now we’re coming to 2026
The monthly structure of 2026 is very interesting.
Approximately:
January:
-10%
February:
-15%
March:
+2%
April:
+12%
May:
-4%
June:
-20%
July:
+7%
August:
+25%
September:
approximately +9% at the moment.
This is not a classic bull market.
But this is also no longer a classic bear market.
That is:
a market of big waves inside a broader recovery structure.
The most interesting historical coincidence
If you look only at the four-year cycle, 2026 should correspond to:
2014
2018
2022.
That is, the second year after the halving.
And all three prior analogs were very bad.
2014:
≈ -58%
2018:
≈ -73%
2022:
≈ -64%.
And their Q4 was weak too.
Cumulatively:
Q4 2014:
≈ -17%
Q4 2018:
≈ -44%
Q4 2022:
≈ -15%.
So the pure cyclic model says:
cautiously.
But 2026 has one huge difference
In 2014, there was no spot ETF.
In 2018, there was no spot ETF.
In 2022, there was no spot ETF.
And now only the U.S. spot Bitcoin ETFs have a combined net inflow of approximately:
$56.6 billion
over the entire lifespan of the products.
And literally right after the September FOMC:
September 17:
+$159.5 million
September 18:
+ $433 million
September 21:
+$999 million
September 22:
+$364 million.
In a few sessions, the institutional channel absorbed more than:
$1.5 billion.
That buyer didn’t exist in the previous after-cycle bear markets.
So a simple model like “2014 = 2018 = 2022 = 2026” no longer works
But you also can’t ignore it.
More precisely:
Bitcoin is in a historically weak phase of the four-year cycle, but for the first time it enters it with a steady institutional demand channel.
This is an absolutely new regime.
What shows the seasonality of October, November, and December
If you take the entire history from 2011 to 2025, Q4 looks very strong.
According to Charles Schwab/Bloomberg:
mid October:
+15%
mid November:
+35.5%
mid-December:
+7.2%.
But the average is heavily distorted by early explosive cycles.
The median is much more realistic:
October:
+11.5%
November:
+8.9%
December:
-3.2%.
So historically:
October and November were indeed strong.
And December is not as clear-cut as people often think.
Most importantly: cycle conditions matter more than seasonality
If Bitcoin is in an expansion regime:
Q4 is often very strong.
For example:
2017
October +48%
November +56%
December +39%
2020
October +28%
November +42%
December +48%.
But if the cycle peak is already behind us:
2018
November -37%
2021
December -19%
2022
November -16%
2025
November around -17%.
So:
“Uptober” — not a strategy.
First you need to determine the market regime.
Which historical period is fall 2026 most similar to?
Not 2017.
Back then it was a vertical speculative mania.
Not 2020.
Back then, central banks were creating huge liquidity and rates were nearly zero.
And not completely 2022.
Back then, the Fed was aggressively accelerating tightening, and the crypto ecosystem was breaking from the inside.
In my opinion, the current structure most resembles:
a mix of 2019 + 2023 + partly 2024.
Why?
There is:
recovery after a major correction;
strong institutional demand;
positive regulatory developments;
yet at the same time, a tight macro environment.
So the fundamentals of the crypto industry are improving faster than global monetary liquidity.
What currently works in Bitcoin’s favor
1. ETF flows
This is the strongest argument.
On September 21, spot BTC ETFs received approximately:
$999 million
net inflow in a single session.
This is a huge buyer.
2. Bitcoin withstood bad news
The CLARITY Act did not pass a procedural vote.
The Senate voted 49–50, while cloture required 60 votes.
Two days later, the Fed:
raised the rate.
And still BTC went up.
This is a typical signal:
bad news stops working.
3. Regulatory policy still moves forward
The failure of the CLARITY Act did not stop the SEC.
On September 17, the SEC introduced a temporary five-year “Innovation Exemption” for certain tokenized stock infrastructure.
This shows that regulatory normalization of crypto/on-chain markets continues even without a major law from Congress.
4. Nasdaq again at an all-time high
On September 22, Nasdaq set a new intraday record.
At the same time, the yield on the 10-year Treasury dropped below 5%, and oil started getting cheaper.
In 2025–2026, Bitcoin became significantly more correlated with technology risk assets.
So a strong Nasdaq now is:
bullish for BTC.
But there is a very serious macro risk
In September, the Fed raised the rate to:
3.75–4.00%.
And the median FOMC forecast shows:
4.1% by the end of 2026.
So another rate increase effectively remains the Fed’s base scenario.
Next FOMCs:
October 27–28
and
December 8–9.
Those are what can define BTC’s final trajectory in 2026.
The biggest risk is inflation
Fed sees PCE inflation in 2026 around:
3.7%
and Core PCE:
3.4%.
This is far from the 2% target.
If the next CPIs are hot again, the market may start pricing in not one, but several additional hikes.
Next key CPIs:
October 14
November 10
December 10.
Levels that currently define BTC’s structure
Current price:
around $85,000–86,000.
First resistance zone:
$87,000–90,000.
$90,000 is especially important right now as a psychological and technical level.
Next:
$95,000
and:
$100,000.
Why $100,000 is so important
This isn’t just a round number.
A return of BTC above $100,000 would mean:
full recovery after the summer correction;
a return of a large share of momentum traders;
a narrative shift from recovery to expansion;
a sharp reduction in the psychological impact of the ATH in 2025.
After that, the market would start looking at:
$110,000–115,000
and only then:
$125,000–126,000 ATH.
supports
Closest:
$82,000–83,000.
Next:
$79,000–80,000.
And now $80,000 is becoming the most important pivot.
Below:
$75,000–76,000.
And then:
$70,000–72,000.
Bitcoin forecast for the end of 2026
I see three main scenarios.
🟡 Base scenario — 50%
ETF flows remain positive, but the Fed is doing another rate hike.
Inflation slowly decreases.
The 10-year Treasury is trading around 4.7–5.1%.
Bitcoin doesn’t return to the ATH, but it consolidates above $80,000.
In October–November, a test is possible:
$90,000–95,000.
In favorable moments:
$100,000.
But above $100K, sellers become more active.
Base range until the end of the year:
$80,000–100,000
The most likely zone is December 31:
$90,000–97,000.
🟢 Bullish scenario — 30%
For this to happen, several conditions must coincide at the same time:
ETF flows continue bringing in hundreds of millions of dollars;
CPI starts to slow down;
After one additional hike, the Fed signals a pause;
Treasury yield is going below 4.7%;
Nasdaq continues setting new highs;
geopolitical tensions and oil prices are falling.
Then the breakout:
$90,000
can quickly lead to:
$100,000.
Next:
$105,000–110,000.
With a very strong Q4:
$115,000–120,000.
And a test of the all-time high is coming:
$125,000–126,000
it becomes possible, but I don’t make it the base target.
Bullish year-end zone:
$105,000–120,000.
🔴 Bearish scenario — 20%
Main triggers:
a new acceleration in CPI;
oil rises sharply again;
the Fed signals a series of additional hikes;
the Treasury yield holds above 5.1–5.2%;
ETF flows shift into steady outflows;
a new geopolitical or trade shock;
Nasdaq starts a deep correction.
Then BTC loses:
$80,000.
Next zone:
$75,000–76,000.
The breakout opens it:
$70,000–72,000.
In a strong liquidation event, a spike is possible:
$65,000–68,000.
Bearish year-end zone:
$68,000–78,000.
Which historical scenario is currently the most dangerous?
In my view:
2025.
Not 2018.
In 2025, the market also had:
institutional demand;
positive regulatory narrative;
strong stock market;
all-time highs.
And then one trade/geopolitical shock triggered a record wave of liquidations.
More than $19 billion in leverage was destroyed in a very short time.
Therefore the main risk for 2026 is:
not a slow bear market.
And a sharp liquidity shock inside an overall healthier structure.
Which scenario is most bullish?
Not 2017.
A:
2020.
But only if macroeconomics starts moving in the same direction.
2020 worked because Bitcoin got all of this at the same time:
supply shock;
institutional adoption;
cheap money;
global liquidity.
Today, institutional adoption is already here.
But cheap capital:
not yet.
That’s why the Fed remains the main barrier to a real move to a new ATH.
The main takeaway from 16 years of history
The strongest Bitcoin rallies didn’t happen just because:
after the halving.
They happened when the halving or constrained supply coincided with:
an expansion of liquidity.
2013 — new speculative capital.
2017 — retail mania + institutional access.
2020–2021 — nearly zero rates + stimulus + institutionals.
2024–2025 — spot ETF + regulatory optimism.
And vice versa:
when liquidity was disappearing:
2014;
2018;
2022;
Bitcoin was moving into deep drawdowns.
What changed in 2026
Today BTC has one advantage it never had in the past after-cycle years:
a structural buyer via ETFs.
That’s why I don’t expect a mechanical repetition:
2014;
2018;
But you also can’t ignore macroeconomics.
The Fed is not saving the market right now.
She:
raises rates.
And this is a fundamental difference from 2020.
What I will track until the end of the year
$90,000
First real breakout.
$100,000
The line between recovery and a new expansion phase.
ETF flows
If inflows remain consistently positive, then fundamental support remains intact.
10-year Treasury
Below 4.7–4.8%:
bullish.
Above 5.1–5.2%:
bearish.
CPI
October 14.
November 10.
December 10.
FOMC
October 28.
December 9.
Nasdaq
Bitcoin is behaving much more like an institutional risk asset right now than like a standalone crypto market.
My forecast for December 31, 2026
Current zone:
$85,000–86,000
Support:
$82,000
Main support:
$79,000–80,000
Strong support:
$75,000–76,000
Bearish breakdown:
below $70,000–72,000
First resistance:
$87,000–90,000
Main breakout:
$90,000
Next target:
$95,000
The main psychological level:
$100,000
Bullish extension:
$105,000–110,000
Strong Q4:
$115,000–120,000
ATH:
$125,000–126,000
Summary
If you look only at the calendar, Bitcoin is currently in a dangerous spot.
In four-year logic, 2026 corresponds to:
2014;
2018;
2022.
And all these years ended with a big drop.
But the 2026 market is already different.
Bitcoin now has:
spot ETF;
institutional buyers;
corporate treasury holdings;
a much more mature derivatives infrastructure;
a more favorable regulatory policy.
That’s why the old cycle model can no longer be used mechanically.
At the same time, ETFs don’t cancel out:
rates;
inflation;
Treasury yields;
liquidity;
geopolitical shocks.
That’s why my main scenario for the end of the year — is not a vertical bull run and not a new crypto winter.
And:
gradual recovery with high volatility.
My base zone for the end of 2026:
$90,000–97,000.
Bullish scenario:
$105,000–120,000.
Bearish:
$68,000–78,000.
And the main boundary between these scenarios:
$90,000.
If Bitcoin clears $90K on strong ETF inflows and Treasury yields stabilize, the chance of seeing $100K+ by year-end rises sharply.
If BTC again loses $80K at the same time as ETF outflows and a new jump in inflation expectations, then the historical after-cycle scenario of 2014/2018/2022 will become relevant again.
And this, in my view, is the main takeaway from the entire monthly history of Bitcoin:
Bitcoin doesn’t repeat specific prices. It repeats liquidity regimes, leverage, and investor behavior.
Halving sets the supply structure.
But the direction of big monthly moves is increasingly determined by:
liquidity.
Not financial advice. The forecast is scenario analysis based on historical monthly data, the current macroeconomic situation, ETF flows, and market structure. Historical seasonality and past cycles do not guarantee the repetition of results.
#Bitcoin #BitcoinAnalysis #BitcoinPrediction #CryptoCycle #BinanceSquare