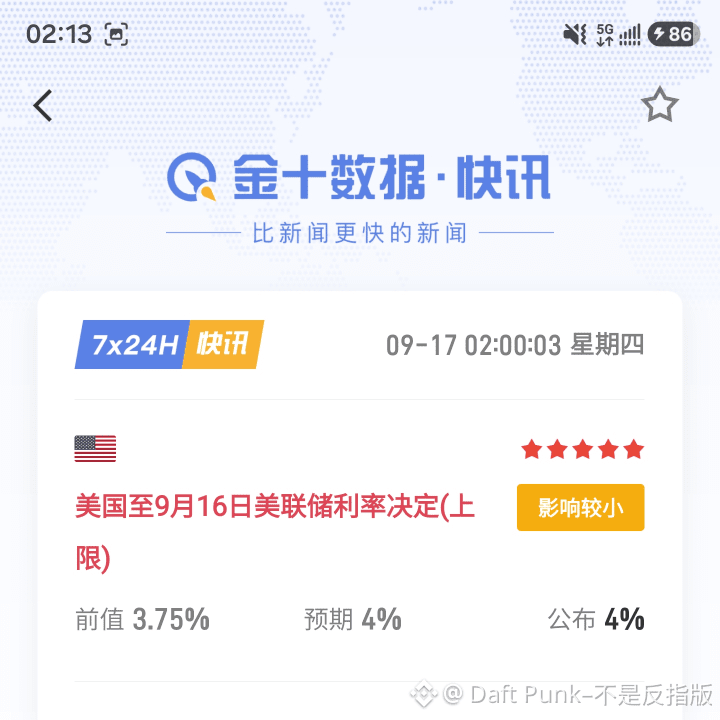

The shoes have hit the ground. The Federal Reserve announced a 25-basis-point rate hike, bringing the federal funds rate into the 3.75%–4% range—its first hike in three years. After the news was released, there was no panic on the trading screen; instead, prices slowly rebounded. This detail is more worth pondering than the hike itself.
The answer is hidden in expectations. As early as before the meeting, the interest rate swap market had already priced in this hike with more than a 90% probability—meaning roughly 23 basis points of tightening had been reflected in prices in advance. Step by step, Wach’s hawkish remarks at Jackson Hole, the strong employment data in August, and the oil price rise driven by the situation in the Middle East all helped set up market psychology. Traders spent weeks adjusting their positioning for defense: shorts that should have been built were built, and leverage that should have been reduced was reduced. By the time the decision was announced, the bad news no longer had any fresh impact—there were even signs of excessive bearish positioning.
This is the classic reverse version of “buy the expectation, sell the fact.” The negative news was already over-allocated during the pricing stage; once it landed, it actually became the removal of uncertainty. The sword hanging over investors’ heads has come down, and the worst-case scenario now has defined boundaries. Naturally, waiting capital is willing to re-enter, and the rebound is a direct expression of this mindset.
Going forward, the key is not the 25 basis points this time, but the path. How the dot plot is drawn, how Waller speaks about subsequent hikes, and whether inflation can hold steady under energy shocks—these determine how long capital is willing to stay. For investors, digesting a single rate hike doesn’t equal an end to the tightening cycle. An environment in which the interest-rate center of gravity moves higher may persist through 2027. For now, the comfortable entry is about sentiment repair; later positioning still needs to follow the data. Don’t take the idea that one piece of negative news has been fully “priced out” as the whole reason to believe in a trend reversal. $ZEC
The answer is hidden in expectations. As early as before the meeting, the interest rate swap market had already priced in this hike with more than a 90% probability—meaning roughly 23 basis points of tightening had been reflected in prices in advance. Step by step, Wach’s hawkish remarks at Jackson Hole, the strong employment data in August, and the oil price rise driven by the situation in the Middle East all helped set up market psychology. Traders spent weeks adjusting their positioning for defense: shorts that should have been built were built, and leverage that should have been reduced was reduced. By the time the decision was announced, the bad news no longer had any fresh impact—there were even signs of excessive bearish positioning.
This is the classic reverse version of “buy the expectation, sell the fact.” The negative news was already over-allocated during the pricing stage; once it landed, it actually became the removal of uncertainty. The sword hanging over investors’ heads has come down, and the worst-case scenario now has defined boundaries. Naturally, waiting capital is willing to re-enter, and the rebound is a direct expression of this mindset.
Going forward, the key is not the 25 basis points this time, but the path. How the dot plot is drawn, how Waller speaks about subsequent hikes, and whether inflation can hold steady under energy shocks—these determine how long capital is willing to stay. For investors, digesting a single rate hike doesn’t equal an end to the tightening cycle. An environment in which the interest-rate center of gravity moves higher may persist through 2027. For now, the comfortable entry is about sentiment repair; later positioning still needs to follow the data. Don’t take the idea that one piece of negative news has been fully “priced out” as the whole reason to believe in a trend reversal. $ZEC