
#derivativesdata
derivativesdata
63 views
7 Discussing
Hot
Latest
The Funding Rate for $SHELL is no longer uniformly negative across platforms, as it was in some previous snapshots.
Data from early on 16/11 shows that Funding rates vary by venue. Some platforms report slightly positive rates of around 0.005–0.01% per period, while others still report negative rates.
Positive Funding generally means Longs pay Shorts; negative Funding generally means Shorts pay Longs.
The differences between platforms show that a single figure should not be used to represent the entire market.
In particular, positive Funding does not mean the price is certain to rise, and negative Funding does not guarantee a short squeeze. This mechanism keeps perpetual contract prices aligned with the Spot market while also providing additional information about positioning.
#SHELL #FundingRate #DerivativesData
The Funding Rate for $SHELL is no longer uniformly negative across platforms, as it was in some previous snapshots.
Data from early on 16/11 shows that Funding rates vary by venue. Some platforms report slightly positive rates of around 0.005–0.01% per period, while others still report negative rates.
Positive Funding generally means Longs pay Shorts; negative Funding generally means Shorts pay Longs.
The differences between platforms show that a single figure should not be used to represent the entire market.
In particular, positive Funding does not mean the price is certain to rise, and negative Funding does not guarantee a short squeeze. This mechanism keeps perpetual contract prices aligned with the Spot market while also providing additional information about positioning.
#SHELL #FundingRate #DerivativesData
Data from early on 16/11 shows that Funding rates vary by venue. Some platforms report slightly positive rates of around 0.005–0.01% per period, while others still report negative rates.
Positive Funding generally means Longs pay Shorts; negative Funding generally means Shorts pay Longs.
The differences between platforms show that a single figure should not be used to represent the entire market.
In particular, positive Funding does not mean the price is certain to rise, and negative Funding does not guarantee a short squeeze. This mechanism keeps perpetual contract prices aligned with the Spot market while also providing additional information about positioning.
#SHELL #FundingRate #DerivativesData
62
Open interest did not move in a straight line after SHELL's November 13 rally.
Tracked derivatives data placed open interest around $12–15.7 million during November 14–15. Some snapshots showed a substantial decline of approximately 25–30% or more over 24 hours.
A decline in open interest means the outstanding derivatives exposure has decreased. It can happen when traders close positions, contracts are liquidated, or market participants reduce leverage.
When price and open interest decline together, it may indicate that positions are being unwound during the retracement.
However, open interest does not identify every trader's intention or reveal whether the remaining market is dominated by longs or shorts.
The important point is that the derivatives market was changing rapidly after the initial price spike.
#OpenInterest #SHELL #DerivativesData
Open interest did not move in a straight line after SHELL's November 13 rally.
Tracked derivatives data placed open interest around $12–15.7 million during November 14–15. Some snapshots showed a substantial decline of approximately 25–30% or more over 24 hours.
A decline in open interest means the outstanding derivatives exposure has decreased. It can happen when traders close positions, contracts are liquidated, or market participants reduce leverage.
When price and open interest decline together, it may indicate that positions are being unwound during the retracement.
However, open interest does not identify every trader's intention or reveal whether the remaining market is dominated by longs or shorts.
The important point is that the derivatives market was changing rapidly after the initial price spike.
#OpenInterest #SHELL #DerivativesData
Tracked derivatives data placed open interest around $12–15.7 million during November 14–15. Some snapshots showed a substantial decline of approximately 25–30% or more over 24 hours.
A decline in open interest means the outstanding derivatives exposure has decreased. It can happen when traders close positions, contracts are liquidated, or market participants reduce leverage.
When price and open interest decline together, it may indicate that positions are being unwound during the retracement.
However, open interest does not identify every trader's intention or reveal whether the remaining market is dominated by longs or shorts.
The important point is that the derivatives market was changing rapidly after the initial price spike.
#OpenInterest #SHELL #DerivativesData
46
$BTC : Total open interest is sitting flat at +0.32% (24h), but the exchange-level split is where the real signal is.
CME OI: -10.98% (24h) → institutional futures contracting
Bybit OI: +4.91% (24h) → retail leverage expanding
when aggregate data stays flat but venue-level positioning diverges this sharply, it usually means capital rotation is happening beneath the surface, not stagnation.
Environments like this, where leverage is unevenly distributed across participant types, often produce sharper-than-expected moves in either direction. Range-aware execution (not directional conviction) tends to handle this kind of setup better...
#OpenInterest #DerivativesData #BTC
$BTC : Total open interest is sitting flat at +0.32% (24h), but the exchange-level split is where the real signal is.
CME OI: -10.98% (24h) → institutional futures contracting
Bybit OI: +4.91% (24h) → retail leverage expanding
when aggregate data stays flat but venue-level positioning diverges this sharply, it usually means capital rotation is happening beneath the surface, not stagnation.
Environments like this, where leverage is unevenly distributed across participant types, often produce sharper-than-expected moves in either direction. Range-aware execution (not directional conviction) tends to handle this kind of setup better...
#OpenInterest #DerivativesData #BTC
CME OI: -10.98% (24h) → institutional futures contracting
Bybit OI: +4.91% (24h) → retail leverage expanding
when aggregate data stays flat but venue-level positioning diverges this sharply, it usually means capital rotation is happening beneath the surface, not stagnation.
Environments like this, where leverage is unevenly distributed across participant types, often produce sharper-than-expected moves in either direction. Range-aware execution (not directional conviction) tends to handle this kind of setup better...
#OpenInterest #DerivativesData #BTC
52
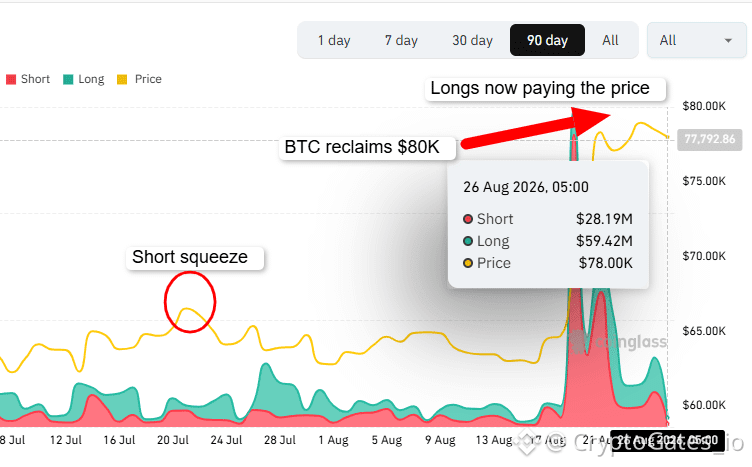
$BTC : Liquidation flow has rotated.
Short liquidations fueled the move back to $80K (3-month high). In the latest 24h window, long liquidations are now dominant as price cools off the local top.
This is a textbook positioning rotation, leverage gets punished wherever it stacks up, not based on market direction alone.
For active traders, this is exactly the kind of volatility regime where wider stop placement and reduced leverage sizing matter more than usual.
#BTC #Liquidations #DerivativesData
$BTC : Liquidation flow has rotated.
Short liquidations fueled the move back to $80K (3-month high). In the latest 24h window, long liquidations are now dominant as price cools off the local top.
This is a textbook positioning rotation, leverage gets punished wherever it stacks up, not based on market direction alone.
For active traders, this is exactly the kind of volatility regime where wider stop placement and reduced leverage sizing matter more than usual.
#BTC #Liquidations #DerivativesData
Short liquidations fueled the move back to $80K (3-month high). In the latest 24h window, long liquidations are now dominant as price cools off the local top.
This is a textbook positioning rotation, leverage gets punished wherever it stacks up, not based on market direction alone.
For active traders, this is exactly the kind of volatility regime where wider stop placement and reduced leverage sizing matter more than usual.
#BTC #Liquidations #DerivativesData
50
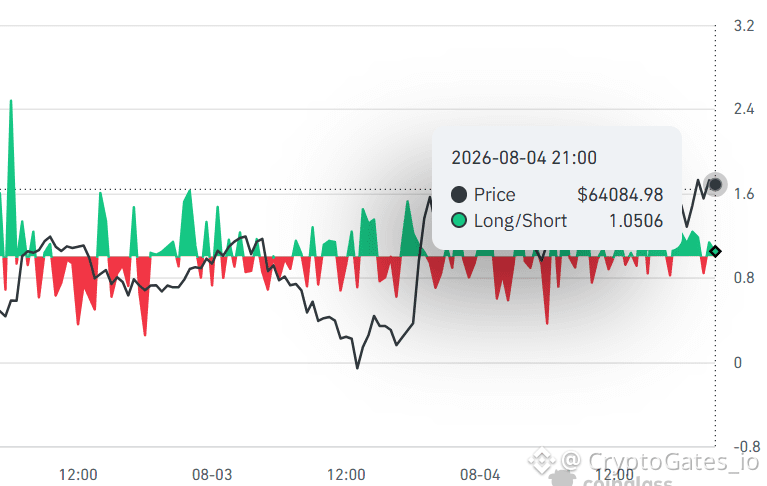
📊 Positioning divergence forming.
Retail long/short ratios on Binance, OKX, and Bybit are all above 1.3 - a clear bullish tilt at the retail level.
Aggregate market-wide long/short, however, sits close to flat at 51%/49%.
The takeaway: retail conviction is concentrated on one side while the broader market hasn't confirmed it.
This kind of setup has historically raised volatility risk on the next directional move, without indicating which way it resolves.
Execution-relevant note: crowded one-sided retail leverage is exactly the environment where wider risk parameters and structured position sizing matter most.
Stress test your setup before the crowd unwinds
#LongShortRatio #DerivativesData #CryptoGates
📊 Positioning divergence forming.
Retail long/short ratios on Binance, OKX, and Bybit are all above 1.3 - a clear bullish tilt at the retail level.
Aggregate market-wide long/short, however, sits close to flat at 51%/49%.
The takeaway: retail conviction is concentrated on one side while the broader market hasn't confirmed it.
This kind of setup has historically raised volatility risk on the next directional move, without indicating which way it resolves.
Execution-relevant note: crowded one-sided retail leverage is exactly the environment where wider risk parameters and structured position sizing matter most.
Stress test your setup before the crowd unwinds
#LongShortRatio #DerivativesData #CryptoGates
Retail long/short ratios on Binance, OKX, and Bybit are all above 1.3 - a clear bullish tilt at the retail level.
Aggregate market-wide long/short, however, sits close to flat at 51%/49%.
The takeaway: retail conviction is concentrated on one side while the broader market hasn't confirmed it.
This kind of setup has historically raised volatility risk on the next directional move, without indicating which way it resolves.
Execution-relevant note: crowded one-sided retail leverage is exactly the environment where wider risk parameters and structured position sizing matter most.
Stress test your setup before the crowd unwinds
#LongShortRatio #DerivativesData #CryptoGates
50
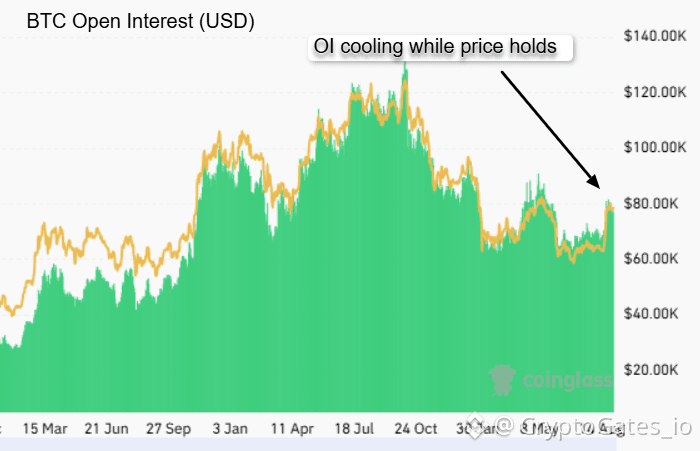
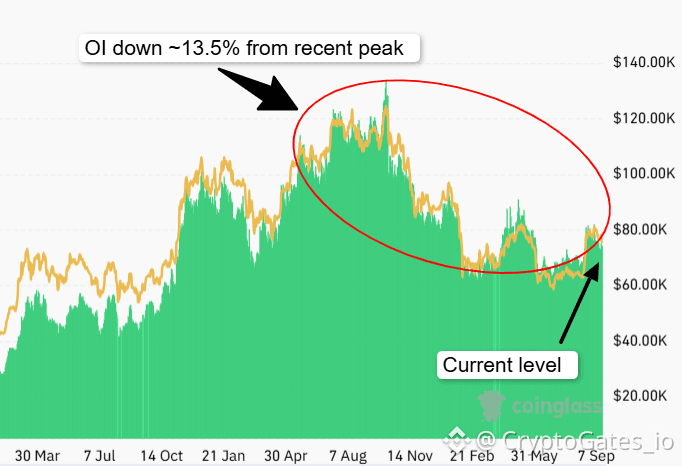
$BTC : Open Interest has pulled back roughly 13.5% from its recent high.
Two catalysts sit directly ahead: the Fed's rate decision and the CLARITY Act Senate vote. Leverage coming off without a matching liquidation cascade typically signals discipline,with positionss being trimmed proactively rather than liquidated reactively.
historically, this kind of setup precedes leverage rebuilding once the event risk clears, not a directional break beforehand.
If you're holding a leveraged position into this week, this is exactly the scenario a Strategy Stress Test is designed to model before you size in.
Stress test your edge...
#OpenInterest #BTC #DerivativesData
$BTC : Open Interest has pulled back roughly 13.5% from its recent high.
Two catalysts sit directly ahead: the Fed's rate decision and the CLARITY Act Senate vote. Leverage coming off without a matching liquidation cascade typically signals discipline,with positionss being trimmed proactively rather than liquidated reactively.
historically, this kind of setup precedes leverage rebuilding once the event risk clears, not a directional break beforehand.
If you're holding a leveraged position into this week, this is exactly the scenario a Strategy Stress Test is designed to model before you size in.
Stress test your edge...
#OpenInterest #BTC #DerivativesData
Two catalysts sit directly ahead: the Fed's rate decision and the CLARITY Act Senate vote. Leverage coming off without a matching liquidation cascade typically signals discipline,with positionss being trimmed proactively rather than liquidated reactively.
historically, this kind of setup precedes leverage rebuilding once the event risk clears, not a directional break beforehand.
If you're holding a leveraged position into this week, this is exactly the scenario a Strategy Stress Test is designed to model before you size in.
Stress test your edge...
#OpenInterest #BTC #DerivativesData
95
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
21,702 views
143 Discussing
2
#SolanaSets2027RoadmapToDoubleComputeCapacity
5,920 views
232 Discussing
3
#CaliforniaNvidiaProbeExaminesPotentialCriminalViolations
2,986 views
44 Discussing
4
#BlackRockLaunchesHKDollarDigitalLiquidityFund
6,857 views
227 Discussing
5
#NvidiaLoses$2.7TrillionInMonthAndAHalf
53,840 views
252 Discussing
6
#GlobalStocksFaceLongestLosingStreakSince2023
453,121 views
2,934 Discussing
7
#BlackRockIBITPostsRecord$541MSingleDayOutflow
70,596 views
158 Discussing
8
#AnthropicPlungesTowardIPOPriceonDay2
246,777 views
1,930 Discussing
9
#TwentyOneCapitalAdds172.25BTC
122,603 views
1,286 Discussing
10
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
15,606 views
89 Discussing