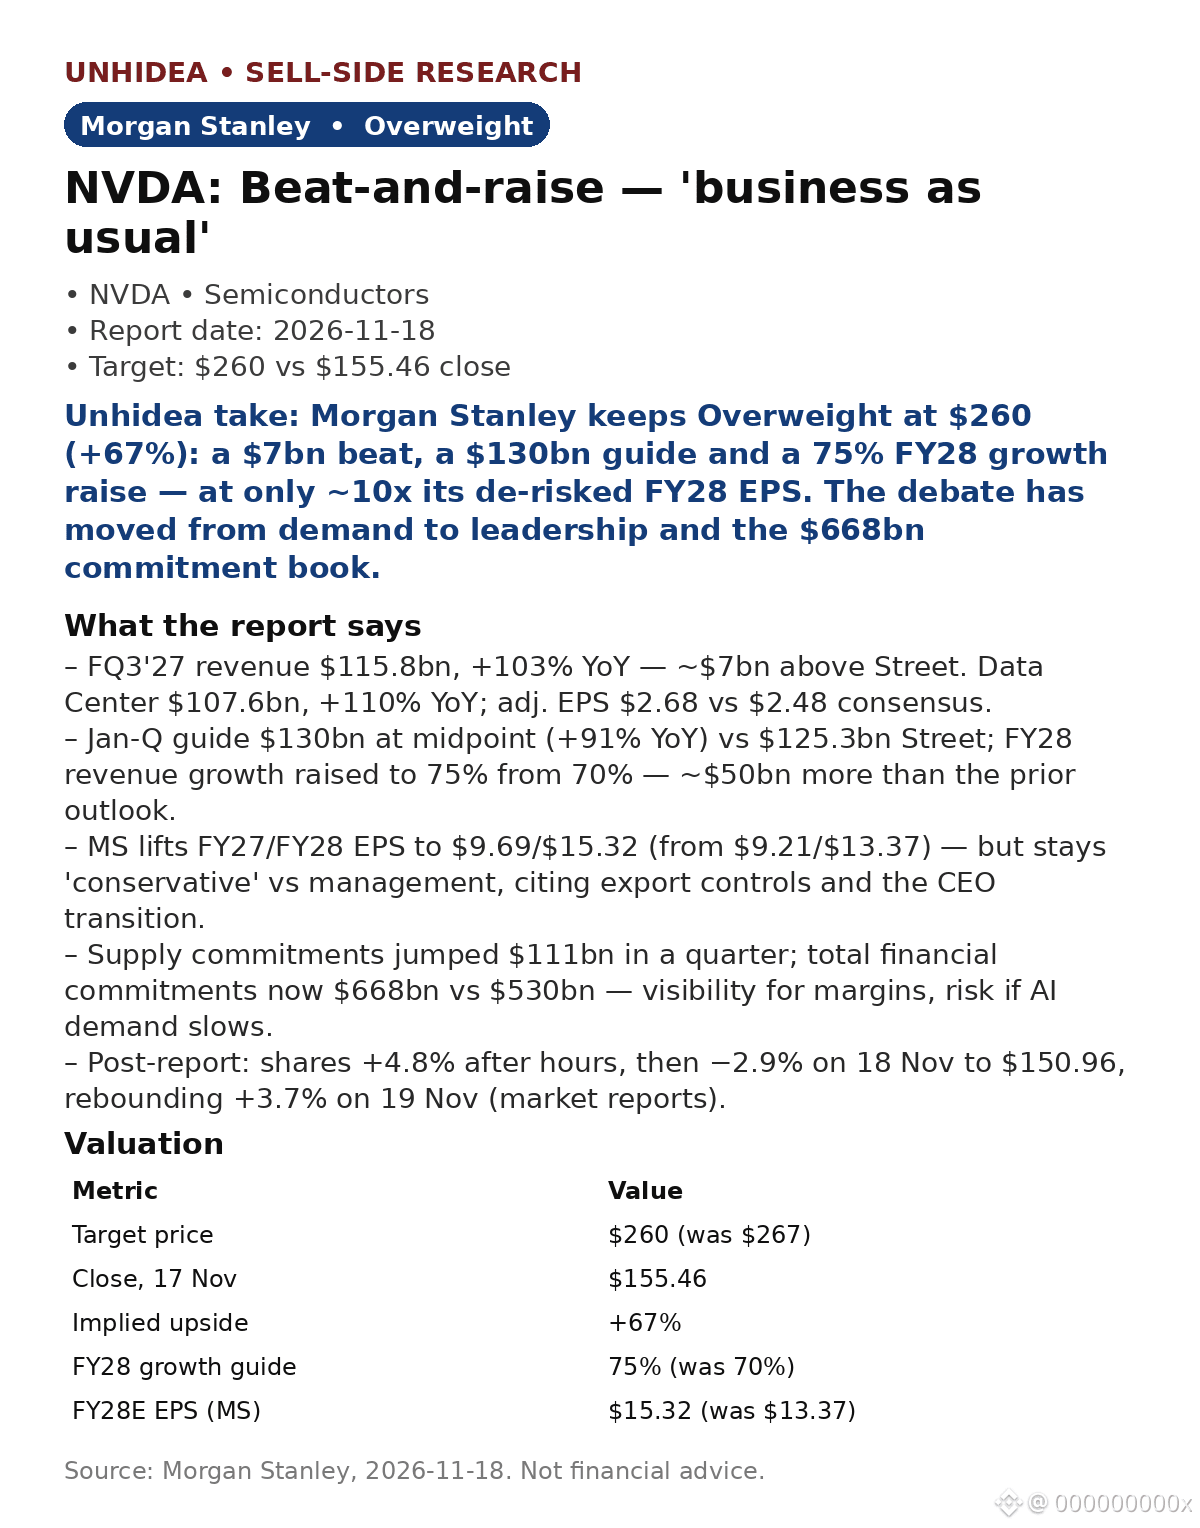
$NVDA: Morgan Stanley calls the beat-and-raise "business as usual" — Overweight, $260 target, +67% vs the $155.46 close on 17 Nov.
- FQ3'27: revenue $115.8bn, +103% YoY, ~$7bn above Street. Data Center $107.6bn, +110% YoY. Adj. EPS $2.68 vs $2.48 consensus; margin 74.9%.
- Guide: Jan-Q revenue $130bn at midpoint (+91% YoY) vs $125.3bn Street; FY28 growth raised to 75% from 70% — ~$50bn more than the prior outlook.
- MS lifts FY27/FY28 EPS to $9.69/$15.32; PT trimmed $267→$260 on a lower ~12x multiple.
- Post-report: +4.8% after hours, −2.9% on 18 Nov to $150.96, +3.7% rebound on 19 Nov (market reports).
Unhidea take: the guide raise matters more than the beat — 75% FY28 growth off a $424bn base underwrites the AI buildout, even mid-CEO transition.
Unhidea take: MS models "conservatively" at ~10x de-risked FY28 EPS and still sees +67%. The debate is no longer demand — it's whether $668bn of commitments is an asset or an anchor.
Valuation: Overweight, $260 (~12x CY28E EPS $21.04), +67% vs $155.46 close 17 Nov.
Risks: BIS export controls, DOJ/SEC probes, no permanent CEO yet, higher rates.
Source: Morgan Stanley, 18 Nov 2026. Not financial advice.
- FQ3'27: revenue $115.8bn, +103% YoY, ~$7bn above Street. Data Center $107.6bn, +110% YoY. Adj. EPS $2.68 vs $2.48 consensus; margin 74.9%.
- Guide: Jan-Q revenue $130bn at midpoint (+91% YoY) vs $125.3bn Street; FY28 growth raised to 75% from 70% — ~$50bn more than the prior outlook.
- MS lifts FY27/FY28 EPS to $9.69/$15.32; PT trimmed $267→$260 on a lower ~12x multiple.
- Post-report: +4.8% after hours, −2.9% on 18 Nov to $150.96, +3.7% rebound on 19 Nov (market reports).
Unhidea take: the guide raise matters more than the beat — 75% FY28 growth off a $424bn base underwrites the AI buildout, even mid-CEO transition.
Unhidea take: MS models "conservatively" at ~10x de-risked FY28 EPS and still sees +67%. The debate is no longer demand — it's whether $668bn of commitments is an asset or an anchor.
Valuation: Overweight, $260 (~12x CY28E EPS $21.04), +67% vs $155.46 close 17 Nov.
Risks: BIS export controls, DOJ/SEC probes, no permanent CEO yet, higher rates.
Source: Morgan Stanley, 18 Nov 2026. Not financial advice.