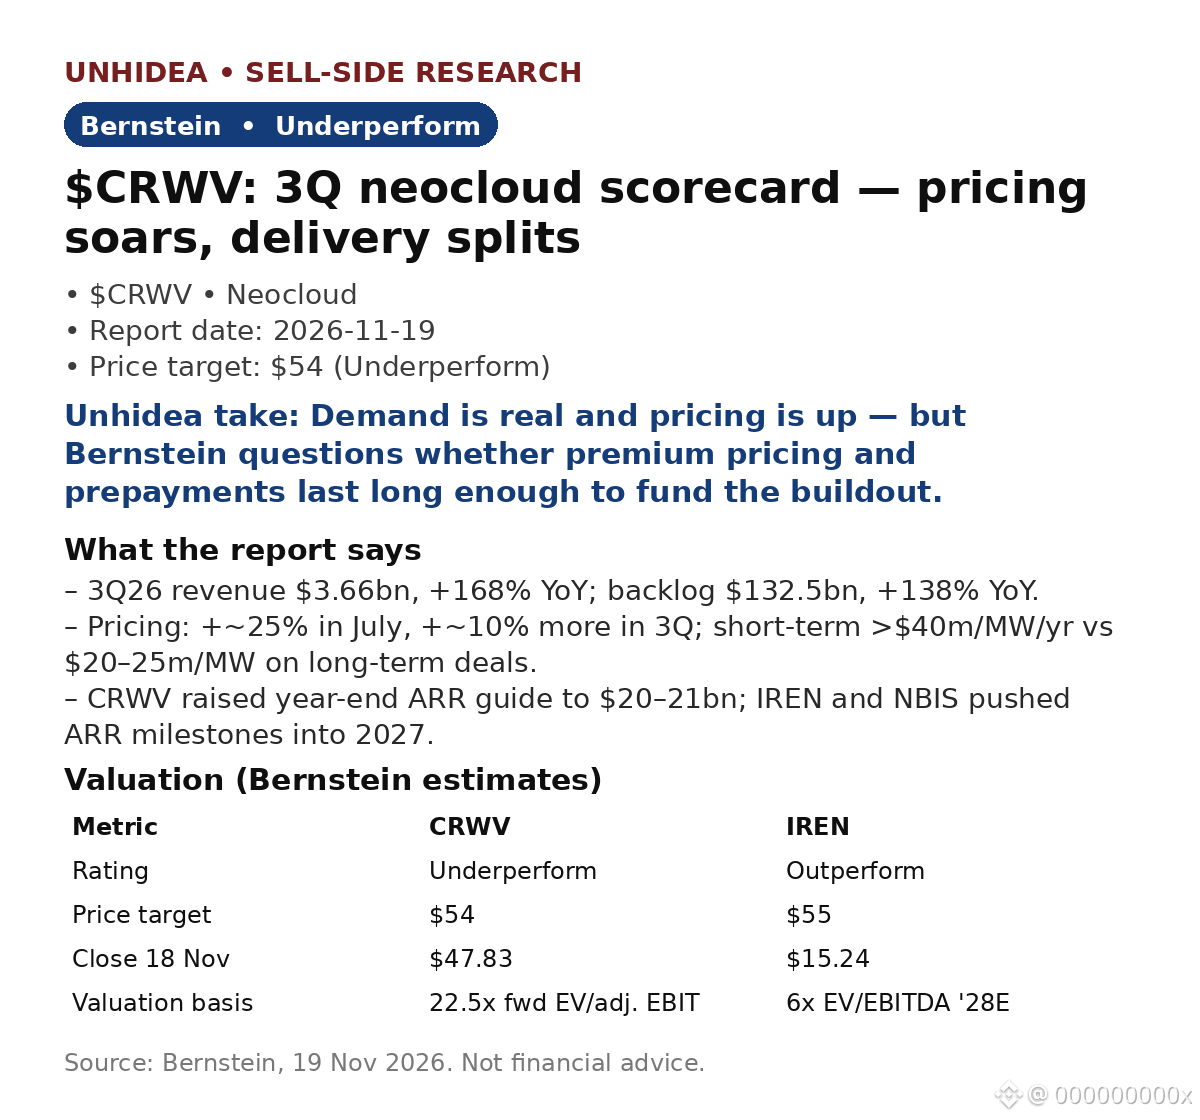
$CRWV: Bernstein stays Underperform at $54 — even as neocloud pricing jumped ~25% in July, then ~10% more in 3Q.
- Revenue $3.66bn, +168% YoY, beat guidance of $3.45–3.60bn; backlog $132.5bn, +138% YoY; qualified demand ~10x available capacity through 2027.
- Adj. EBITDA $2.26bn, +169% YoY, 62% margin (59% in 2Q); adj. operating income $379m, 10% margin vs $128m / 5% in 2Q — double-digit margins a quarter early.
- Pricing: short-term deals fetch >$40m/MW a year vs $20–25m/MW on 4–5yr terms; Ampere/Hopper pricing +30–50% QoQ.
- Delivery split: CRWV >1.7GW active, YE ARR guide raised to $20–21bn; IREN pushed its >$4bn operating ARR milestone to early 2027; NBIS delayed its >$7bn ARR target to Feb 2027.
- Funding: CRWV FY26 CapEx $37–39bn, backed by ~$9bn prepayments; IREN cut FY27 spend to ~$15bn. But 3Q interest was $846m — over 2x adj. operating income.
- Shares -6.1% on 19 Nov to $44.91; NBIS -9.4%. (Post-report market data.)
Unhidea take: backlog is a promise, energised power is the product — CRWV delivered, IREN and NBIS slipped. Watch GW online, not GW contracted.
Unhidea take: a $54 target, +13% vs the $47.83 close on 18 Nov, with an Underperform rating is a relative call — CRWV can rise and still lose to the market if premium pricing fades as supply catches up.
Risks: pricing/prepayment durability; funding model; delivery execution.
Source: Bernstein, 19 Nov 2026. Not financial advice.
- Revenue $3.66bn, +168% YoY, beat guidance of $3.45–3.60bn; backlog $132.5bn, +138% YoY; qualified demand ~10x available capacity through 2027.
- Adj. EBITDA $2.26bn, +169% YoY, 62% margin (59% in 2Q); adj. operating income $379m, 10% margin vs $128m / 5% in 2Q — double-digit margins a quarter early.
- Pricing: short-term deals fetch >$40m/MW a year vs $20–25m/MW on 4–5yr terms; Ampere/Hopper pricing +30–50% QoQ.
- Delivery split: CRWV >1.7GW active, YE ARR guide raised to $20–21bn; IREN pushed its >$4bn operating ARR milestone to early 2027; NBIS delayed its >$7bn ARR target to Feb 2027.
- Funding: CRWV FY26 CapEx $37–39bn, backed by ~$9bn prepayments; IREN cut FY27 spend to ~$15bn. But 3Q interest was $846m — over 2x adj. operating income.
- Shares -6.1% on 19 Nov to $44.91; NBIS -9.4%. (Post-report market data.)
Unhidea take: backlog is a promise, energised power is the product — CRWV delivered, IREN and NBIS slipped. Watch GW online, not GW contracted.
Unhidea take: a $54 target, +13% vs the $47.83 close on 18 Nov, with an Underperform rating is a relative call — CRWV can rise and still lose to the market if premium pricing fades as supply catches up.
Risks: pricing/prepayment durability; funding model; delivery execution.
Source: Bernstein, 19 Nov 2026. Not financial advice.