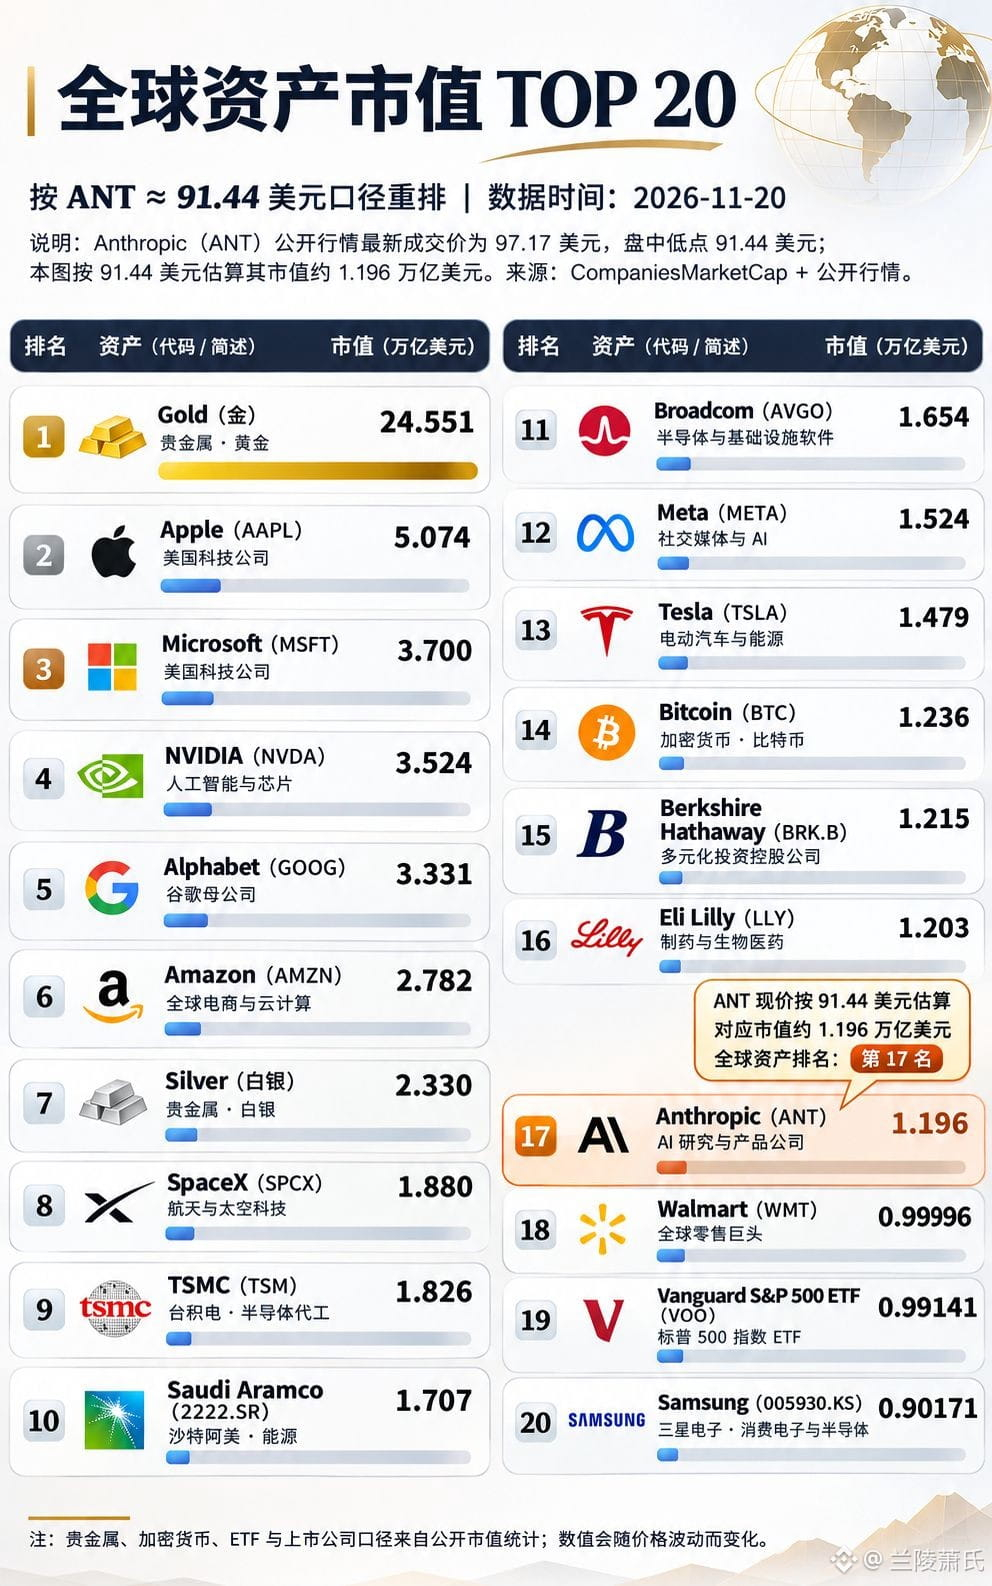
$ANT.US is currently trading around $91, ranking 17th globally by market cap.
This valuation is already quite expensive, with the market having priced in a significant amount of growth expected over the next few years.
And the AI industry is different from traditional software. With traditional software, marginal costs may fall as the user base grows. But every time a large model is called, it consumes computing power. Rapid revenue growth doesn’t necessarily mean profits will grow at the same pace. The key will be whether the company can improve its profit margins going forward.
Also, don’t overlook the competition from OpenAI and Google. AI models are improving so quickly that being ahead today doesn’t mean you’ll still be ahead six months from now. So, for Anthropic to sustain a trillion-dollar market cap over the long term, it can’t rely solely on Claude’s strong capabilities. It will also need to build a real competitive moat through enterprise customers, a product ecosystem, and sustained profitability.
In the short term, I think ANT will probably need some time after its listing to digest its valuation and share supply. The area around $91 is worth watching, but there’s no need to rush into a large position for now.
If it stabilizes in this range and trading volume and buying support start to improve, you could consider entering in stages. Conversely, if it breaks below key support, that would indicate the market is still repricing the stock. In that case, I’d rather wait for a better entry point than force a purchase.
Over the medium to long term, I’m still bullish on Anthropic.
There will be no shortage of opportunities in AI, but only a handful of companies will ultimately survive.
Anthropic has a chance to be one of them.
For now, though, I’d rather treat ANT as a high-growth, high-valuation, high-volatility tech stock—not as a long-term asset you can buy and then ignore the price of.
This valuation is already quite expensive, with the market having priced in a significant amount of growth expected over the next few years.
And the AI industry is different from traditional software. With traditional software, marginal costs may fall as the user base grows. But every time a large model is called, it consumes computing power. Rapid revenue growth doesn’t necessarily mean profits will grow at the same pace. The key will be whether the company can improve its profit margins going forward.
Also, don’t overlook the competition from OpenAI and Google. AI models are improving so quickly that being ahead today doesn’t mean you’ll still be ahead six months from now. So, for Anthropic to sustain a trillion-dollar market cap over the long term, it can’t rely solely on Claude’s strong capabilities. It will also need to build a real competitive moat through enterprise customers, a product ecosystem, and sustained profitability.
In the short term, I think ANT will probably need some time after its listing to digest its valuation and share supply. The area around $91 is worth watching, but there’s no need to rush into a large position for now.
If it stabilizes in this range and trading volume and buying support start to improve, you could consider entering in stages. Conversely, if it breaks below key support, that would indicate the market is still repricing the stock. In that case, I’d rather wait for a better entry point than force a purchase.
Over the medium to long term, I’m still bullish on Anthropic.
There will be no shortage of opportunities in AI, but only a handful of companies will ultimately survive.
Anthropic has a chance to be one of them.
For now, though, I’d rather treat ANT as a high-growth, high-valuation, high-volatility tech stock—not as a long-term asset you can buy and then ignore the price of.