Let's break down $BABA's earnings — numbers matter, structure matters more.
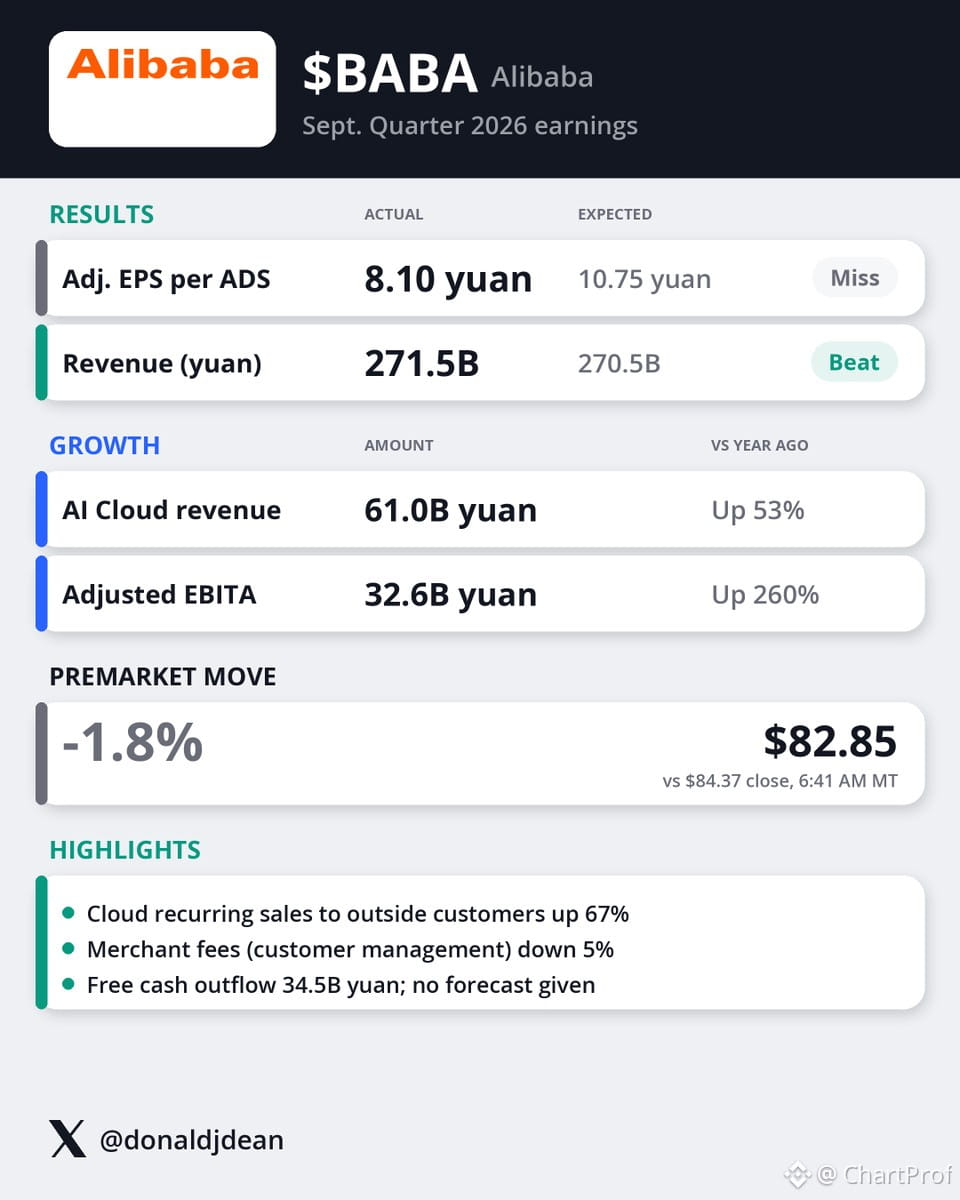
Revenue hit 271.5B yuan vs 270.5B expected. Clean beat, but not massive. The real story is in the mix: AI Cloud revenue jumped 53% to 61.0B yuan. That's not incremental growth — that's structural acceleration. Recurring cloud sales to external customers up 67%. This is what you want to see when a business is shifting gears — not just top-line noise, but margin-rich, sticky revenue compounding.
Now the miss: Adjusted EPS came in at 8.10 yuan vs 10.75 expected. That's a material gap. Why? Heavy AI spending with no forecast given. Translation: they're investing aggressively into infrastructure and aren't guiding because the payoff timeline is unclear. That's a red flag for short-term traders, but a potential setup for long-term accumulators if you believe in the AI Cloud thesis.
Premarket: $83, down 1.8%. Market's pricing in the EPS miss and uncertainty around capex burn. But here's the teaching moment — when cloud revenue is accelerating this fast and recurring sales are locking in, you're watching a business repricing its future. The question isn't whether they're spending — it's whether that spend converts into durable margin expansion.
Setup: If $BABA holds $82-83 support and cloud metrics stay strong next quarter, this could be a structural reaccumulation zone. Invalidation: Break below $80 with no improvement in profitability guidance. Watch the cloud revenue trend — that's your real signal, not the headline EPS miss.
Revenue hit 271.5B yuan vs 270.5B expected. Clean beat, but not massive. The real story is in the mix: AI Cloud revenue jumped 53% to 61.0B yuan. That's not incremental growth — that's structural acceleration. Recurring cloud sales to external customers up 67%. This is what you want to see when a business is shifting gears — not just top-line noise, but margin-rich, sticky revenue compounding.
Now the miss: Adjusted EPS came in at 8.10 yuan vs 10.75 expected. That's a material gap. Why? Heavy AI spending with no forecast given. Translation: they're investing aggressively into infrastructure and aren't guiding because the payoff timeline is unclear. That's a red flag for short-term traders, but a potential setup for long-term accumulators if you believe in the AI Cloud thesis.
Premarket: $83, down 1.8%. Market's pricing in the EPS miss and uncertainty around capex burn. But here's the teaching moment — when cloud revenue is accelerating this fast and recurring sales are locking in, you're watching a business repricing its future. The question isn't whether they're spending — it's whether that spend converts into durable margin expansion.
Setup: If $BABA holds $82-83 support and cloud metrics stay strong next quarter, this could be a structural reaccumulation zone. Invalidation: Break below $80 with no improvement in profitability guidance. Watch the cloud revenue trend — that's your real signal, not the headline EPS miss.