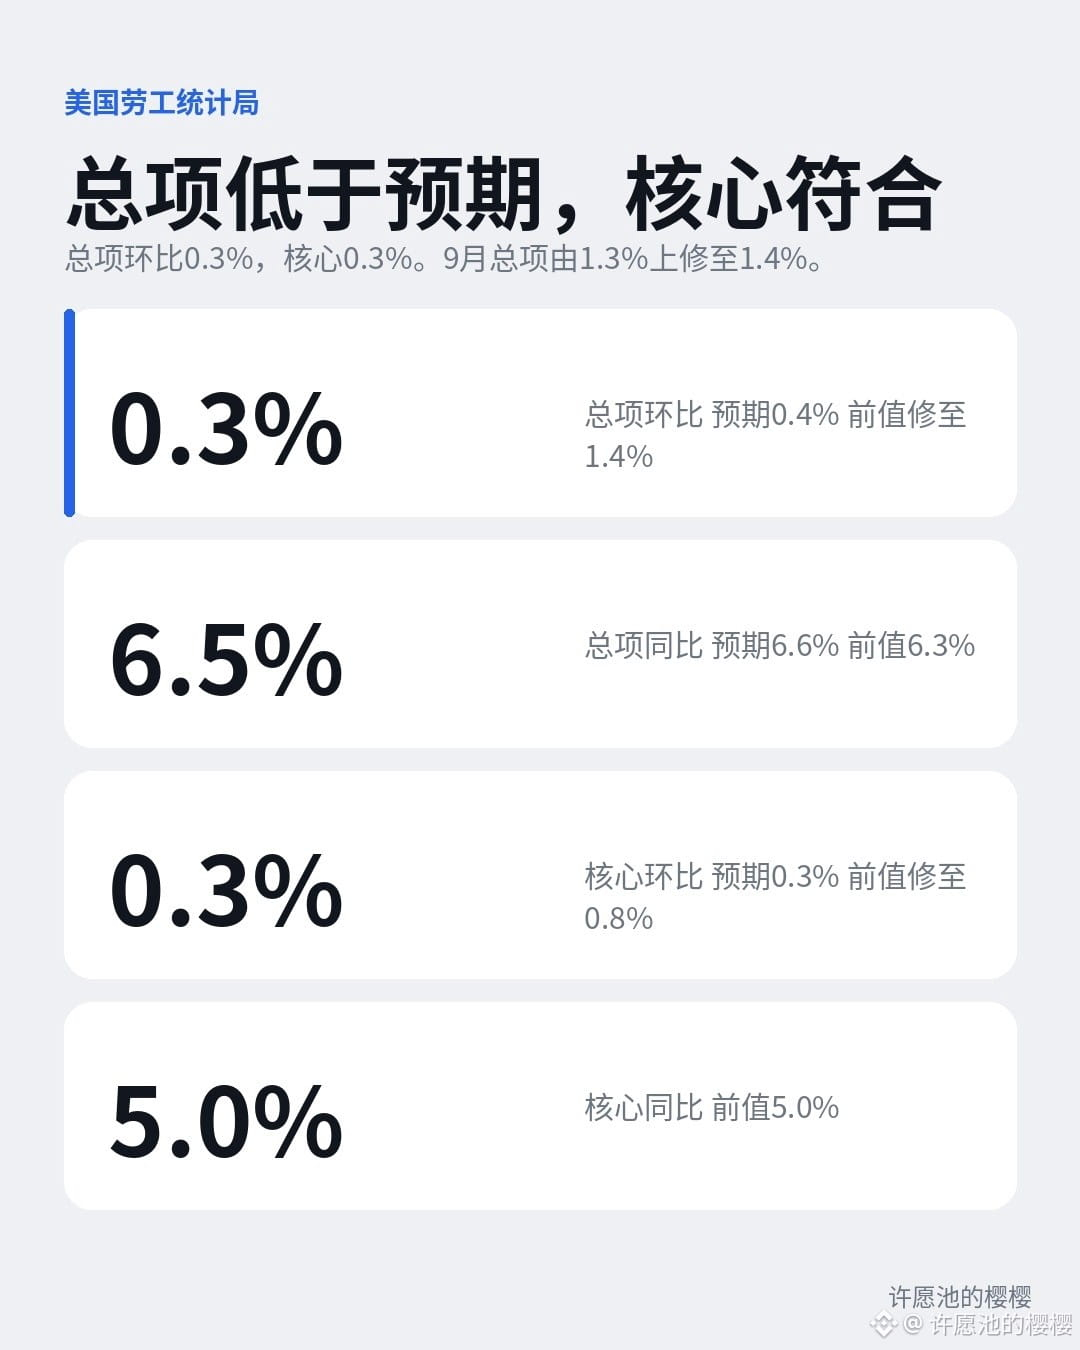
Headline month over month: +0.3%; core month over month: +0.3%. 【Slightly bullish】The U.S. Bureau of Labor Statistics released October’s PPI tonight at 21:30 Beijing time. The Dow Jones survey that markets generally used as a benchmark ahead of the release expected headline month-over-month growth of 0.4% and core growth of 0.3%; the headline year-over-year figure was expected to be 6.6%, versus 6.3% previously.
Bitcoin initially plunged to 69068.14 at the moment of the release, then surged to 69678.28. Compared with 69246 before the release, the wick’s low was down about 0.3%. It continued climbing over the next ten-odd minutes, reaching 70214. ETH first dipped from around 1957 to 1950.11, then rebounded to 1989. At around 21:39, I saw Bitcoin near 70000 and ETH around 1984.
First, the official figures. In October, seasonally adjusted month-over-month headline growth fell back to +0.3% from September’s revised +1.4% (September was initially reported at +1.3%, then revised up to +1.4% tonight). Core, excluding food and energy, rose +0.3%, exactly in line with expectations, but September’s core figure was also revised up from +0.7% to +0.8%. Headline year-over-year growth was +6.5%, one of the highest readings since November 2022, but slightly below the 6.6% expected; core year-over-year growth remained at 5.0%. Goods rose +0.5%, services +0.2%, energy fell -0.1%, while food rose 1.3%. PPI can be understood as the prices factories and businesses pay for their inputs. Those input costs often move first, with consumer prices following after a while. Much of September’s jump came from energy; tonight, energy was nearly flat.
Those expected figures came from a Dow Jones survey reported by the media before the release, not from the Bureau of Labor Statistics’ own forecast. If that benchmark is roughly accurate, headline month-over-month growth came in a little below the 0.4% forecast, while core landed right at 0.3%. Don’t compare it only with September and call it cooling—the September figure itself was revised up, and core wasn’t below expectations either. The year-over-year figure rose to 6.5%, partly due to a low base in October 2025; that doesn’t mean inflation has accelerated sharply again.
Personally, I’m more inclined to see this as a reading that came in slightly below expectations, but doesn’t amount to cooling. The market’s initial plunge and rebound are common reactions when data comes out. It’s too early to say whether there will be another rate hike in December; October CPI had already come in hot once, and tonight’s upstream figures may only temper bets on “another hike,” without supporting the claim that “inflation is cooling smoothly.” Next, watch whether the recent highs of 70214 and 1989 hold, and which way the market moves after U.S. stocks open at 22:30. Don’t mistake a one-minute wick for a trend reversal.
Are you more focused on whether month-over-month growth fell from September, or on whether core inflation has genuinely cooled? Share your thoughts in the comments.
$BTC $ETH
Personal opinion, not investment advice
Bitcoin initially plunged to 69068.14 at the moment of the release, then surged to 69678.28. Compared with 69246 before the release, the wick’s low was down about 0.3%. It continued climbing over the next ten-odd minutes, reaching 70214. ETH first dipped from around 1957 to 1950.11, then rebounded to 1989. At around 21:39, I saw Bitcoin near 70000 and ETH around 1984.
First, the official figures. In October, seasonally adjusted month-over-month headline growth fell back to +0.3% from September’s revised +1.4% (September was initially reported at +1.3%, then revised up to +1.4% tonight). Core, excluding food and energy, rose +0.3%, exactly in line with expectations, but September’s core figure was also revised up from +0.7% to +0.8%. Headline year-over-year growth was +6.5%, one of the highest readings since November 2022, but slightly below the 6.6% expected; core year-over-year growth remained at 5.0%. Goods rose +0.5%, services +0.2%, energy fell -0.1%, while food rose 1.3%. PPI can be understood as the prices factories and businesses pay for their inputs. Those input costs often move first, with consumer prices following after a while. Much of September’s jump came from energy; tonight, energy was nearly flat.
Those expected figures came from a Dow Jones survey reported by the media before the release, not from the Bureau of Labor Statistics’ own forecast. If that benchmark is roughly accurate, headline month-over-month growth came in a little below the 0.4% forecast, while core landed right at 0.3%. Don’t compare it only with September and call it cooling—the September figure itself was revised up, and core wasn’t below expectations either. The year-over-year figure rose to 6.5%, partly due to a low base in October 2025; that doesn’t mean inflation has accelerated sharply again.
Personally, I’m more inclined to see this as a reading that came in slightly below expectations, but doesn’t amount to cooling. The market’s initial plunge and rebound are common reactions when data comes out. It’s too early to say whether there will be another rate hike in December; October CPI had already come in hot once, and tonight’s upstream figures may only temper bets on “another hike,” without supporting the claim that “inflation is cooling smoothly.” Next, watch whether the recent highs of 70214 and 1989 hold, and which way the market moves after U.S. stocks open at 22:30. Don’t mistake a one-minute wick for a trend reversal.
Are you more focused on whether month-over-month growth fell from September, or on whether core inflation has genuinely cooled? Share your thoughts in the comments.
$BTC $ETH
Personal opinion, not investment advice