Investing in BTC with DCA—once you set the dates, is that really all there is to it?
You’ve just been paid, and BTC has pulled back. You want to invest a lump sum, but worry you’ll buy at a high. DCA helps if you don’t have time to watch the market or are worried about picking the wrong time to buy. It doesn’t guarantee a profit.
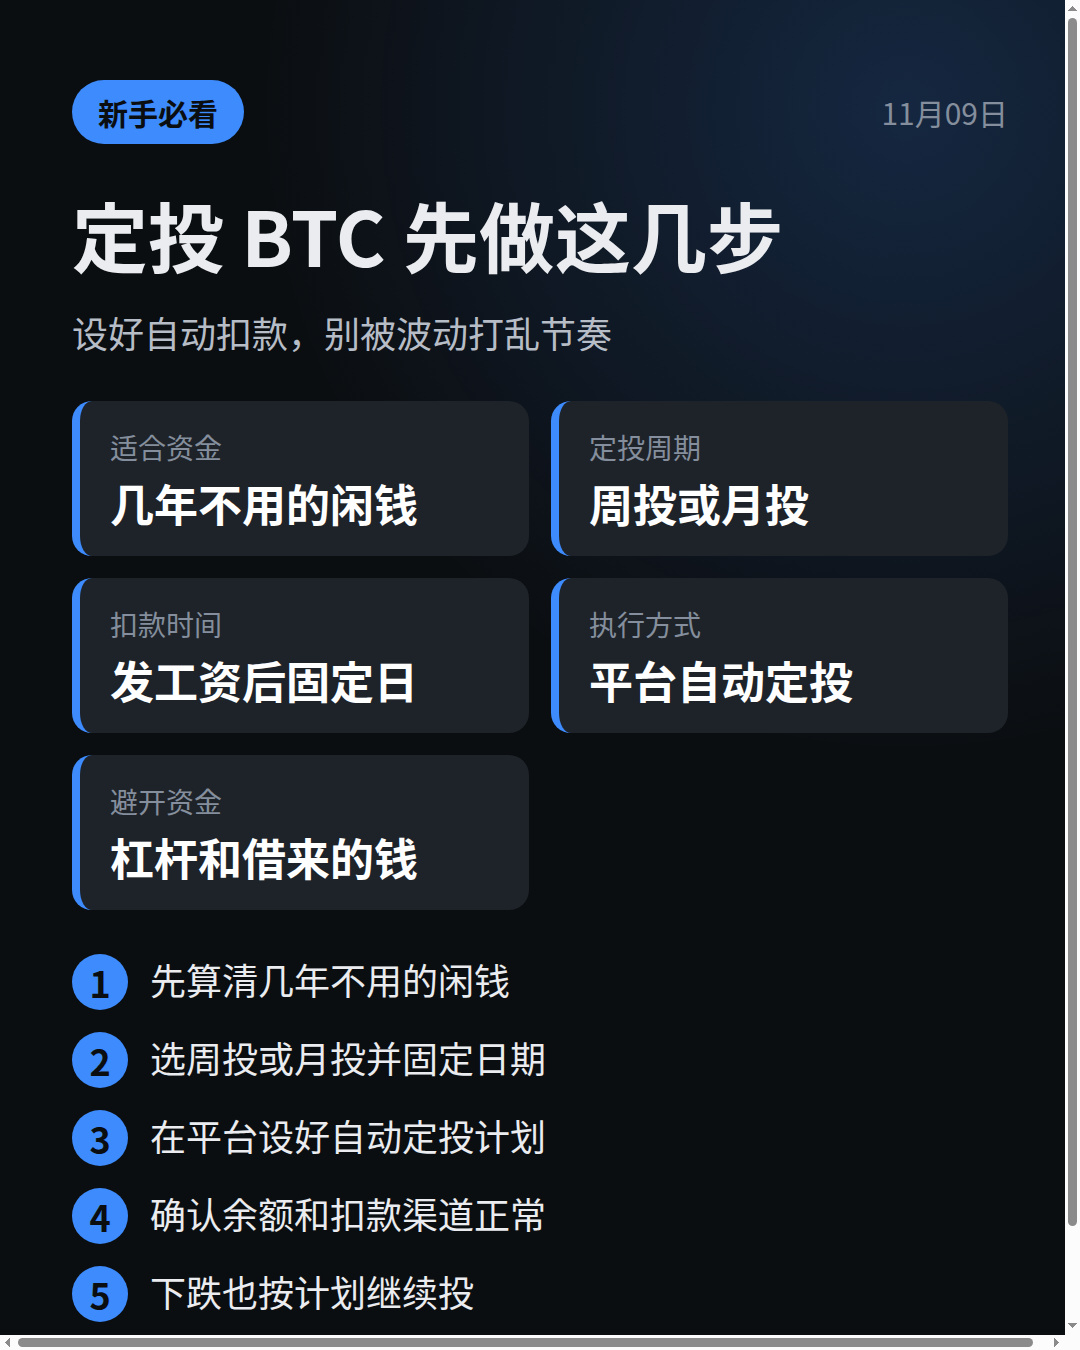
First, who is it right for? If you have money left over regularly, won’t need it for a few years, and can handle volatility, it may suit you. If you’re hoping to double your money in the short term, or plan to invest money for living expenses or money you’ve borrowed, it’s not for you.
1️⃣ First, set aside money you can’t afford to lose: only invest spare money, and make sure investing it won’t affect your rent or groceries. That way, you won’t be forced to stop investing or sell at a loss if prices fall.
2️⃣ Then choose a schedule: weekly or monthly both work. Set up an automatic deduction for a fixed day after payday. Let discipline handle the timing, so you’re less tempted to change the plan on impulse.
3️⃣ Set up an automatic plan: in the platform’s automatic DCA section, choose the coin, amount, and schedule, then confirm the payment method. Automatic execution is easier to stick with than investing manually. Check the official page for the specific steps and rules.
4️⃣ Before you start, make sure your account balance is sufficient and your payment method is working. If your balance is too low, an investment can be missed—and once your rhythm is disrupted, it’s easiest to give up.
5️⃣ Don’t stop when prices fall, and don’t use leverage. Stick to your original plan, and don’t DCA with borrowed money or funds for contracts. A sharp market move could trigger forced liquidation when you use leverage, derailing your long-term plan.
Are you planning to invest weekly or monthly, and for how many years? #DCA
You’ve just been paid, and BTC has pulled back. You want to invest a lump sum, but worry you’ll buy at a high. DCA helps if you don’t have time to watch the market or are worried about picking the wrong time to buy. It doesn’t guarantee a profit.
First, who is it right for? If you have money left over regularly, won’t need it for a few years, and can handle volatility, it may suit you. If you’re hoping to double your money in the short term, or plan to invest money for living expenses or money you’ve borrowed, it’s not for you.
1️⃣ First, set aside money you can’t afford to lose: only invest spare money, and make sure investing it won’t affect your rent or groceries. That way, you won’t be forced to stop investing or sell at a loss if prices fall.
2️⃣ Then choose a schedule: weekly or monthly both work. Set up an automatic deduction for a fixed day after payday. Let discipline handle the timing, so you’re less tempted to change the plan on impulse.
3️⃣ Set up an automatic plan: in the platform’s automatic DCA section, choose the coin, amount, and schedule, then confirm the payment method. Automatic execution is easier to stick with than investing manually. Check the official page for the specific steps and rules.
4️⃣ Before you start, make sure your account balance is sufficient and your payment method is working. If your balance is too low, an investment can be missed—and once your rhythm is disrupted, it’s easiest to give up.
5️⃣ Don’t stop when prices fall, and don’t use leverage. Stick to your original plan, and don’t DCA with borrowed money or funds for contracts. A sharp market move could trigger forced liquidation when you use leverage, derailing your long-term plan.
Are you planning to invest weekly or monthly, and for how many years? #DCA