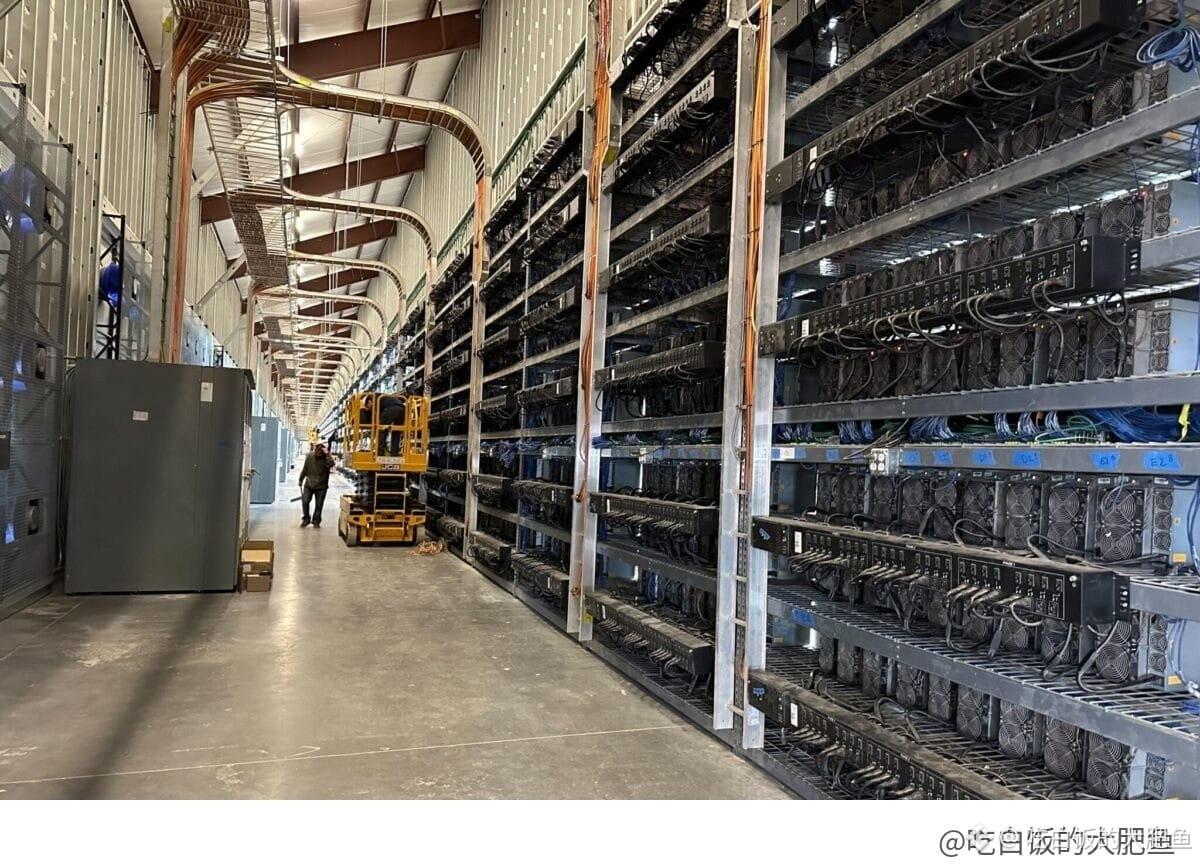
A Bitcoin mining company whose mining revenue is down to just 5%—is it still a mining company?
Core Scientific ($CORZ) reported its Q3 results yesterday: total revenue of $232.9 million, nearly triple year over year and above the market’s $193 million estimate. But the interesting part isn’t how much revenue grew—it’s where it came from:
Colocation revenue from renting data center space to AI companies was $215.4 million, up nearly 60% quarter over quarter and accounting for 92.5% of total revenue. Its own mining brought in just $12.3 million, with hosted mining contributing $5.2 million. Billable capacity reached 485 megawatts, with 90 megawatts added in the quarter, and annualized colocation revenue has already topped $700 million.
Adjusted EBITDA was $133.6 million, with a 57% margin, up from just 25% last quarter. Don’t take the $1.18 billion in net income at face value—it was mainly driven by a non-cash gain from changes in the fair value of warrants. Management said it aims to retire its remaining mining rigs by the end of Q4 and enter 2027 as a colocation provider. It has already signed contracts representing more than $24 billion in revenue and about 1.1 gigawatts of capacity.
This whale’s take: This isn’t just one company’s transformation; it’s a turning point for the entire mining sector. Power and sites are going to AI, and mining $BTC is shifting from “mining coins” to “collecting rent.” The business logic has changed, so the valuation approach needs to change too. But let’s keep a cool head: colocation is a capital-intensive, long-cycle business. It spent $985 million on capital expenditures in a single quarter, and how quickly it earns that back depends entirely on the pace of delivery. As impressive as that 92% figure is, it’s no reason to buy blindly.
Core Scientific ($CORZ) reported its Q3 results yesterday: total revenue of $232.9 million, nearly triple year over year and above the market’s $193 million estimate. But the interesting part isn’t how much revenue grew—it’s where it came from:
Colocation revenue from renting data center space to AI companies was $215.4 million, up nearly 60% quarter over quarter and accounting for 92.5% of total revenue. Its own mining brought in just $12.3 million, with hosted mining contributing $5.2 million. Billable capacity reached 485 megawatts, with 90 megawatts added in the quarter, and annualized colocation revenue has already topped $700 million.
Adjusted EBITDA was $133.6 million, with a 57% margin, up from just 25% last quarter. Don’t take the $1.18 billion in net income at face value—it was mainly driven by a non-cash gain from changes in the fair value of warrants. Management said it aims to retire its remaining mining rigs by the end of Q4 and enter 2027 as a colocation provider. It has already signed contracts representing more than $24 billion in revenue and about 1.1 gigawatts of capacity.
This whale’s take: This isn’t just one company’s transformation; it’s a turning point for the entire mining sector. Power and sites are going to AI, and mining $BTC is shifting from “mining coins” to “collecting rent.” The business logic has changed, so the valuation approach needs to change too. But let’s keep a cool head: colocation is a capital-intensive, long-cycle business. It spent $985 million on capital expenditures in a single quarter, and how quickly it earns that back depends entirely on the pace of delivery. As impressive as that 92% figure is, it’s no reason to buy blindly.