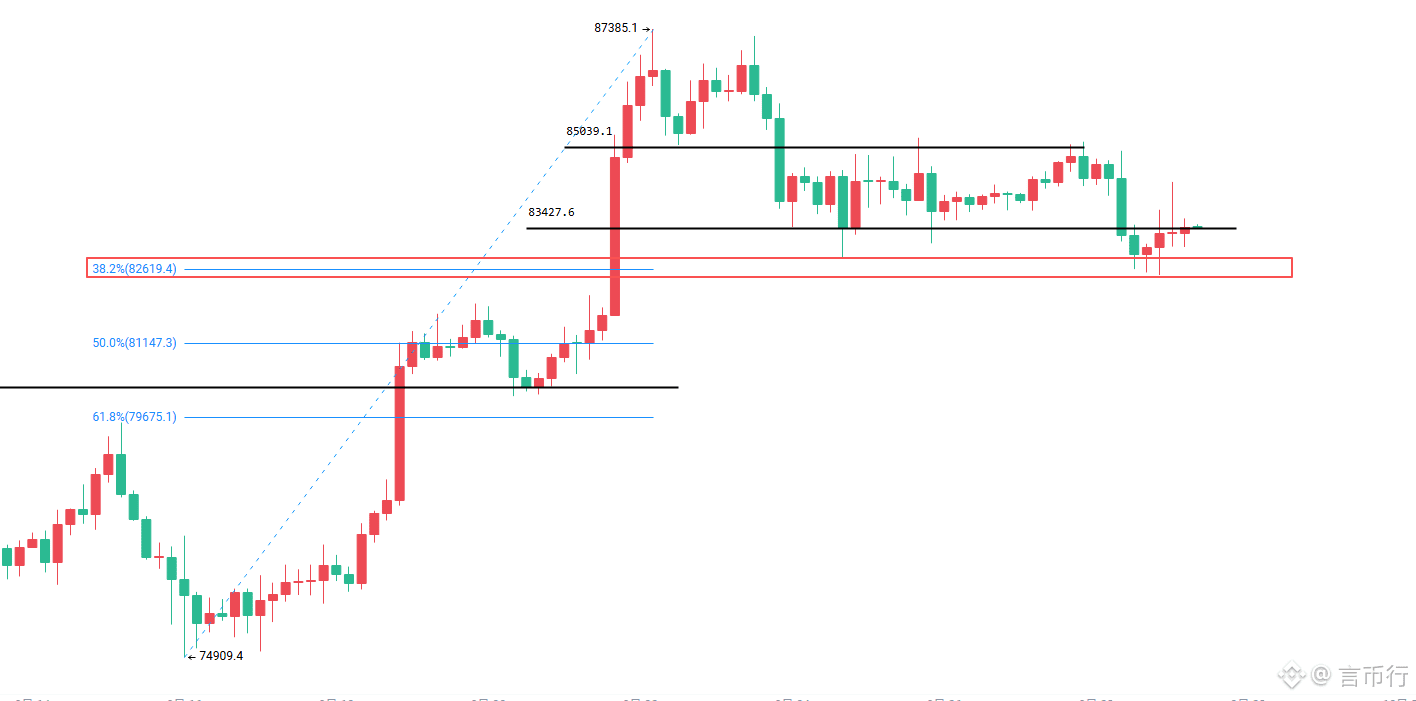
Recent major market index declines have mainly been triggered by:
1. Market-wide expectations that the Fed will continue to raise rates in October (a 0.25 rate hike has a probability as high as 70%). Panic has set in over the next round of hikes, leading to liquidity contraction.
2. Recent conflict between Iran and the U.S. has again pushed international oil prices sharply higher. The eventual rise in oil prices has intensified concerns that inflation may keep recurring, increasing the risk of market risk premiums.
However, on the other hand, we should still note that the market remains relatively restrained. The $82,000 support level is firmly holding, and today it has started to attempt to stabilize above $83,000;
Meanwhile, spot ETFs have recently attracted a large amount of capital. Net inflows in a single week reached approximately $2.4 billion, setting a new high since October last year. Year-to-date cumulative net inflows have already reached $1.0 billion, indicating that institutions are still building positions on dips.
So, based on the above points, and considering the failure of the $82,000 breakthrough, the short ideas shared in the past few days are recommended to be closed out for profit in full ((84,500——83,000; 2,710——2,670)), and we should begin establishing low long entries today around 82,800/2,660, in hopes of a renewed move later—aiming for opportunities to test 87,000/90,000 and 2,800/3,000.