
1500+ liquidations, zero bad debt.
Seeing this number made me go back and review the Zest Protocol again properly.
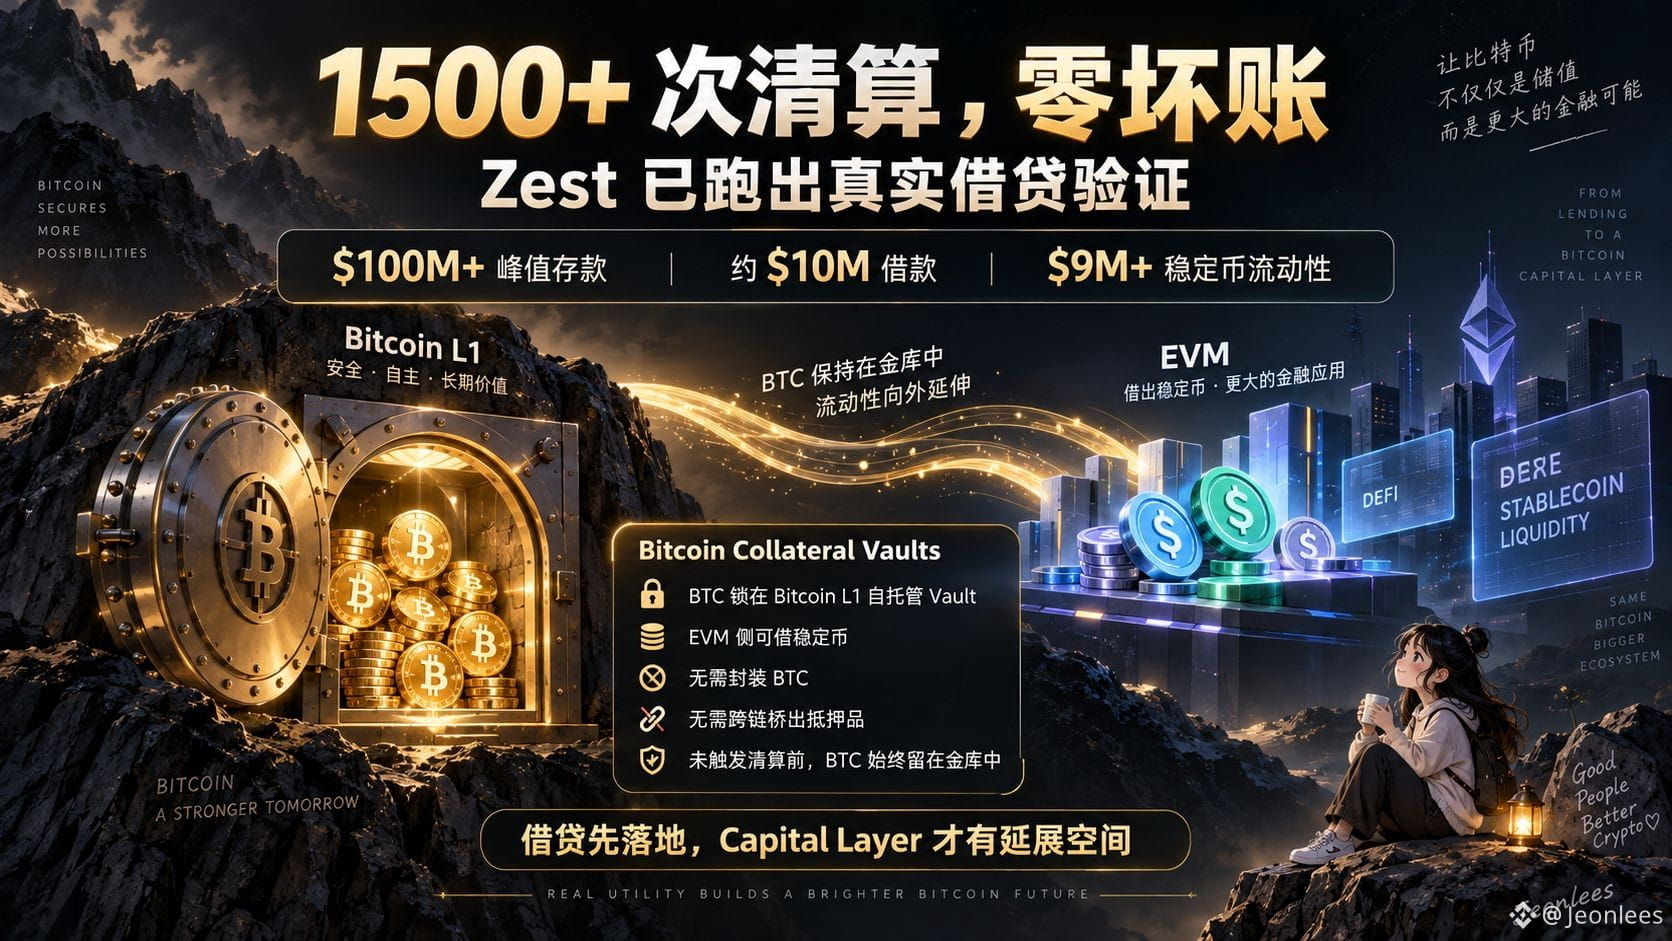
There are many BTCFi projects out there now, and lots of them talk about the “capital layer” and “native BTC yield.” But in the end, lending and borrowing still comes down to whether real funds are actually flowing. According to Zest’s operating records as of August 2026, on Stacks it reached a peak of $100M+ in deposits, about $10M in borrowings, $9M+ in stablecoin liquidity, and it handled 1,500+ liquidations while maintaining zero bad debt.
I think this set of data is far more interesting than just looking at TVL.
When the market is favorable, it’s not hard for capital to come in. What really tests a lending protocol is whether positions can be liquidated smoothly during volatility—and whether the system leaves behind any bad debt. Zest has at least already run through this part using real market conditions, and the interest paid by borrowers also becomes protocol revenue.
Next, what I care about even more is Bitcoin Collateral Vaults.
Its logic is actually very straightforward: users lock $BTC on Bitcoin L1 into independent self-custody vaults, and then they can borrow stablecoins on the EVM chain. BTC doesn’t need to be wrapped first, and it doesn’t need to be bridged out. As long as liquidation isn’t triggered, the BTC stays in the original vault.
This design is quite crucial for BTCFi.
In the past, many strategies required moving BTC to other chains first before entering DeFi, which introduces additional risks like bridges, custodianship, and wrapped assets. What Zest wants to do now is to keep BTC as much as possible on the main network, while extending lending and liquidity outward.
If these vaults can keep running sustainably, lending will just be the first step to take root. Whether the system can later support more financial needs built around native BTC will determine how far this Capital Layer can go.
Seeing this number made me go back and review the Zest Protocol again properly.
There are many BTCFi projects out there now, and lots of them talk about the “capital layer” and “native BTC yield.” But in the end, lending and borrowing still comes down to whether real funds are actually flowing. According to Zest’s operating records as of August 2026, on Stacks it reached a peak of $100M+ in deposits, about $10M in borrowings, $9M+ in stablecoin liquidity, and it handled 1,500+ liquidations while maintaining zero bad debt.
I think this set of data is far more interesting than just looking at TVL.
When the market is favorable, it’s not hard for capital to come in. What really tests a lending protocol is whether positions can be liquidated smoothly during volatility—and whether the system leaves behind any bad debt. Zest has at least already run through this part using real market conditions, and the interest paid by borrowers also becomes protocol revenue.
Next, what I care about even more is Bitcoin Collateral Vaults.
Its logic is actually very straightforward: users lock $BTC on Bitcoin L1 into independent self-custody vaults, and then they can borrow stablecoins on the EVM chain. BTC doesn’t need to be wrapped first, and it doesn’t need to be bridged out. As long as liquidation isn’t triggered, the BTC stays in the original vault.
This design is quite crucial for BTCFi.
In the past, many strategies required moving BTC to other chains first before entering DeFi, which introduces additional risks like bridges, custodianship, and wrapped assets. What Zest wants to do now is to keep BTC as much as possible on the main network, while extending lending and liquidity outward.
If these vaults can keep running sustainably, lending will just be the first step to take root. Whether the system can later support more financial needs built around native BTC will determine how far this Capital Layer can go.