There’s a $1.6 billion settlement event on the horizon for Bitcoin this Friday.
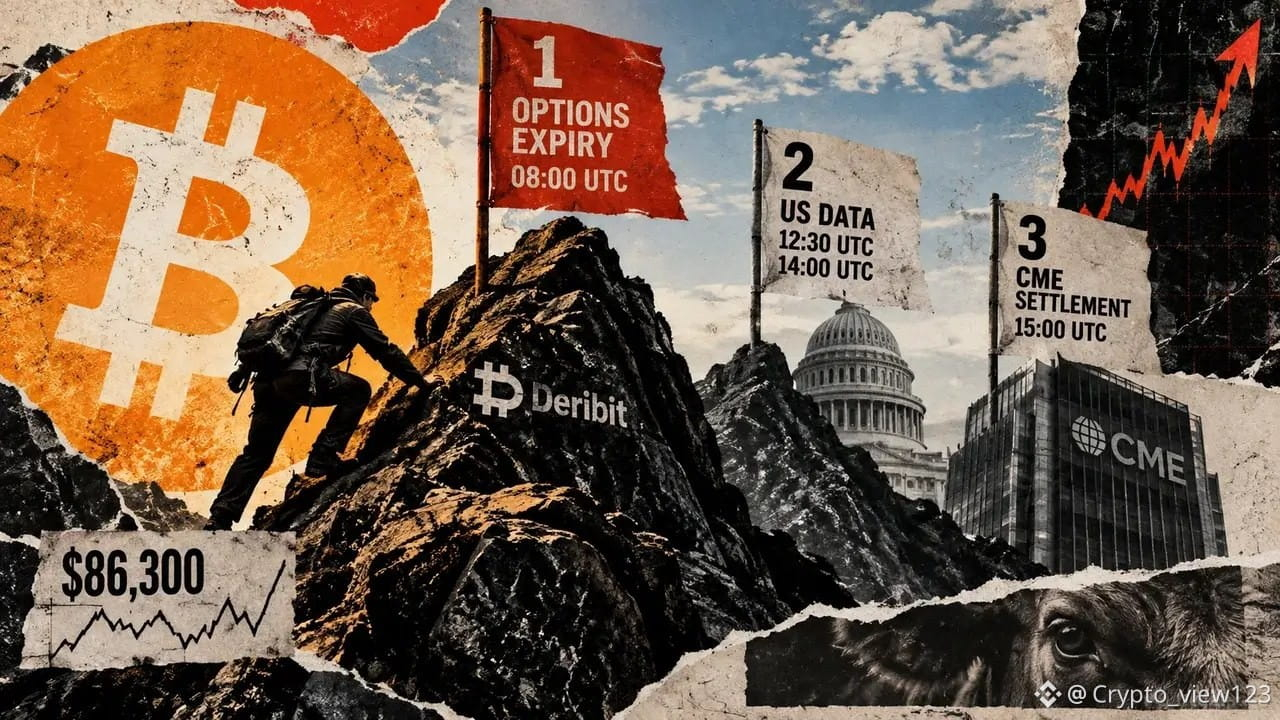
At Deribit, Bitcoin options with a notional value of roughly $16 billion will expire at 08:00 on September 25 (UTC), comprising about $9.6 billion in call options and about $6.4 billion in put options. Ahead of settlement, Bitcoin is trading around $86,300, after briefly crossing above $85,000 earlier this week on Monday.
The timing is even tighter. Within the same trading day, two U.S. economic data releases are scheduled within seven hours, and CME Bitcoin futures for September will also expire—three items packed together, any one of which could trigger volatility.
In structure, calls account for about 60% of open interest at expiry. A market-maker model places the largest call buildup at $95,000, the largest put buildup at $60,000. The put/call ratio is 0.52, with a “zero gamma” level of roughly $71,000. Price is hovering around $86,000, right in the range this model considers stable. For now, the net positioning direction of hedging flows provides some buffering to price movement.
Options themselves don’t indicate direction; they simply price in volatility over the coming days. Deribit’s volatility index was 38.1 on September 22—on the same basis, among the lowest levels in the five-year range. It’s the collision of calm pricing with dense settlement that gives this test its real meaning.
Settlement day doesn’t create direction; it amplifies the positions that are already there.
#比特币 #期权
At Deribit, Bitcoin options with a notional value of roughly $16 billion will expire at 08:00 on September 25 (UTC), comprising about $9.6 billion in call options and about $6.4 billion in put options. Ahead of settlement, Bitcoin is trading around $86,300, after briefly crossing above $85,000 earlier this week on Monday.
The timing is even tighter. Within the same trading day, two U.S. economic data releases are scheduled within seven hours, and CME Bitcoin futures for September will also expire—three items packed together, any one of which could trigger volatility.
In structure, calls account for about 60% of open interest at expiry. A market-maker model places the largest call buildup at $95,000, the largest put buildup at $60,000. The put/call ratio is 0.52, with a “zero gamma” level of roughly $71,000. Price is hovering around $86,000, right in the range this model considers stable. For now, the net positioning direction of hedging flows provides some buffering to price movement.
Options themselves don’t indicate direction; they simply price in volatility over the coming days. Deribit’s volatility index was 38.1 on September 22—on the same basis, among the lowest levels in the five-year range. It’s the collision of calm pricing with dense settlement that gives this test its real meaning.
Settlement day doesn’t create direction; it amplifies the positions that are already there.
#比特币 #期权