

#azure
azure
55,509 views
67 Discussing
Hot
Latest
#MicrosoftSharesRise6%AfterHours
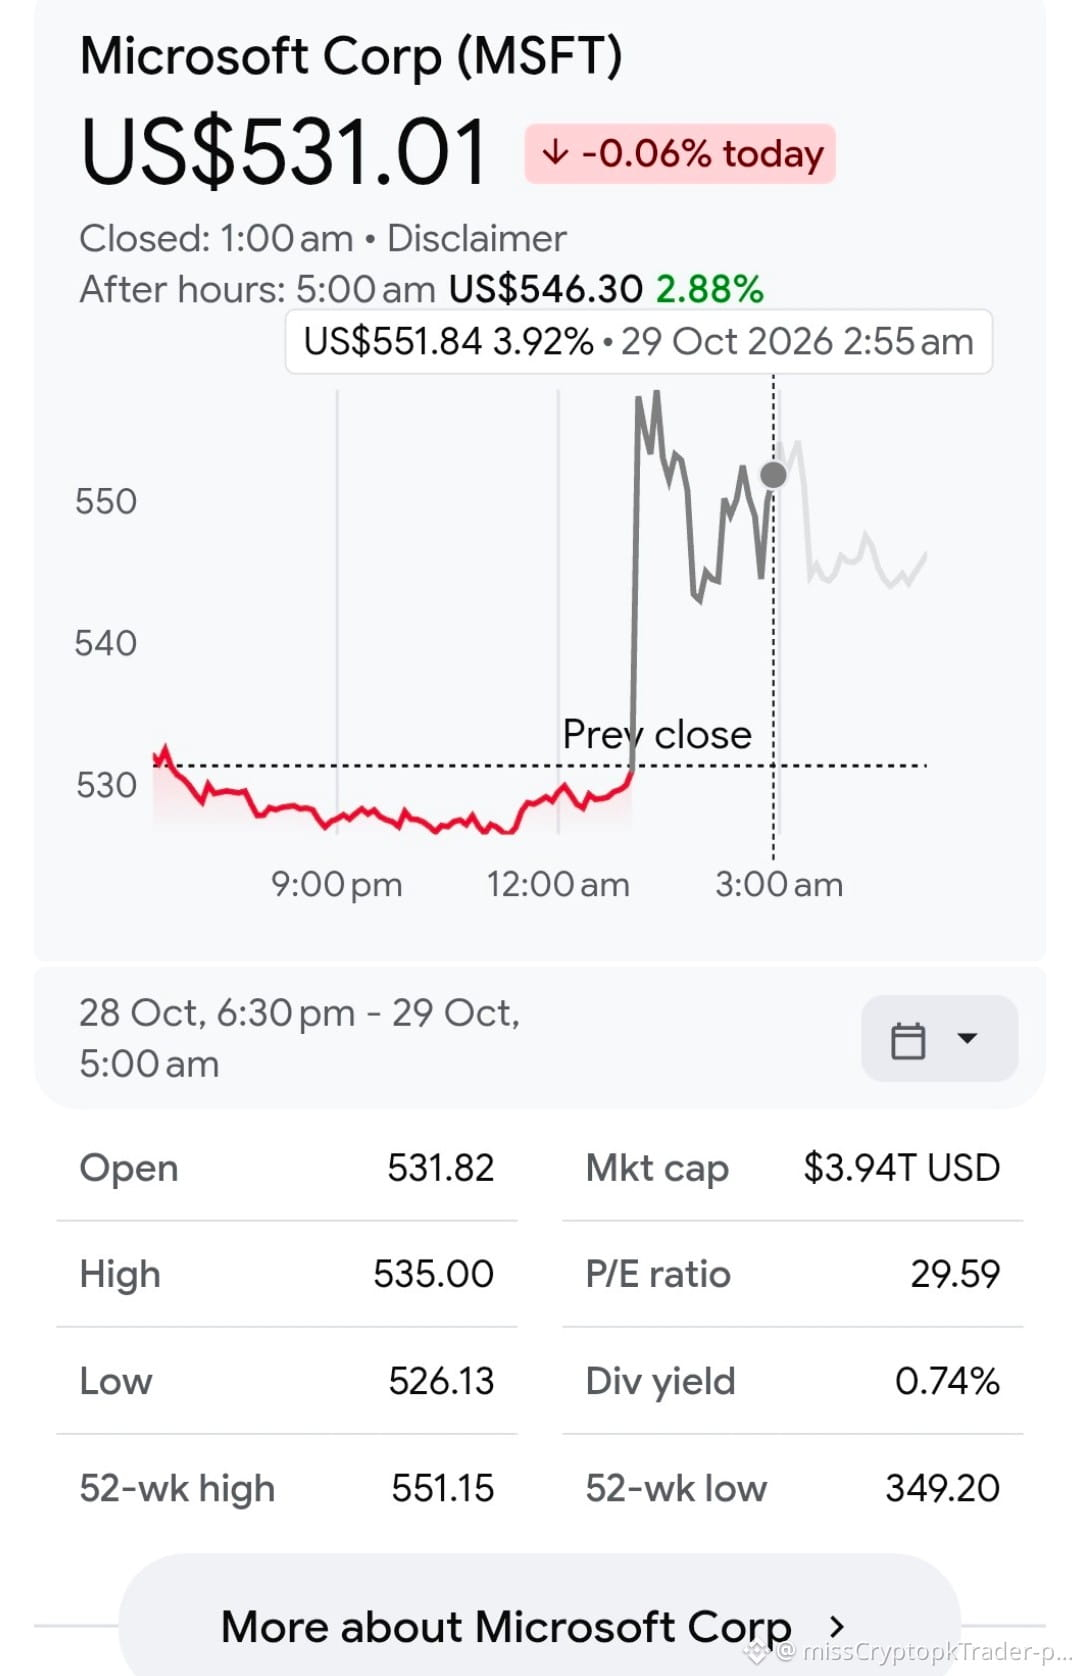
🚨 Microsoft $MSFT jumps 6% after hours!
Q1 2027: Revenue $92.28B +19% YoY (beat $90.6B) | EPS $4.89 (beat $4.73) | Net $36.6B +32%
🔥 Azure $33.17B +48% YoY (beat 44-45%) — AI demand exploding
💰 Capex $45.2B ( $5B BELOW fears) + FCF $18.6B ( $10B ABOVE est)
Regular close $531.01 -0.06% → AH $546.30 → $550 high!
#MicrosoftSharesRise6%AfterHours #MSFT $MSFT #Azure #Earnings
{future}(MSFTUSDT)
#MicrosoftSharesRise6%AfterHours
🚨 Microsoft $MSFT jumps 6% after hours!
Q1 2027: Revenue $92.28B +19% YoY (beat $90.6B) | EPS $4.89 (beat $4.73) | Net $36.6B +32%
🔥 Azure $33.17B +48% YoY (beat 44-45%) — AI demand exploding
💰 Capex $45.2B ( $5B BELOW fears) + FCF $18.6B ( $10B ABOVE est)
Regular close $531.01 -0.06% → AH $546.30 → $550 high!
#MicrosoftSharesRise6%AfterHours #MSFT $MSFT #Azure #Earnings
1
61
·
--
Microsoft’s AI Growth Is Real. But Can It Deliver Long-Term Returns?
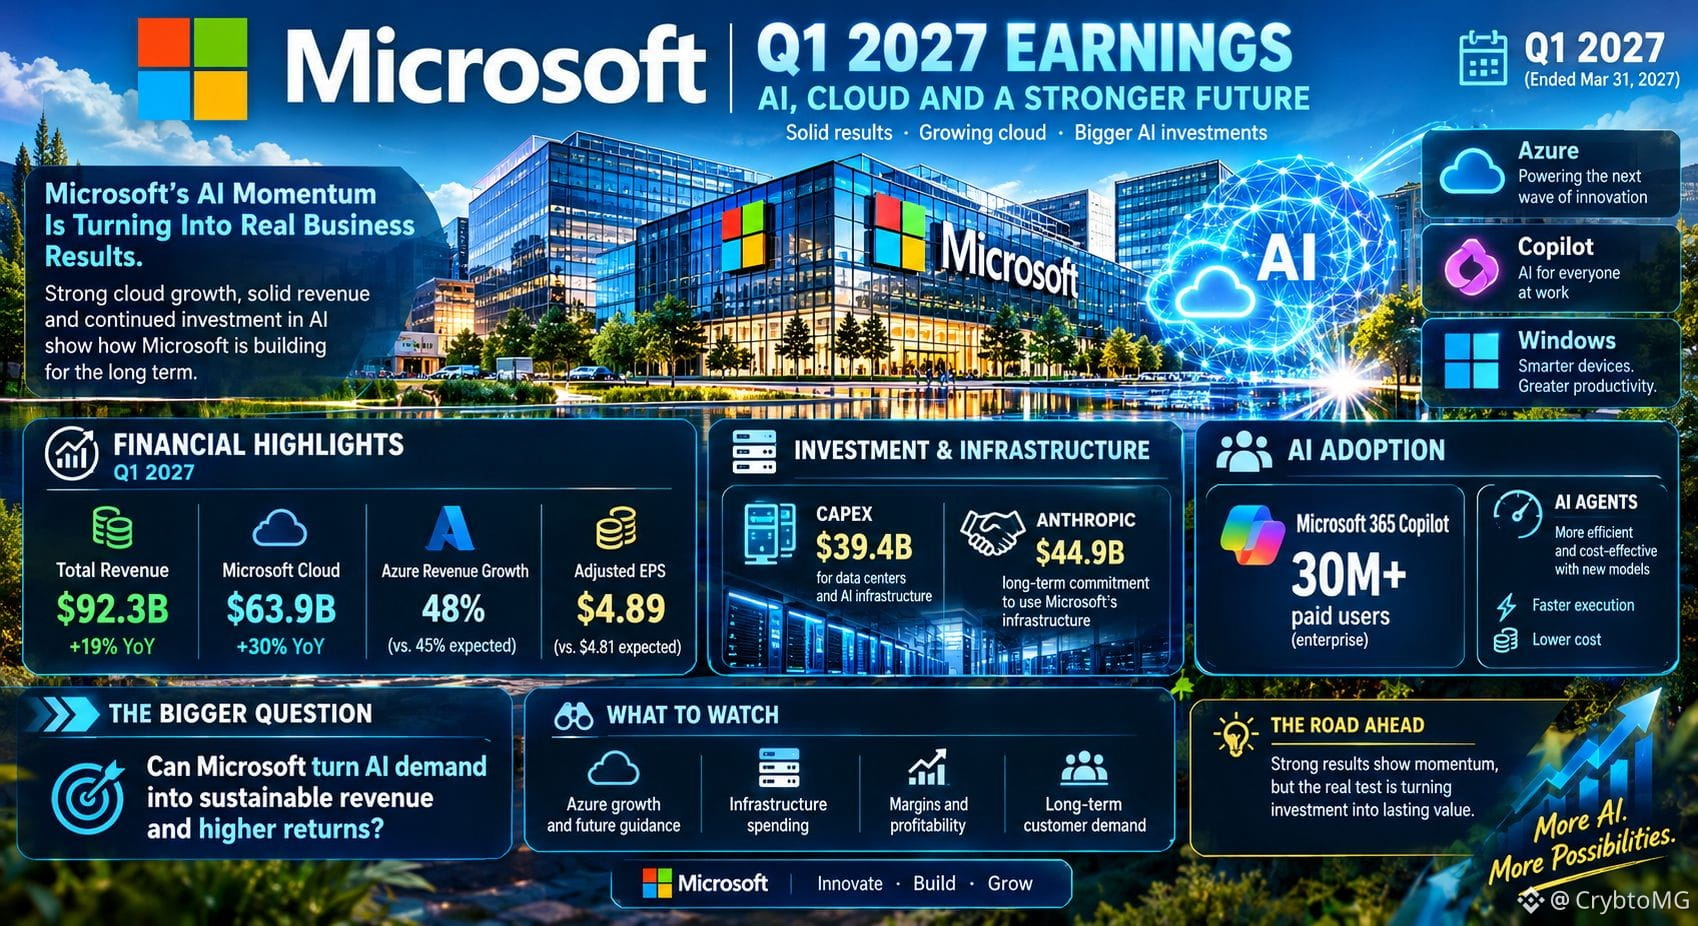
Microsoft’s latest results show strong demand for cloud and AI services:
📊 Total revenue: $92.3B, up 19% year over year
☁️ Microsoft Cloud: $63.9B, up 30%
⚙️ Azure: Revenue growth accelerated to 48%
💰 Adjusted EPS: $4.89
The bigger story is how Microsoft turns that demand into sustainable returns while investing heavily in data centers and AI infrastructure.
Anthropic’s long-term infrastructure commitments also highlight the scale of demand for computing capacity.
But strong revenue growth is only one part of the picture. Investment costs, margins, and future customer demand matter too.
What matters more for AI’s long-term success: faster growth or better returns on investment?
#Microsoft #Aİ #Azure
1
99
#CanMicrosoftDeliverOnAI
While everyone was debating AI hype, Microsoft shipped results:
🔹 Azure crossed *$100B+ annual revenue*, still sold out
🔹 *30M+ paid Copilot seats*, doubling every quarter
🔹 *40M AI Agents built on Agent 365* in 60 days
🔹 Own frontier models – MAI-Voice, MAI-Thinking & Maia 200 chip
🔹 *$80B+ invested* in global AI super-factories
Microsoft is no longer just an AI investor. It's the infrastructure layer for the entire AI economy.
*Why it matters for us in Crypto?*
When Microsoft delivers, AI tokens follow. The demand for compute, agents, and data is real. $FET , $TAO , $RENDER , $AKT.
The question was #CanMicrosoftDeliverOnAI
The answer is: It already did.
What's your bet – Will AI crypto be the next to deliver?
#Microsoft #Azure #AgenticAI

like, share , follow
From Syeda Hoorulain Zaidi
1
169
Verified
#CanMicrosoftDeliverOnAI
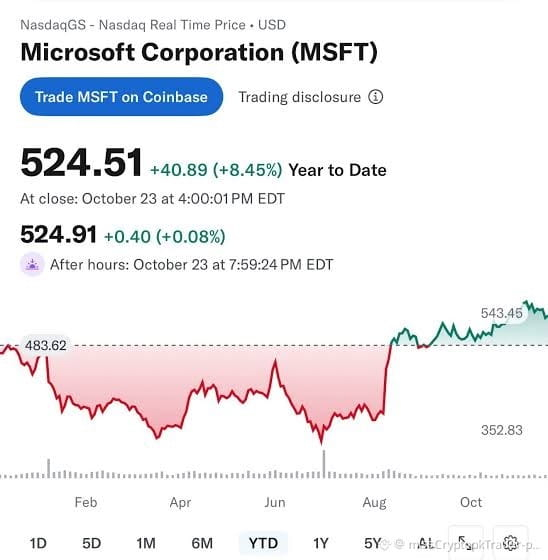
🚨 MSFT YTD +8.45% 🚀 Can Microsoft Deliver On AI? Earnings Oct 28!
At Close: $524.51 (+$40.89 YTD) | After hours $524.91
YTD low 483.62 -> Now 543.46 peak
Azure 45% guidance, $50B+ CapEx, Copilot 30M seats
Consensus EPS $4.71, Rev $90.6B
#CanMicrosoftDeliverOnAI #Microsoft #Azure #earnings $GOOGLB $MSFT $GOOGL
2
732

·
--
Bullish
Microsoft's quarterly revenue was $92.3 billion, up 19% year over year; Azure grew 48%, and Microsoft Cloud revenue reached $63.9 billion, while commercial contract backlog rose further to $677 billion.
On the other hand, Windows OEM and devices revenue plunged 22%, and Xbox content revenue also declined 2%. Microsoft has proven that AI can make money, but it increasingly looks like an infrastructure company selling computing power—if its consumer business continues to shrink, is this a successful transformation, or is it deliberately abandoning its core business?
$MSFTB #微软财报能否兑现AI红利 #Azure #美股财报 #Aİ
{spot}(MSFTBUSDT)
Microsoft's quarterly revenue was $92.3 billion, up 19% year over year; Azure grew 48%, and Microsoft Cloud revenue reached $63.9 billion, while commercial contract backlog rose further to $677 billion.
On the other hand, Windows OEM and devices revenue plunged 22%, and Xbox content revenue also declined 2%. Microsoft has proven that AI can make money, but it increasingly looks like an infrastructure company selling computing power—if its consumer business continues to shrink, is this a successful transformation, or is it deliberately abandoning its core business?
$MSFTB #微软财报能否兑现AI红利 #Azure #美股财报 #Aİ
王小神:
微软云和Azure增速很亮,但消费端在掉。市场现在更在意这门算力生意能不能持续兑现。
2
1
273
·
--
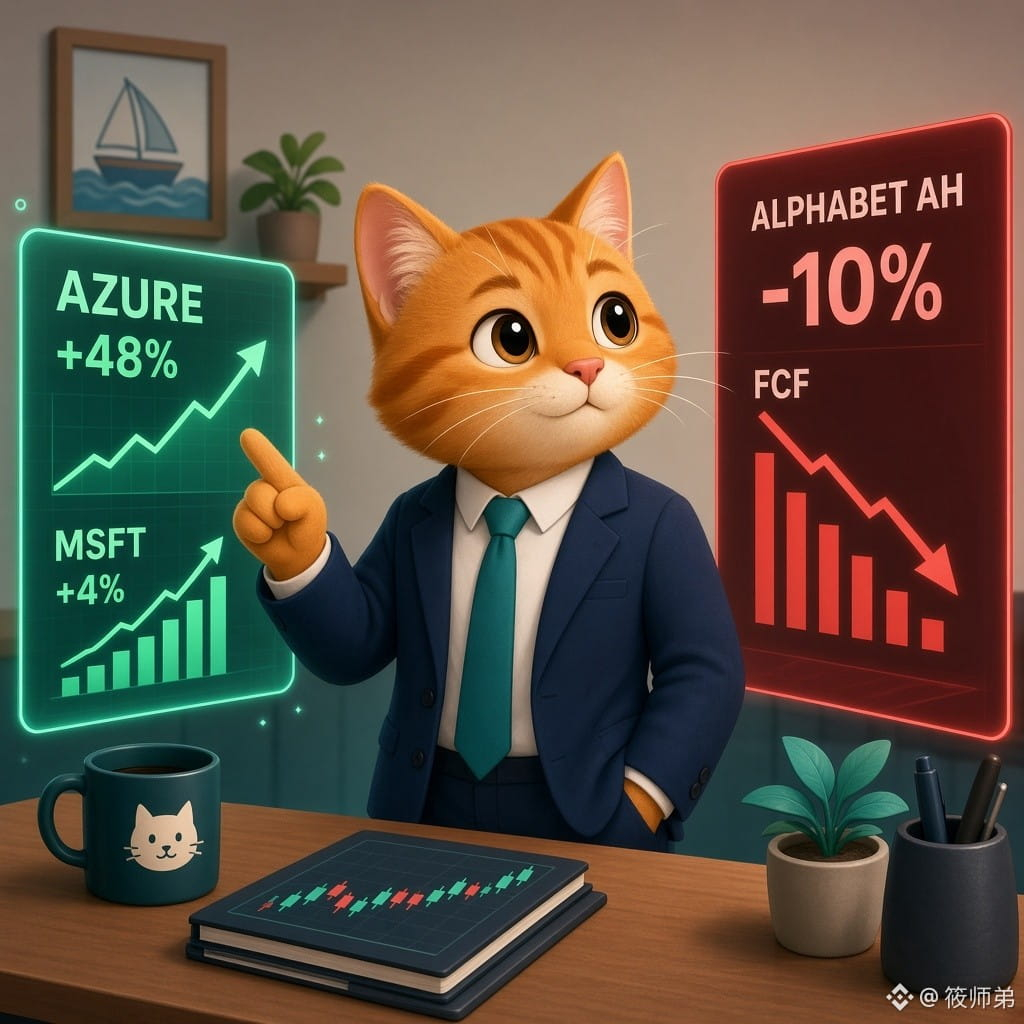
Microsoft’s report card: Azure grew 48%The same evening, two giants, two very different reactions.
Microsoft’s shares rose several percentage points after hours.
The numbers are rock-solid: earnings per share of $4.89 and revenue of $90.28 billion, up 19% year over year—both beat expectations. The biggest story, Azure, grew 48%, with quarterly revenue topping $33 billion.
To grow at nearly 50% at that scale is, honestly, pretty wild.
Of course, it’s also spending money like crazy. Quarterly capital expenditures topped $45 billion, up 30% year over year. Free cash flow also fell 27%, to around $18.6 billion.
So why isn’t the market giving it a hard time?
Because investors can see how that spending will pay off. Azure’s growth is the proof. Investors can accept earning a little less today, as long as tomorrow’s revenue growth is already taking shape.
Microsoft’s report card: Azure grew 48%
The same evening, two giants, two very different reactions.
Microsoft’s shares rose several percentage points after hours.
The numbers are rock-solid: earnings per share of $4.89 and revenue of $90.28 billion, up 19% year over year—both beat expectations. The biggest story, Azure, grew 48%, with quarterly revenue topping $33 billion.
To grow at nearly 50% at that scale is, honestly, pretty wild.
Of course, it’s also spending money like crazy. Quarterly capital expenditures topped $45 billion, up 30% year over year. Free cash flow also fell 27%, to around $18.6 billion.
So why isn’t the market giving it a hard time?
Because investors can see how that spending will pay off. Azure’s growth is the proof. Investors can accept earning a little less today, as long as tomorrow’s revenue growth is already taking shape.
27

·
--
Microsoft earnings beat expectations: Azure surges 48%, shares rise about 4% after hours
According to Microsoft and CNBC/Reuters: FY27 Q1 revenue was $92.3 billion, up 19% (versus expectations of about $90.7 billion); adjusted EPS was $4.89, beating the $4.73 estimate. Azure revenue was $33.17 billion, up 48%, and was disclosed in dollars for the first time, making it Microsoft's largest individual business. Microsoft Cloud revenue was $63.9 billion, up 30%. Commercial RPO rose 73% to $677 billion. Q2 revenue guidance is $96.0–$97.1 billion, with Azure growth of about 49%–50% in constant currency. Capital expenditures and finance leases totaled $45.2 billion (below expectations of about $50.7 billion). FCF remained positive but fell 27% year over year to $18.6 billion. By comparison, Alphabet fell more than 10% after hours, with FCF at about -$9.1 billion.
【View】
Both companies are pouring money into AI computing power, but Microsoft countered concerns about AI spending with Azure's growth and still-positive free cash flow. Alphabet, meanwhile, was weighed down by a revenue miss and cash flow. The hyperscale cloud providers are beginning to diverge: those that can prove capex is turning into revenue may be revalued.
【Opportunities/Risks】
Watch whether Azure meets its guidance, whether capex accelerates in Q2, and whether third-party capacity is delayed; how the computing-power supply chain is pricing the view that demand still exceeds supply; and how shifts in risk appetite around diverging AI narratives affect $BTC. Risks include continued pressure on FCF and renewed valuation pressure as debt financing expands.
Microsoft is using Azure's growth to show that its AI investment is being monetized. Do you have more confidence in cloud providers or chip stocks?
#微软财报 #Azure #AI基建 $BTC $RENDER
For reference only; this is not investment advice.
Microsoft earnings beat expectations: Azure surges 48%, shares rise about 4% after hours
According to Microsoft and CNBC/Reuters: FY27 Q1 revenue was $92.3 billion, up 19% (versus expectations of about $90.7 billion); adjusted EPS was $4.89, beating the $4.73 estimate. Azure revenue was $33.17 billion, up 48%, and was disclosed in dollars for the first time, making it Microsoft's largest individual business. Microsoft Cloud revenue was $63.9 billion, up 30%. Commercial RPO rose 73% to $677 billion. Q2 revenue guidance is $96.0–$97.1 billion, with Azure growth of about 49%–50% in constant currency. Capital expenditures and finance leases totaled $45.2 billion (below expectations of about $50.7 billion). FCF remained positive but fell 27% year over year to $18.6 billion. By comparison, Alphabet fell more than 10% after hours, with FCF at about -$9.1 billion.
【View】
Both companies are pouring money into AI computing power, but Microsoft countered concerns about AI spending with Azure's growth and still-positive free cash flow. Alphabet, meanwhile, was weighed down by a revenue miss and cash flow. The hyperscale cloud providers are beginning to diverge: those that can prove capex is turning into revenue may be revalued.
【Opportunities/Risks】
Watch whether Azure meets its guidance, whether capex accelerates in Q2, and whether third-party capacity is delayed; how the computing-power supply chain is pricing the view that demand still exceeds supply; and how shifts in risk appetite around diverging AI narratives affect $BTC . Risks include continued pressure on FCF and renewed valuation pressure as debt financing expands.
Microsoft is using Azure's growth to show that its AI investment is being monetized. Do you have more confidence in cloud providers or chip stocks?
#微软财报 #Azure #AI基建 $BTC $RENDER
For reference only; this is not investment advice.
·
--
#CanMicrosoftDeliverOnAI CanMicrosoftDeliverOnAI? 🤖📈
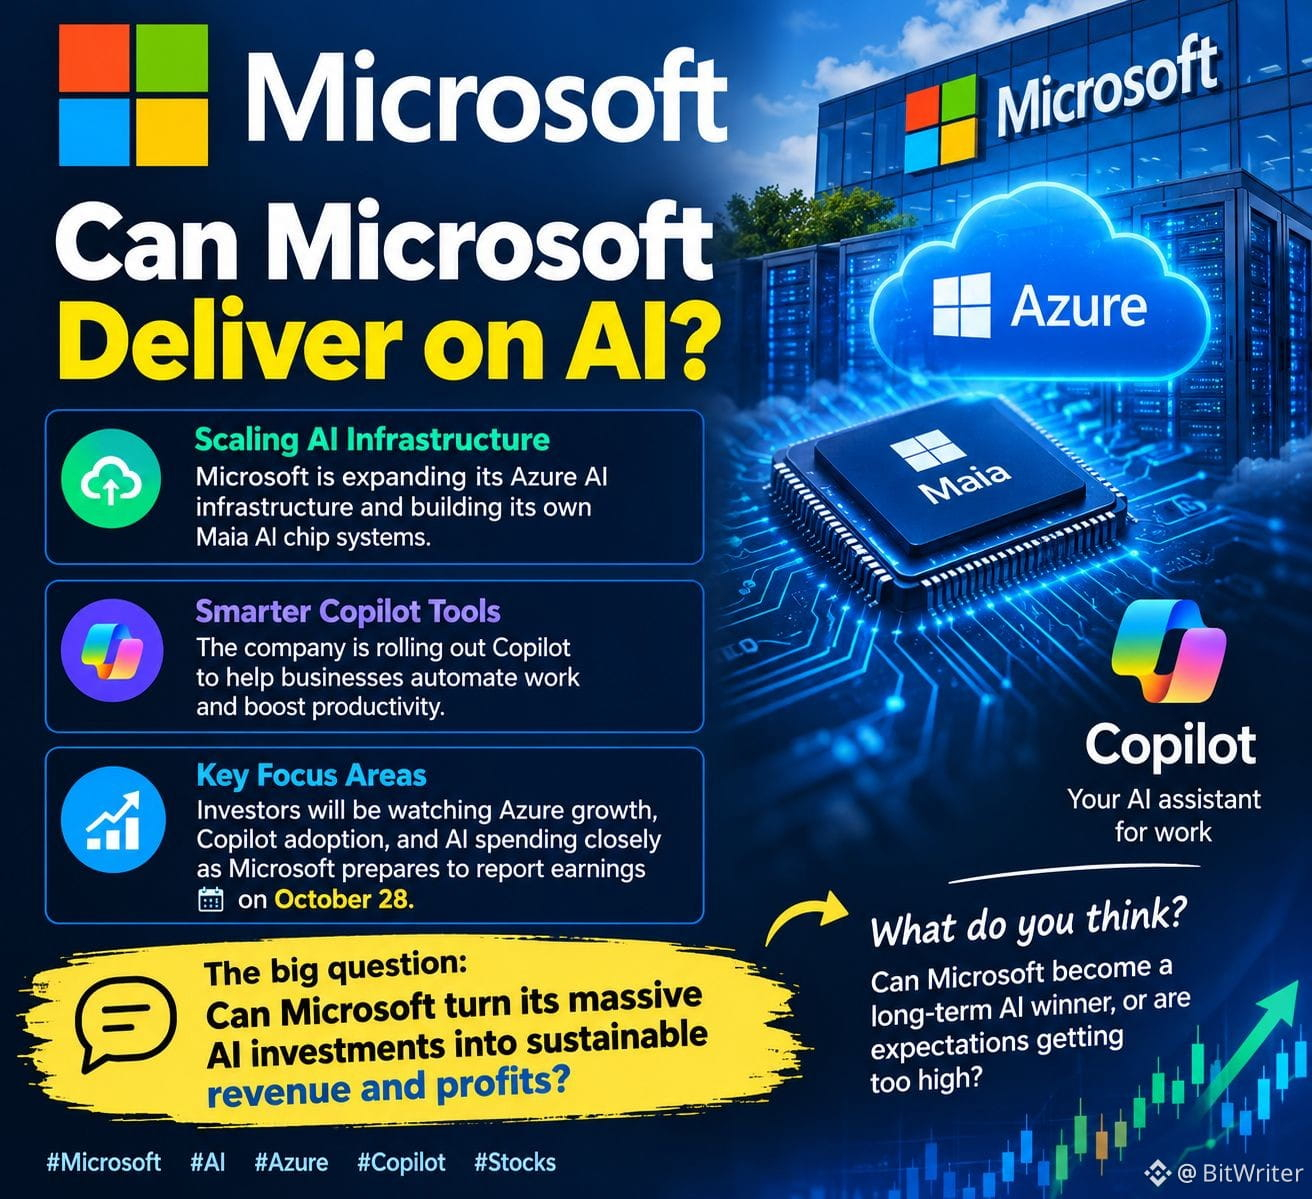
Microsoft is doubling down on AI, expanding its Azure AI infrastructure and developing smarter Copilot tools to help businesses automate work. Its latest plans include scaling its own Maia AI chip systems.
🚨 The big question: Can Microsoft turn its massive AI investments into sustainable revenue and profits?
Investors will be watching Azure growth, Copilot adoption, and AI spending closely as Microsoft prepares to report earnings on October 28.
💬 What do you think? Can Microsoft become a long-term AI winner, or are expectations getting too high?
#Microsoft #AI #Azure
1
31
Verified
#canmicrosoftdeliveronai
🚨 Microsoft Faces a $50 Billion AI Spending Test: Can Azure Deliver the Profits Wall Street Demands?
Microsoft ($MSFT ) reports its quarterly earnings on October 28, and investors are preparing for one of the biggest tests of the artificial intelligence boom.
The company is expected to generate approximately $90.6 billion in quarterly revenue, with earnings per share near $4.71. But the real focus will be Azure, Microsoft's cloud platform, which powers businesses and AI applications worldwide.
📊 Three numbers investors will watch:
• $90.6 billion: Expected quarterly revenue.
• 45%: Azure's expected year-over-year growth in constant currency, according to management's previous guidance.
• More than $50 billion: Microsoft's expected quarterly capital expenditure, including the impact of lease reclassifications.
⚠️ The challenge is becoming increasingly clear. AI demand is booming, but data centers, advanced chips and computing infrastructure are extremely expensive.
Investors want evidence that Azure growth and paid adoption of Copilot can generate enough additional revenue and cash flow to justify these investments.
Microsoft will also provide more detail on Azure's revenue in dollars under its new reporting structure, giving the market a clearer view of its cloud business.
The key question is no longer simply whether AI is growing. It's whether Microsoft can turn that growth into sustainable profits without sacrificing margins.
#Microsoft #Azure #artificialintelligence
The _Trading _Geek:
🔥 Great Post! 📈 Join my “CHAT ROOM” 📌 for FREE Trading Insights, LONG & SHORT Setups, and Market Updates 🎯🚀 Find it pinned at the top of my "PROFILE "👑 Tap “JOIN NOW” and stay connected with the community for upcoming market opportunities! ⚡Hope To See You There Bro !😇👇
Click Here To Join "CHAT ROOM"
1
1
7
6.9k
·
--
Microsoft’s AI Bet: Is the Return Worth the Cost?
Microsoft reports its Q1 FY2027 earnings on October 28, and one question stands out: can AI revenue keep pace with the cost of building the infrastructure behind it?
Here’s what I’m watching:
🔹 Azure growth: Analysts expect strong cloud demand, with growth forecasts around 45% in constant currency.
🔹 Capital spending: Microsoft expects quarterly capital expenditure to exceed $50 billion as it expands its AI infrastructure.
🔹 Cash flow and returns: Revenue growth matters, but investors also need evidence that these investments can generate sustainable financial returns.
My view: Microsoft appears well positioned to benefit from growing AI demand, but execution will be crucial. Strong revenue alone may not be enough if spending rises faster than the returns it generates.
The earnings report will be an important test of whether AI demand is translating into durable business value.
What matters more to you: faster Azure growth or stronger returns on Microsoft’s AI investments?
$MSFT
#Microsoft #Aİ #Azure #EarningsSeason
1
16
·
--
#CanMicrosoftDeliverOnAI
Everyone is talking AI capex, but Microsoft is actually SHOWING revenue.
The Bull Case:
✅ Azure crossed $100 Billion annual revenue (+41% YoY) - First time ever
✅ Copilot now 30M+ paid seats - enterprise adoption is real, not hype
✅ Q4 FY26: $90B sales, $35.8B profit (+31%) - AI is already profitable
✅ Earnings Oct 28 - Consensus: $90.75B revenue, Azure growth 44-47% expected
The Bear Case:
⚠️ CapEx insane: $41B last quarter, expecting $50B+ next quarter
⚠️ ∼50% of Azure AI growth is just from OpenAI - concentration risk
⚠️ FCF expected to drop from $67B to $14.3B by 2028 due to AI buildout 2a69be3538f8
Wall Street is asking one question: Can cloud growth justify $175B+ infra spend in 2026?
My take: Microsoft is the ONLY Big Tech proving AI ROI right now. If Azure prints 46%+ growth tomorrow, it lifts entire AI market - including crypto AI tokens.
What's your bet? Will MSFT beat or miss?
#CanMicrosoftDeliverOnAI #MSFT #AI #Azure #Crypto #Binance
1
88
·
--
Verified
#微软财报能否兑现ai红利
$678 billion in orders are piling up at the door, but Microsoft needs to “build the door” before it can collect
The strongest evidence of Microsoft’s AI windfall isn’t in its income statement, but in a figure many people overlook: commercial remaining performance obligations (RPO).
At the end of last quarter, Microsoft’s RPO reached $678 billion, up 84% year over year and approximately $51 billion from the previous quarter. More importantly, the company explicitly said that all of the quarter-over-quarter increase in RPO this quarter came from customers outside the leading U.S. foundation model providers. This means order growth is no longer driven primarily by a handful of mega-customers such as OpenAI. Cloud migration, data platform upgrades, model inference, and agent applications at traditional enterprises are becoming new sources of demand.
But RPO is not revenue. It is money “under contract but not yet delivered.” Microsoft needs to build out its computing capacity before it can convert these orders into revenue. The company is adding data center capacity at a rate of about 1 gigawatt per quarter, with the goal of doubling its overall computing capacity within two years. Bank of America points out that Azure’s growth is converting its $678 billion backlog into revenue.
The ultimate answer to whether the “AI windfall” will materialize lies in the race between “capacity delivery speed” and “order conversion pace.” If Azure’s 47.7% growth rate this quarter comes through, it would show that the race is progressing as planned. If growth falls short of guidance because of capacity constraints, then those $678 billion in orders will be nothing more than a placebo on the books.
$MSFT #RPO #OrderBacklog #CapacityConstraints #Azure
风中浪客:
6780亿刀……先看能不能收到钱吧
1
1
6.7k
·
--
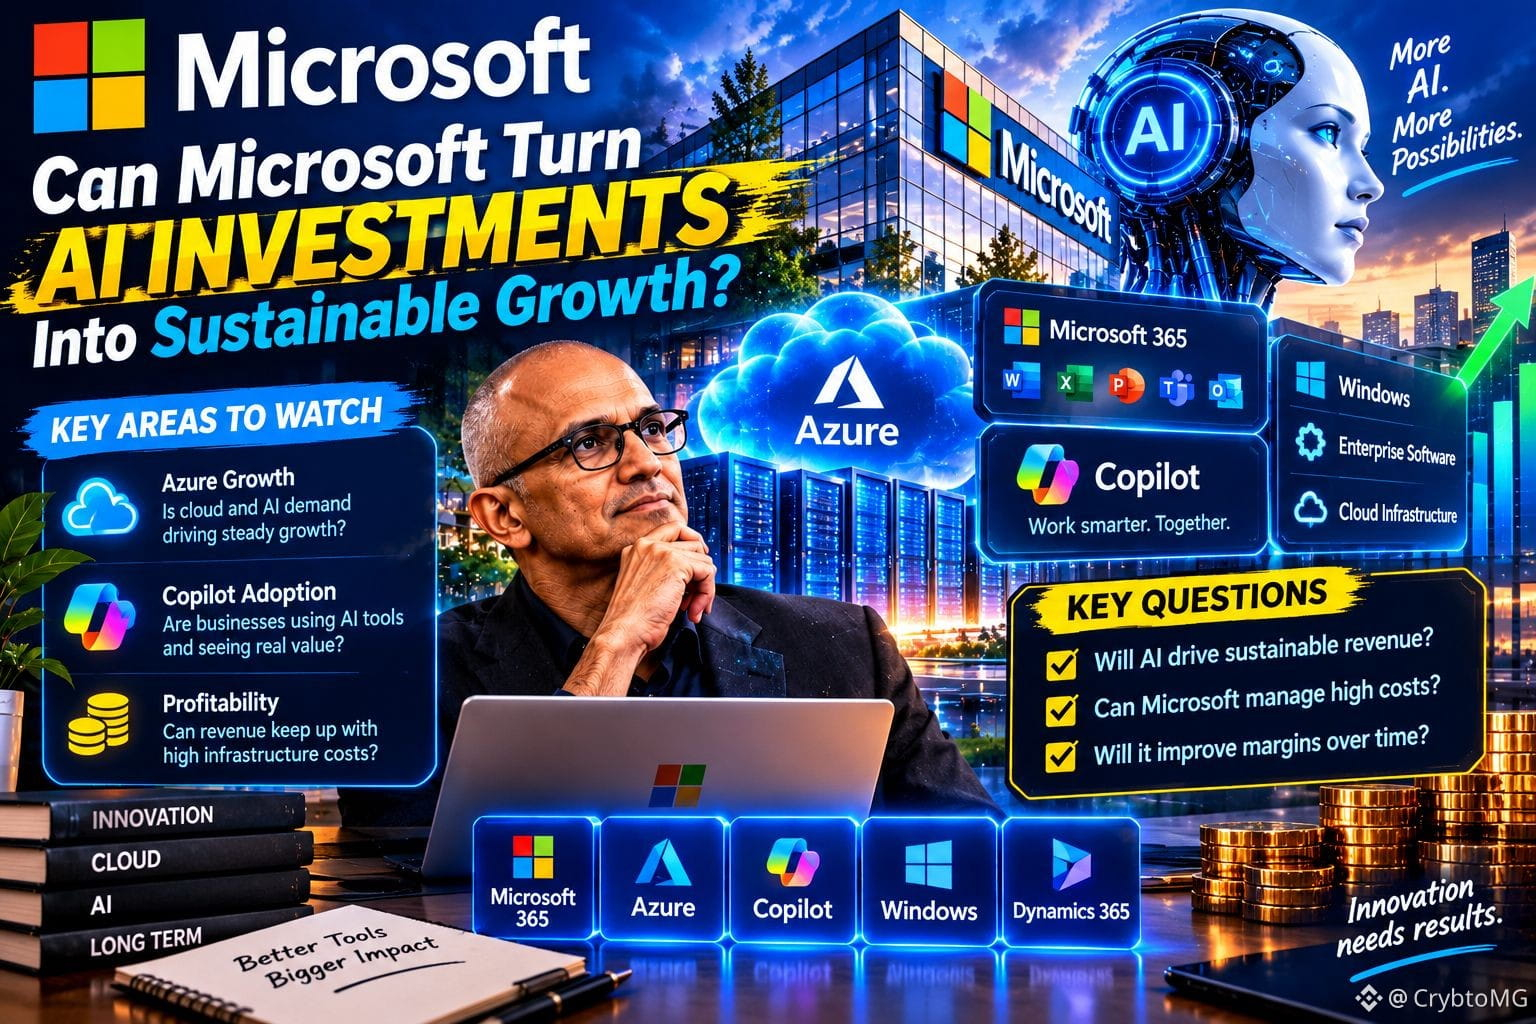
Microsoft AI: Can Heavy Investment Create Sustainable Growth?
Building AI infrastructure is expensive. Turning it into a profitable business is the real challenge.
Microsoft has an advantage: it already serves businesses through Microsoft 365, Azure, Windows, and enterprise software. This gives the company several ways to bring AI tools to existing customers.
But distribution alone isn’t enough.
For its AI strategy to deliver lasting value, three things matter:
☁️ Azure growth: Is demand for AI computing translating into sustained cloud revenue?
🤖 Copilot adoption: Are businesses using AI tools regularly and seeing measurable productivity gains?
📊 Profitability: Can AI-related revenue grow enough to justify spending on data centers, chips, energy, and model development?
The key distinction is between getting businesses interested in AI and building products they are willing to pay for over the long term.
Microsoft doesn’t need to win every AI competition. It needs to make its AI products useful, widely adopted, and economically sustainable.
What will matter most in the long run: Microsoft’s existing customer base or its ability to control AI infrastructure costs?
#Microsoft #MicrosoftAI #Aİ #Azure
1
2
·
--
Microsoft’s AI Strategy: Can Big Investments Deliver Real Results?
Microsoft is investing billions in AI, but the real challenge is turning that spending into sustainable business growth.
☁️ The opportunity: Growing demand for cloud computing and wider AI adoption could support Microsoft’s long-term business.
⚠️ The risks: Competition is intense, infrastructure costs are high, and it may take time for these investments to generate meaningful returns.
For me, the key question isn’t just how much Microsoft spends on AI. It’s whether that investment creates lasting value for the business.
What matters most to you when evaluating Microsoft’s AI strategy: Azure growth, AI adoption, or profitability?
#Microsoft #MSFT #Aİ #Azure
1
2
·
--
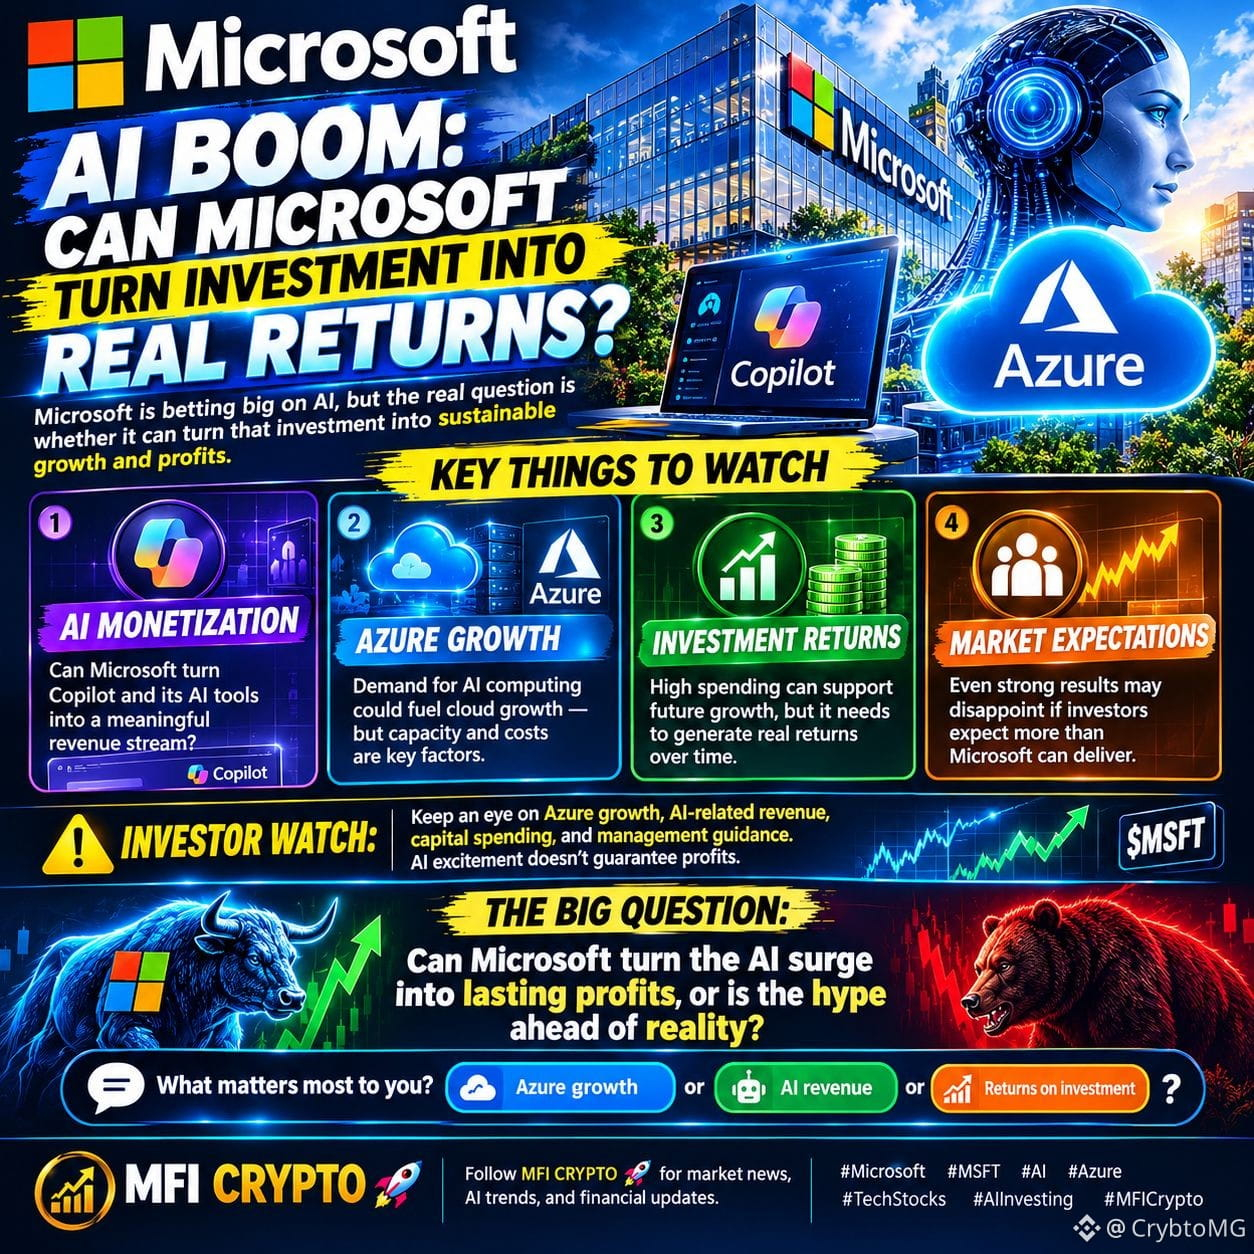
Microsoft’s AI Challenge: Turning Investment Into Long-Term Value
Microsoft ($MSFT) is investing heavily in AI, but the key question is how effectively it can turn that spending into sustainable business growth.
Here are three things worth watching:
☁️ Azure growth: Is demand for AI computing translating into continued cloud growth?
🤖 AI monetization: Are Copilot and other AI tools creating meaningful revenue for Microsoft?
📊 Investment returns: Can revenue and productivity gains justify the cost of building and running AI infrastructure?
Strong demand alone doesn’t tell the whole story. Investors also need to consider capacity constraints, operating costs, and management’s outlook.
The bigger question isn’t simply whether AI adoption will grow. It’s whether Microsoft can turn that adoption into durable financial results.
What matters most when evaluating Microsoft’s AI strategy: Azure growth, AI revenue, or returns on investment?
#Microsoft #Aİ #Azure #Tech
1
8
·
--
Bearish
🔥 $MSFT - MICROSOFT FLIES TO 500! WHAT'S NEXT FOR THE TECH GIANT? 🔥
Microsoft hit a massive 499.32 on the Azure rally and is now resting at 486.48. The bulls are completely in control!
QUESTION TO YOU:
❓ Will MSFT break 500 and rally to 520?
❓ Or will it get rejected and retest 470?
⚠️ Drop your prediction below!
✅ If you are BULLISH, comment "🖥️ MSFT BULL"!
🔻 If you are BEARISH, comment "📉 MSFT BEAR"!
The cloud wars are heating up! 👇
#MSFT #BinanceSquare #CryptoPoll #TechStocks #Azure
16
·
--
$MSFT — Cloud Growth Still Matters
While parts of the technology sector came under pressure, Microsoft stood out with strong cloud results. Reported Azure revenue grew 48%, helping demonstrate that AI-related demand can support real business growth.
But strong fundamentals do not automatically mean the stock must rise tomorrow.
Trading bias: LONG on a confirmed breakout.
My checklist:
- Price breaks above the latest confirmed resistance.
- Volume expands with the move.
- The breakout level holds on a retest.
- The broader Nasdaq environment does not deteriorate sharply.
Invalidation: A failed breakout followed by a close back below the reclaimed level.
I prefer buying confirmed strength rather than assuming every strong earnings report creates an immediate rally.
#Microsoft #MSFT #Azure #AIStocksWhatNew #stockmarket
37
·
--
Bullish
🚀 #CanMicrosoftDeliverOnAI?
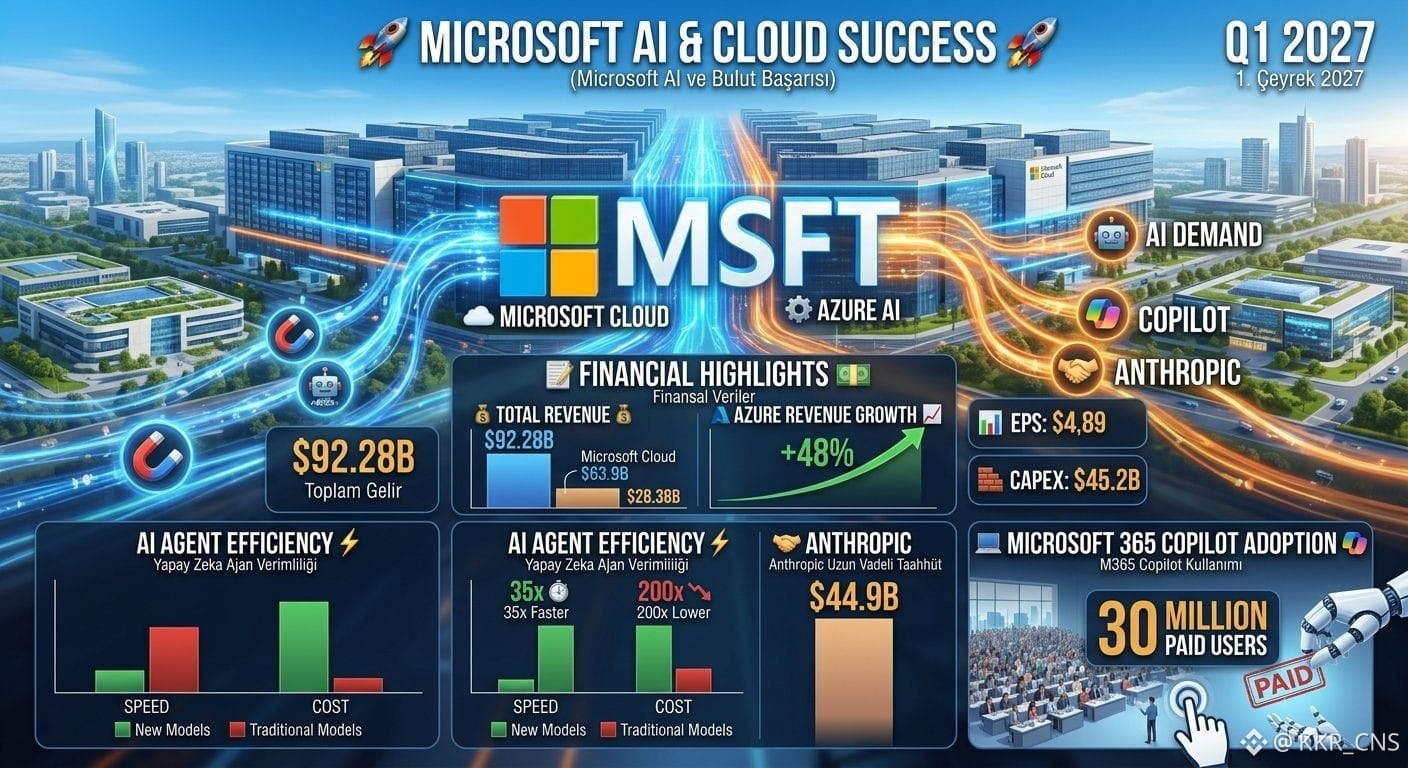
$MSFTB IS TURNING AI INVESTMENTS INTO GROWTH! 🤖📈
Microsoft is making a major move in the AI race—but can it turn massive infrastructure spending into sustainable long-term profits?
🔥 Key Highlights:
💰 $92.28B in total revenue
☁️ $63.9B in Microsoft Cloud revenue, up 30%
⚡ 48% growth in Azure, fueled by AI demand
📊 $4.89 EPS, beating market expectations
🏗️ $45.2B in CapEx invested in infrastructure
🤖 AI-powered efficiency gains could further improve productivity and reduce operating costs.
🎯 The Big Question: Can Microsoft maintain its AI momentum, monetize enterprise demand, and deliver sustainable returns on its massive investments?
AI is no longer just a futuristic concept—it's becoming a serious business opportunity. But execution, competition, and infrastructure costs will determine the winners.
💬 What’s your outlook for $MSFT?
📈 More upside ahead, or are expectations getting too high?
👇 Share your thoughts!
$MSFT $SNXX $XPIN
{spot}(MSFTBUSDT)
{etf_us}(SNXX.ETF)
{alpha}(560xd955c9ba56fb1ab30e34766e252a97ccce3d31a6)
#Microsoft #AI #Azure #ArtificialIntelligence
🚀 #CanMicrosoftDeliverOnAI?
$MSFTB IS TURNING AI INVESTMENTS INTO GROWTH! 🤖📈
Microsoft is making a major move in the AI race—but can it turn massive infrastructure spending into sustainable long-term profits?
🔥 Key Highlights:
💰 $92.28B in total revenue
☁️ $63.9B in Microsoft Cloud revenue, up 30%
⚡ 48% growth in Azure, fueled by AI demand
📊 $4.89 EPS, beating market expectations
🏗️ $45.2B in CapEx invested in infrastructure
🤖 AI-powered efficiency gains could further improve productivity and reduce operating costs.
🎯 The Big Question: Can Microsoft maintain its AI momentum, monetize enterprise demand, and deliver sustainable returns on its massive investments?
AI is no longer just a futuristic concept—it's becoming a serious business opportunity. But execution, competition, and infrastructure costs will determine the winners.
💬 What’s your outlook for $MSFT?
📈 More upside ahead, or are expectations getting too high?
👇 Share your thoughts!
$MSFT $SNXX $XPIN
#Microsoft #AI #Azure #ArtificialIntelligence
20
·
--
Bullish
🚀 #CanMicrosoftDeliverOnAI ?
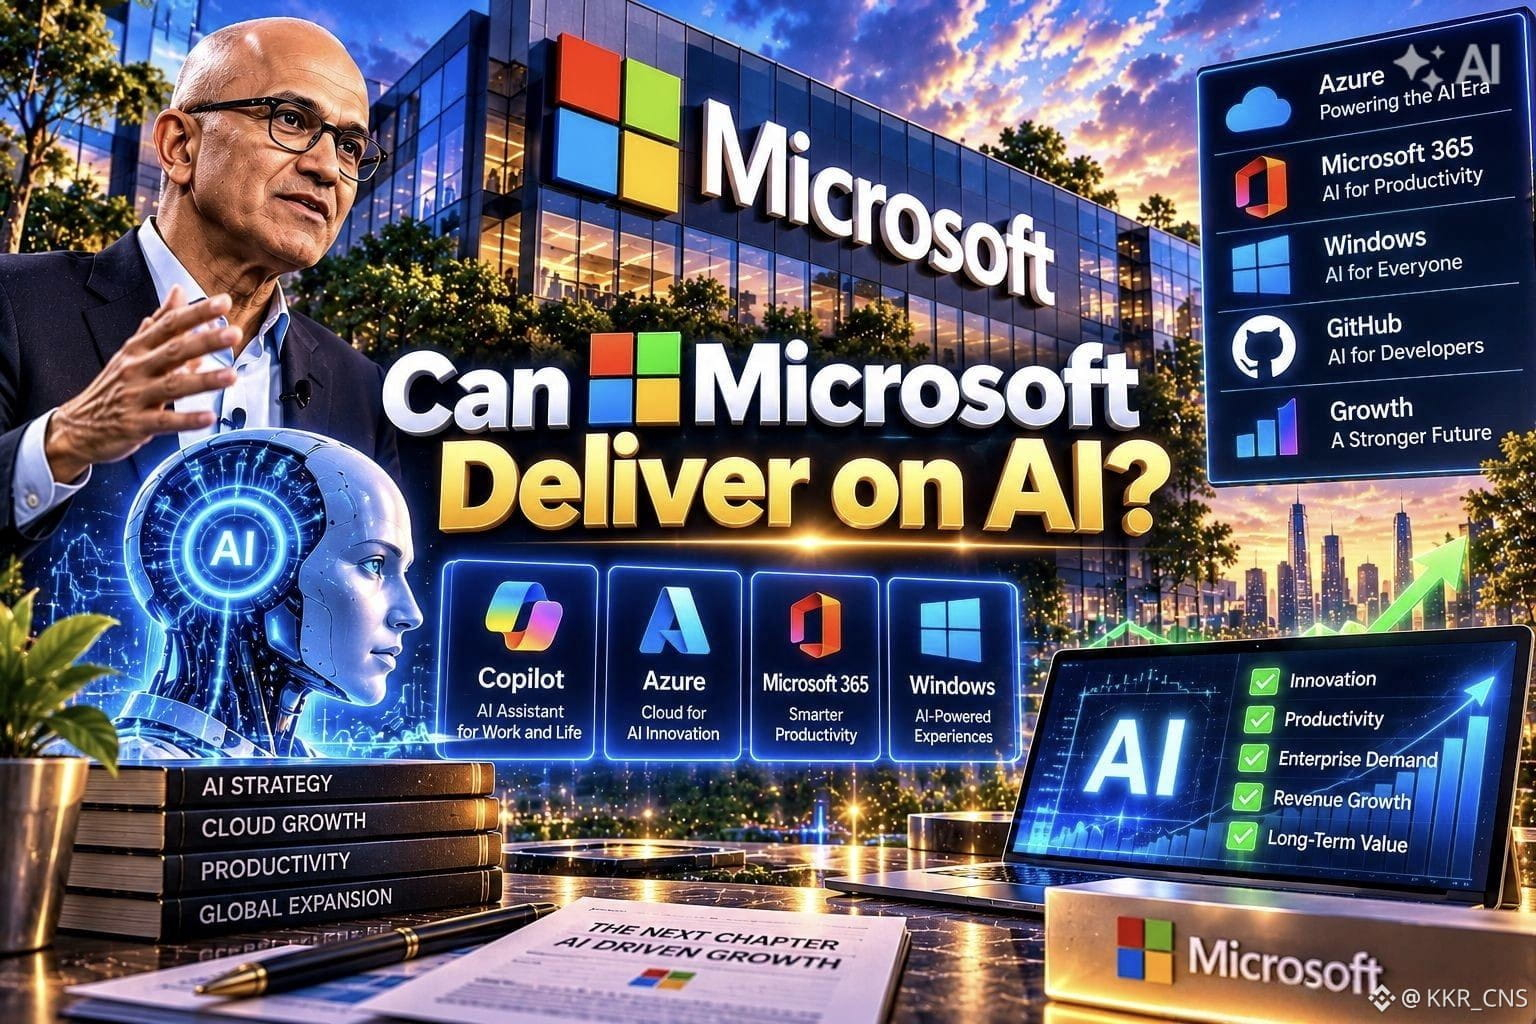
🤖 MICROSOFT'S AI REVOLUTION: THE NEXT BIG GROWTH OPPORTUNITY?
Microsoft is integrating AI across its ecosystem, from Azure and Copilot to Microsoft 365, Windows, and GitHub. The goal is clear: make AI an essential part of business productivity and digital transformation.
📊 WHAT COULD DRIVE GROWTH?
🔹 Azure: Growing demand for cloud computing and AI infrastructure.
🔹 Copilot: Bringing AI-powered assistance into everyday workflows.
🔹 Microsoft 365: Enhancing productivity through intelligent tools.
🔹 GitHub: Helping developers build software more efficiently.
🔹 Enterprise AI: Turning business adoption into recurring revenue.
💰 THE BIG CHALLENGE
Massive AI investments create enormous opportunities, but infrastructure costs, profit margins, and customer demand will determine whether that spending delivers sustainable returns.
₿ WHY IT MATTERS TO CRYPTO
Strong technology earnings could support broader risk appetite, while disappointing results or rising costs could weigh on market sentiment. However, crypto prices will also depend on liquidity, interest rates, and Bitcoin's own market structure.
🎯 MY TAKE: AI hype can attract attention, but long-term success depends on measurable revenue, profitability, and real-world adoption.
🔥 What do you think? Can Microsoft turn its AI investments into lasting growth, or are market expectations getting too high?
👇 Share your views!
{spot}(MSFTBUSDT)
{spot}(GOOGLBUSDT)
{spot}(METABUSDT)
#Microsoft #MSFT #AI #Azure #Copilot #CryptoMarket #Bitcoin #TechStocks #MarketAnalysis
🚀 #CanMicrosoftDeliverOnAI ?
🤖 MICROSOFT'S AI REVOLUTION: THE NEXT BIG GROWTH OPPORTUNITY?
Microsoft is integrating AI across its ecosystem, from Azure and Copilot to Microsoft 365, Windows, and GitHub. The goal is clear: make AI an essential part of business productivity and digital transformation.
📊 WHAT COULD DRIVE GROWTH?
🔹 Azure: Growing demand for cloud computing and AI infrastructure.
🔹 Copilot: Bringing AI-powered assistance into everyday workflows.
🔹 Microsoft 365: Enhancing productivity through intelligent tools.
🔹 GitHub: Helping developers build software more efficiently.
🔹 Enterprise AI: Turning business adoption into recurring revenue.
💰 THE BIG CHALLENGE
Massive AI investments create enormous opportunities, but infrastructure costs, profit margins, and customer demand will determine whether that spending delivers sustainable returns.
₿ WHY IT MATTERS TO CRYPTO
Strong technology earnings could support broader risk appetite, while disappointing results or rising costs could weigh on market sentiment. However, crypto prices will also depend on liquidity, interest rates, and Bitcoin's own market structure.
🎯 MY TAKE: AI hype can attract attention, but long-term success depends on measurable revenue, profitability, and real-world adoption.
🔥 What do you think? Can Microsoft turn its AI investments into lasting growth, or are market expectations getting too high?
👇 Share your views!
#Microsoft #MSFT #AI #Azure #Copilot #CryptoMarket #Bitcoin #TechStocks #MarketAnalysis
444
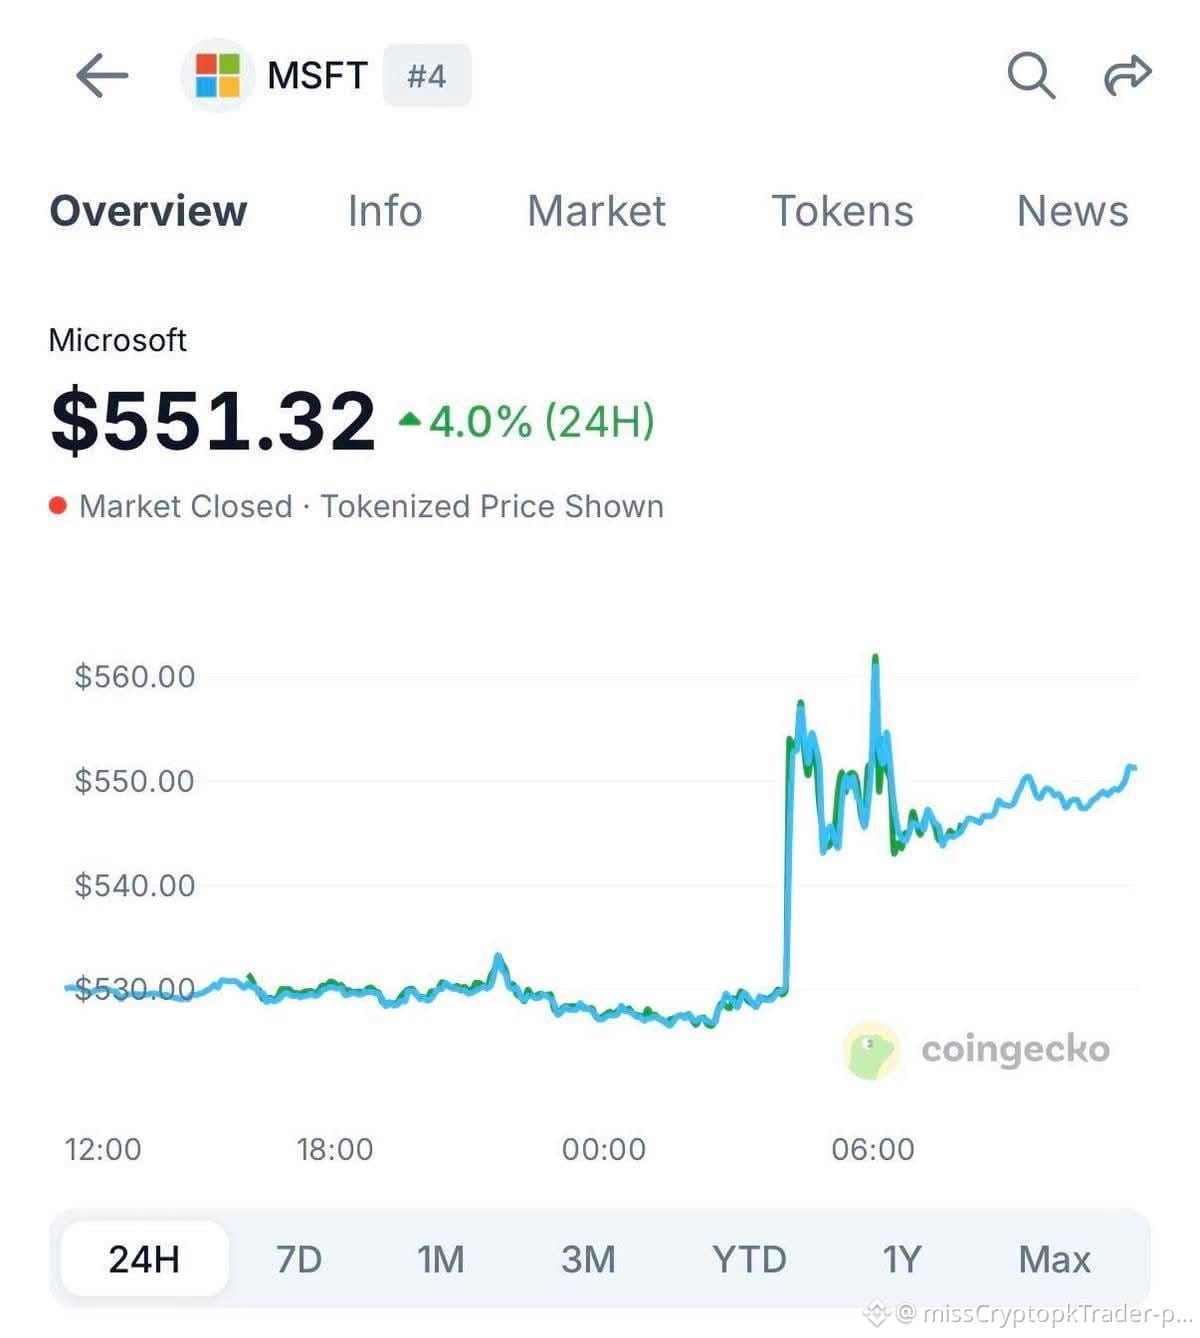
$MSFT is up 4% after fiscal Q1 earnings report 🚀
$551.32 ▲4.0% (24H)
The rally was driven by strong Azure and AI revenue growth, alongside upbeat Q2 guidance that eased concerns over AI spending.
#MSFT #Microsoft #Azure #AI #Earnings
{future}(MSFTUSDT)
$MSFT is up 4% after fiscal Q1 earnings report 🚀
$551.32 ▲4.0% (24H)
The rally was driven by strong Azure and AI revenue growth, alongside upbeat Q2 guidance that eased concerns over AI spending.
#MSFT #Microsoft #Azure #AI #Earnings
$551.32 ▲4.0% (24H)
The rally was driven by strong Azure and AI revenue growth, alongside upbeat Q2 guidance that eased concerns over AI spending.
#MSFT #Microsoft #Azure #AI #Earnings
47
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#FedWatch
16.4M views
39,835 Discussing
2
#EarningsSeason
6.5M views
32,533 Discussing
3
#USMidtermElections
67,265 views
835 Discussing
4
#StrategySTRCReaches$99.95ForFirstTimeIn165Days
63 views
4 Discussing
5
#BinanceWillListPredictPREDICT
1,961 views
103 Discussing
6
#SwitzerlandFirstSpotBitcoinETFExpectedToTradeInNovember
210 views
17 Discussing
7
#StrategyReports$21BQ3OperatingProfit
93 views
7 Discussing
8
#Strategy三季度营业利润210亿美元
8,505 views
38 Discussing
9
#TwoAddressesHoldingAbout1.28BUSDTFrozen
39 views
17 Discussing
10
#FirstDigitalBlacklistsAttackerAddressHoldingAbout3.4MFDUSD
66 views
5 Discussing