$TQQQB : TQQQB Activity Myth Check
Does $TQQQB need constant trading to matter? A hypothetical researcher assumes missing daily action means exclusion.
The shortcut
Watching a chart feels urgent. The watchlist stays calm while the mind rushes. This habit mistakes inaction for risk.
A careful view
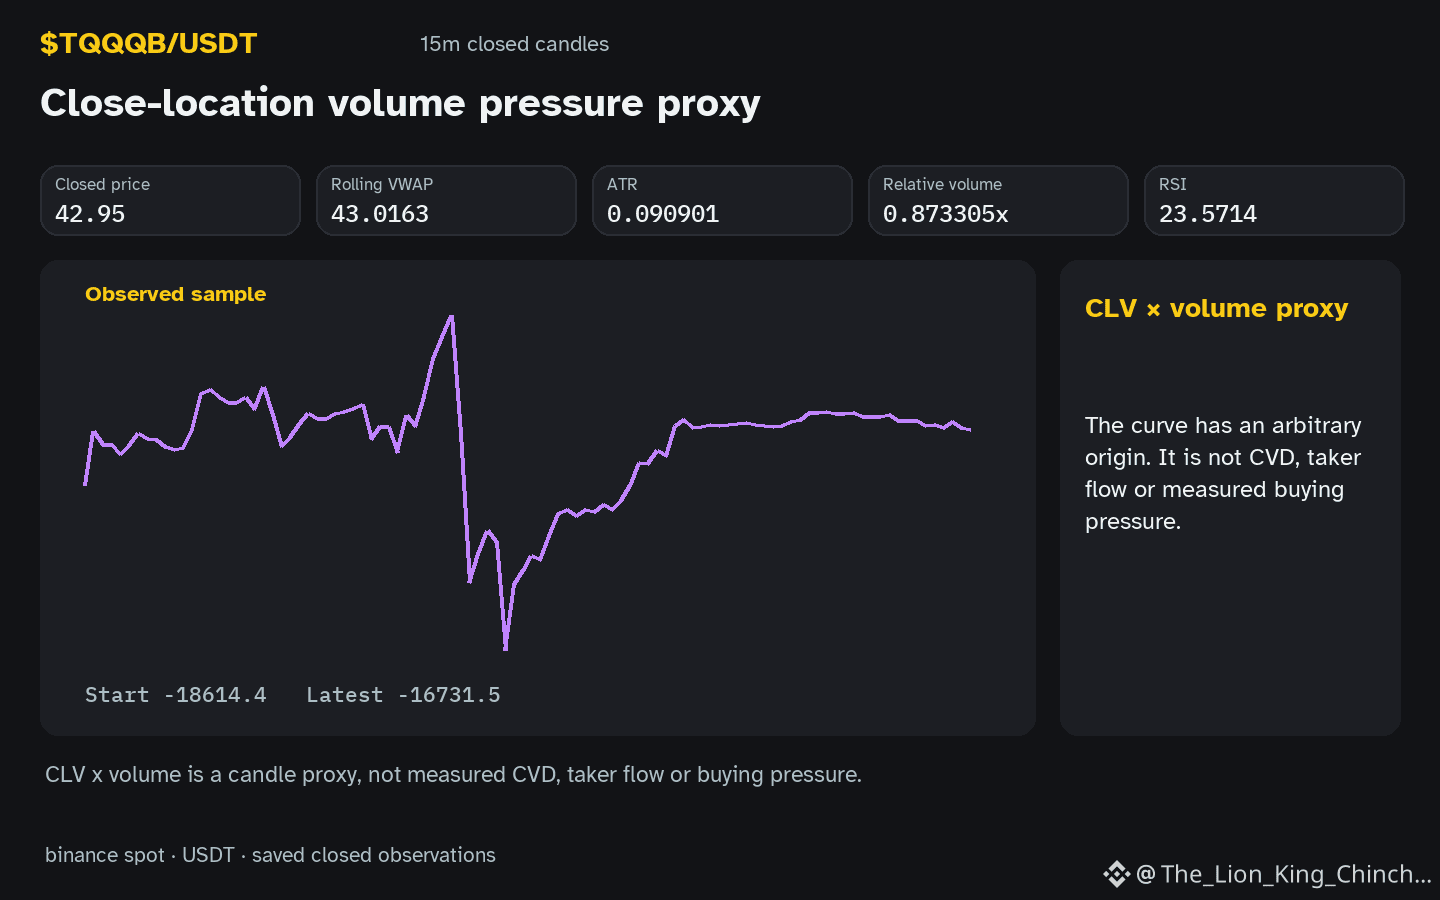
Saved data shows $TQQQB below support. The hourly direction is down. Relative volume is 0.87x baseline. These facts describe one specific moment. They do not prove that missing another day invalidates a method. Daily volatility is a natural feature of markets. It is not a participation requirement.
A useful observation
Consider a counterexample. A trader sets rules based on structure. They see a candle close outside expected bounds. They do not change the rule immediately. They wait for the next closed candle. If the new price respects the old support level, the original view holds. If it breaks further, the view is updated. This self-check separates observation from impulse.
Current data includes relative volume 0.87x baseline. This measures activity against prior candles. It does not measure intent or crowd behavior. Using it to judge daily participation is a category error. The right question is whether the price structure changed. Not whether enough trades happened to feel busy.
This framework applies to any asset. It avoids inventing narratives from limited data. It keeps the analysis grounded in what is actually visible. The lesson is simple. Let the data speak. Do not rush to fill silence with assumptions. 📝
Probabilistic market research, not a recommendation or guaranteed return.
#TQQQB #LearnCrypto
Does $TQQQB need constant trading to matter? A hypothetical researcher assumes missing daily action means exclusion.
The shortcut
Watching a chart feels urgent. The watchlist stays calm while the mind rushes. This habit mistakes inaction for risk.
A careful view
Saved data shows $TQQQB below support. The hourly direction is down. Relative volume is 0.87x baseline. These facts describe one specific moment. They do not prove that missing another day invalidates a method. Daily volatility is a natural feature of markets. It is not a participation requirement.
A useful observation
Consider a counterexample. A trader sets rules based on structure. They see a candle close outside expected bounds. They do not change the rule immediately. They wait for the next closed candle. If the new price respects the old support level, the original view holds. If it breaks further, the view is updated. This self-check separates observation from impulse.
Current data includes relative volume 0.87x baseline. This measures activity against prior candles. It does not measure intent or crowd behavior. Using it to judge daily participation is a category error. The right question is whether the price structure changed. Not whether enough trades happened to feel busy.
This framework applies to any asset. It avoids inventing narratives from limited data. It keeps the analysis grounded in what is actually visible. The lesson is simple. Let the data speak. Do not rush to fill silence with assumptions. 📝
Probabilistic market research, not a recommendation or guaranteed return.
#TQQQB #LearnCrypto