#NvidiaBeatsEstimatesWith$130BQ4Outlook
✅ Conclusion first: The hashtag is factually accurate but incomplete.Nvidia's Q3 FY27 revenue and Q4 guidance both exceeded Wall Street expectations, yet “beating estimates” and “solid fundamentals” are not the same thing 🎯. This earnings report occurred in a special context following Jensen Huang's resignation, SEC investigation, and a halt to China shipments, with several key risk factors that the hashtag conceals 🚩.
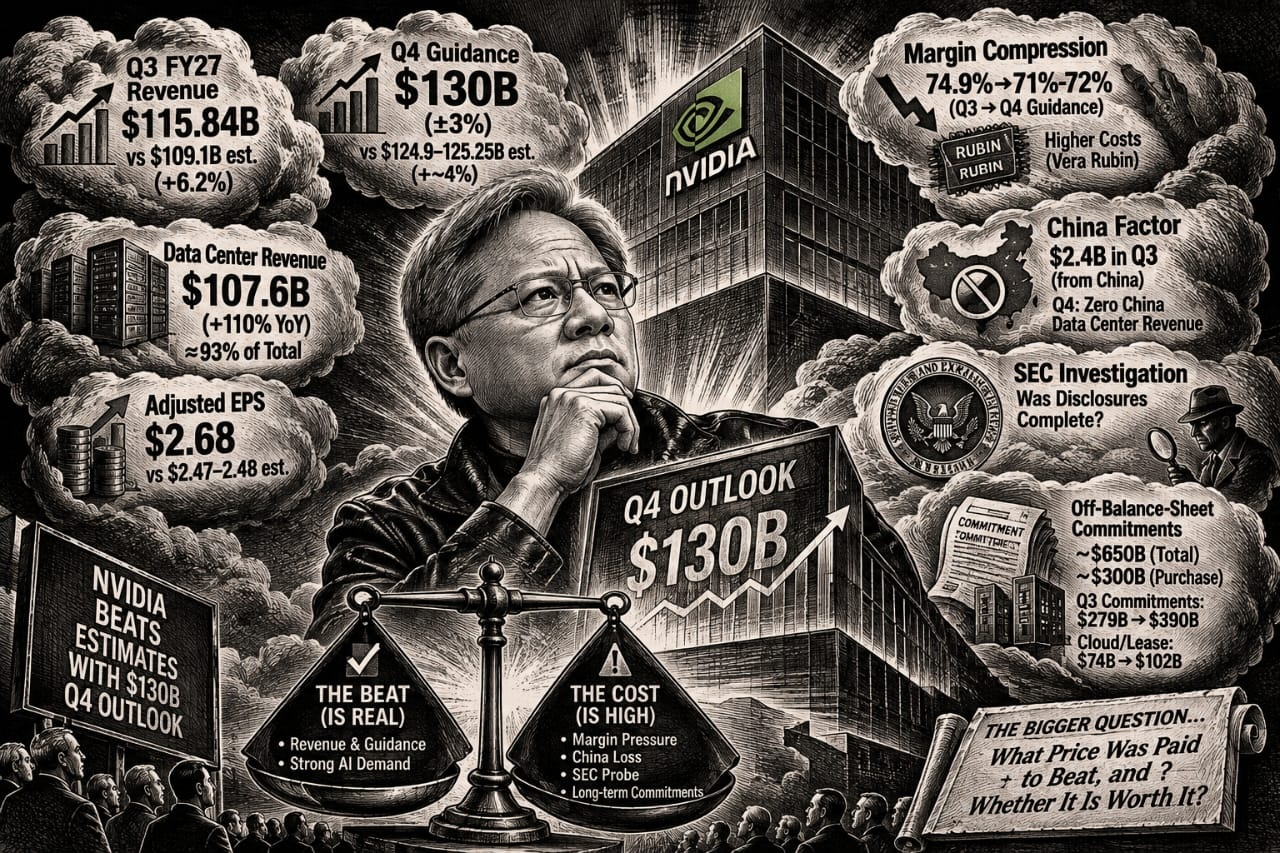
📊 Comparing with market expectations, the beats are real. Q3 revenue reached $115.84 billion, versus LSEG consensus of approximately $109.1 billion, a beat of roughly 6.2% 📈. Q4 revenue guidance of $130 billion (±3%), versus consensus of approximately $124.9–125.25 billion, exceeded expectations by roughly 4% 🚀. Data center revenue of $107.6 billion, up 110% year-over-year, accounted for approximately 93% of total revenue 💾. Adjusted EPS of $2.68 beat the $2.47–2.48 consensus 💰. These figures indicate that the core AI chip business has not stalled due to leadership turmoil, and short-term orders remain solid 💪.
⚠️ However, the cost hidden behind “beating estimates” is margin compression. Q3 adjusted gross margin was 74.9%, but Q4 guidance has been lowered to 71%–72% 📉. The reason given by management is that the Vera Rubin platform incurred higher initial costs, while existing orders were executed at old prices, and a new pricing system will not be introduced until next year 🔧. This means: the “beat” is volume-driven, not profitability-driven 📦. The company is sacrificing near-term margin to exchange for the smooth launch of the new platform 🔄.
🇨🇳 The China factor has been completely erased from guidance. Nvidia still recorded $2.4 billion in Hopper data center product revenue from China in Q3, but explicitly stated that Q4 guidance includes zero China data center compute revenue, and it has stopped shipping licensed Hopper products to China 🚫. This is not an active strategic choice, but rather a passive adjustment under export controls and geopolitical pressure 🌍. For a company whose data center business accounts for 93% of revenue, erasing an entire major market from guidance while still beating expectations demonstrates that demand from other regions is indeed strong enough, but it also means future growth has permanently lost a variable 🔮.
🔍 The SEC investigation is the biggest uncertainty that the hashtag does not reflect. The Wall Street Journal reported that the SEC has launched a civil investigation into whether Nvidia's disclosures misled investors, with the scope involving Jensen Huang's relationships and chip sales in Asia 🕵️. This investigation is not about accounting fraud, but about whether “what the company told investors” was complete and accurate 📋. Combined with the unusual circumstances of Jensen Huang's resignation, this creates a genuine crisis of confidence 😰. Interim CEO Colette Kress stated on the call that “momentum is real,” but this statement is insufficient to offset regulatory uncertainty 🎙️.
💼 The scale of off-balance-sheet commitments deserves attention. Institutional data shows that as of Q2, Nvidia had approximately $650 billion in off-balance-sheet commitments, of which roughly $300 billion were purchase commitments, primarily to lock in TSMC and HBM capacity 🏭. In addition, Q3 supply commitments rose from $279 billion in the previous quarter to $390 billion, and cloud service and data center lease commitments increased from $74 billion to $102 billion 📊. These commitments are not liabilities on the balance sheet, but if AI demand cools, they will become rigid cost pressures 🧊. The company's current cash and expected free cash flow provide sufficient buffer, but this buffer assumes that demand continues to grow ⚡.
🎯 In summary, the hashtag is true but one-sided. Nvidia did beat estimates, and the $130 billion Q4 outlook is indeed higher than the market expected ✅. But behind this “beat” lies a proactive retreat on margins, a passive loss of China revenue, the shadow of an SEC investigation, and an expanding scale of long-term commitments ⚖️. For investors, the real question is not “did it beat,” but “what price was paid to beat, and whether it is worth it” 🤔.


#BTC #Binance #AnthropicIPOPriceCouldExceed$80 #CanNvidia’sDataCenterGrowthContinue?