Anthropic's IPO is testing more than investor appetite for AI. It is testing whether AI's economics can justify the enormous capital being committed to it.
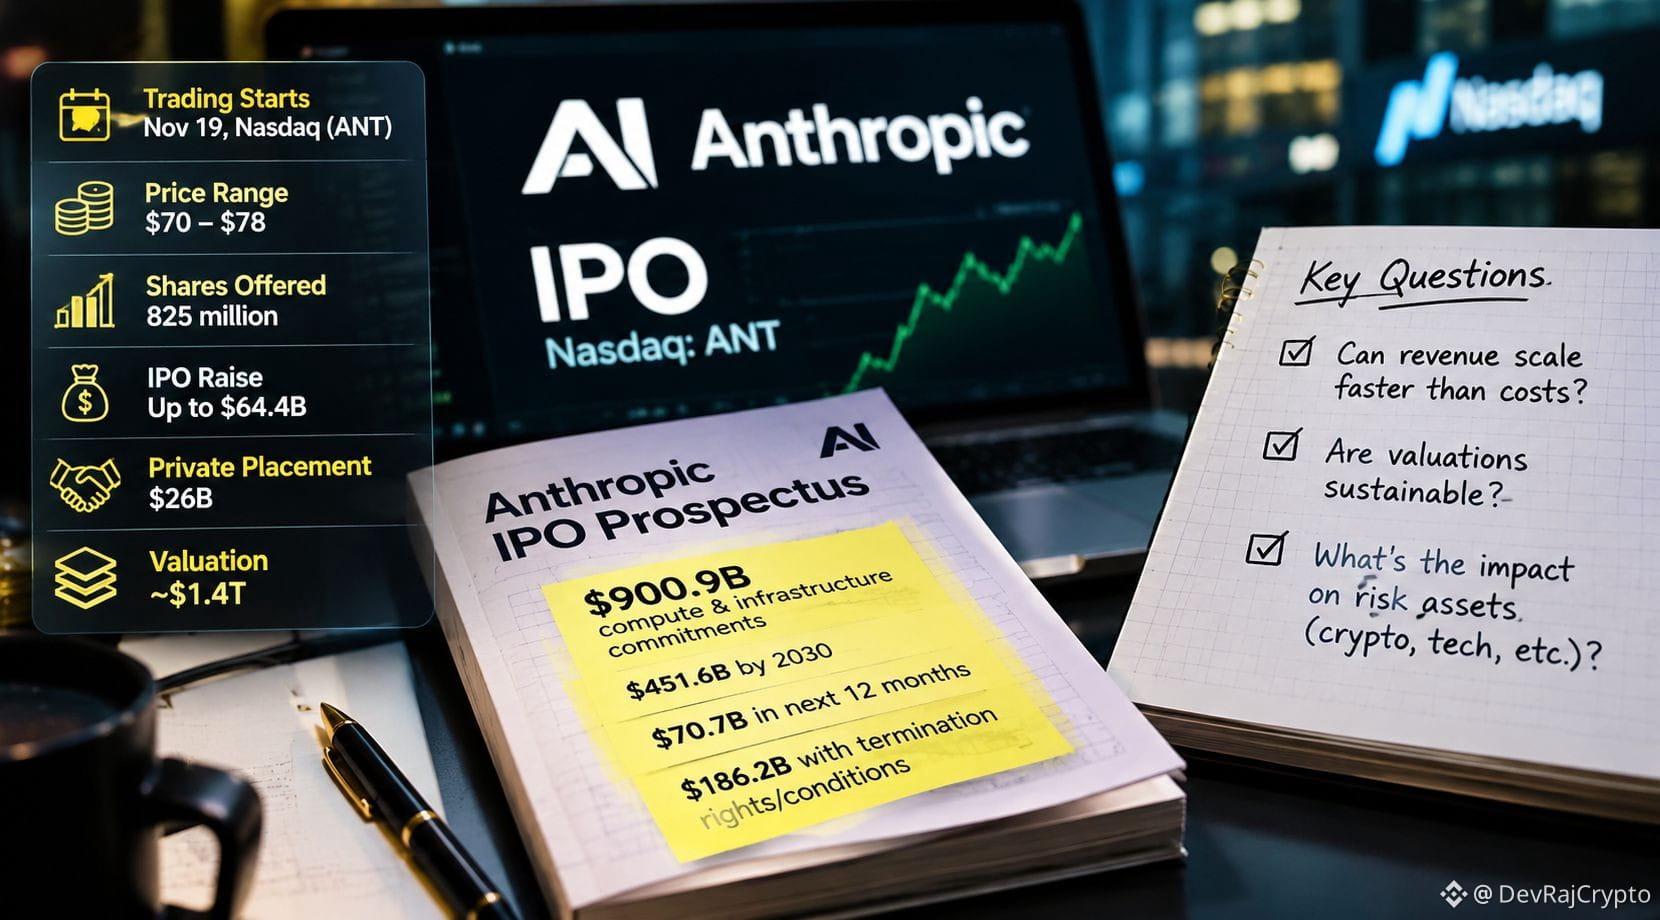
The company behind Claude is preparing for its Nasdaq debut on November 19 under ticker ANT.
Key figures:
• 825 million shares at an indicative $70–$78.
• Up to $64.4B from the IPO, plus a separate $26B private placement.
• Potential valuation of approximately $1.4T.
• Reportedly six-times oversubscribed.
But one number deserves more attention: $900.9 billion.
Anthropic's prospectus reports this amount in aggregate compute and infrastructure commitments. Around $451.6B is expected before the end of 2030, with $70.7B due within the following 12 months.
This is not an immediate debt bill. Approximately $186.2B involves termination rights or conditions that must be met before the arrangements begin.
The financial picture is equally important: Anthropic reported $33.2B in revenue during the first nine months of 2026, alongside an operating loss of approximately $1.26B.
My observation: AI demand is growing rapidly, but revenue growth alone doesn't prove a sustainable business model. The real test is whether revenue can outpace infrastructure and development costs.
Also, six-times oversubscription measures demand at the proposed offering terms, not whether the valuation is justified.
For crypto, the connection is broader risk appetite. A shift away from expensive growth valuations could pressure speculative assets, too. However, there is no verified evidence that Bitcoin is being sold specifically to fund this IPO.
My prediction: The debut may generate excitement, but sustained investor confidence will depend on whether AI growth translates into stronger financial performance.
The AI investment story is moving from proving demand to proving economics.
Can AI companies grow into these valuations, or will infrastructure costs eventually force a major reset?
$BTC $NVDA $ANT #CryptoMarket
The company behind Claude is preparing for its Nasdaq debut on November 19 under ticker ANT.
Key figures:
• 825 million shares at an indicative $70–$78.
• Up to $64.4B from the IPO, plus a separate $26B private placement.
• Potential valuation of approximately $1.4T.
• Reportedly six-times oversubscribed.
But one number deserves more attention: $900.9 billion.
Anthropic's prospectus reports this amount in aggregate compute and infrastructure commitments. Around $451.6B is expected before the end of 2030, with $70.7B due within the following 12 months.
This is not an immediate debt bill. Approximately $186.2B involves termination rights or conditions that must be met before the arrangements begin.
The financial picture is equally important: Anthropic reported $33.2B in revenue during the first nine months of 2026, alongside an operating loss of approximately $1.26B.
My observation: AI demand is growing rapidly, but revenue growth alone doesn't prove a sustainable business model. The real test is whether revenue can outpace infrastructure and development costs.
Also, six-times oversubscription measures demand at the proposed offering terms, not whether the valuation is justified.
For crypto, the connection is broader risk appetite. A shift away from expensive growth valuations could pressure speculative assets, too. However, there is no verified evidence that Bitcoin is being sold specifically to fund this IPO.
My prediction: The debut may generate excitement, but sustained investor confidence will depend on whether AI growth translates into stronger financial performance.
The AI investment story is moving from proving demand to proving economics.
Can AI companies grow into these valuations, or will infrastructure costs eventually force a major reset?
$BTC $NVDA $ANT #CryptoMarket