#A Packed Week of Earnings and Data Tests Markets
Markets are entering a week where corporate guidance and economic evidence could matter more than headlines. Investors will be watching whether business demand remains strong enough to justify current valuations, particularly across technology and consumer sectors.
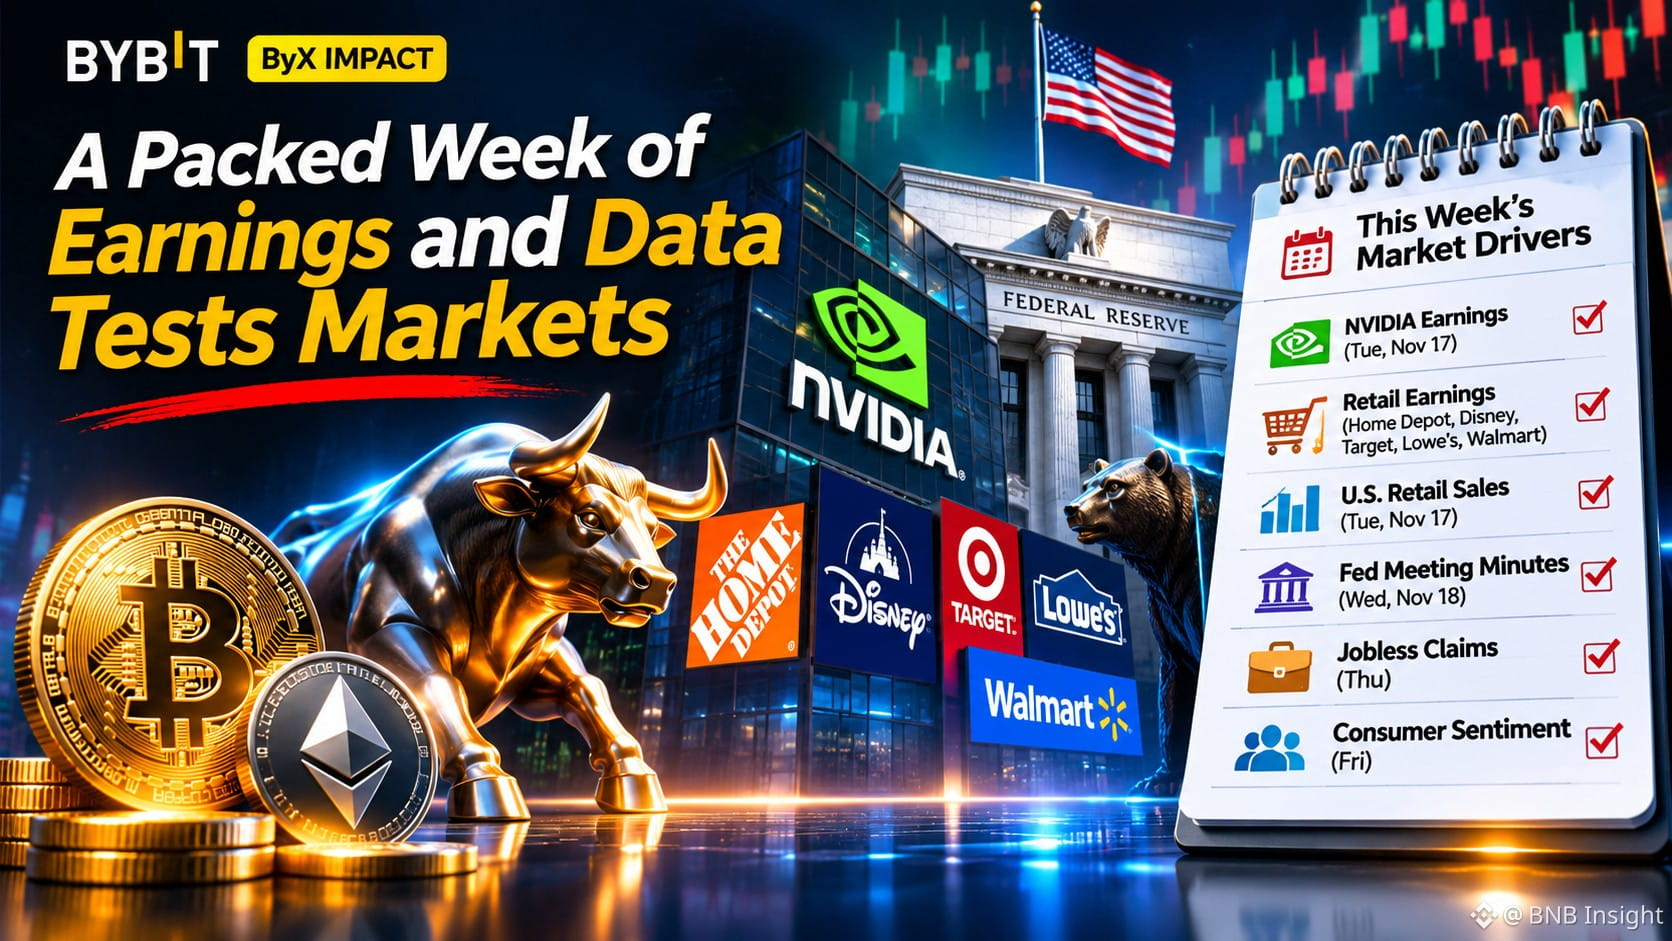
NVIDIA takes center stage. Its quarterly results, scheduled for Tuesday after the US market close, will be a major test of confidence in AI infrastructure spending. Investors will look beyond revenue growth to data-center demand, margins, supply capacity and management’s forward guidance. Strong results may support the wider technology sector, but even good numbers could disappoint if expectations are too aggressive.
Retail earnings bring another important signal. Home Depot and Disney report Tuesday, while Target and Lowe’s are scheduled for Wednesday and Walmart for Thursday. Their commentary may reveal whether consumers are still spending confidently or becoming more selective.
Economic data could shift rate expectations. Tuesday brings US October retail sales and industrial production. Wednesday brings housing data and the Federal Reserve’s October meeting minutes. Thursday’s jobless claims and Friday’s consumer sentiment reading will add further clues about employment and household confidence.
The key connection is liquidity. Strong corporate results combined with resilient economic activity could support equities, but unexpectedly persistent inflation or cautious Fed guidance may keep financial conditions restrictive. Crypto markets could also react through changes in risk appetite, dollar strength and liquidity expectations.
My focus this week is not simply whether companies beat earnings estimates. It is whether their guidance confirms sustainable growth.
Which event do you think will move markets most: NVIDIA’s results, retail sales, or the Fed minutes?
$NVDAB
Markets are entering a week where corporate guidance and economic evidence could matter more than headlines. Investors will be watching whether business demand remains strong enough to justify current valuations, particularly across technology and consumer sectors.
NVIDIA takes center stage. Its quarterly results, scheduled for Tuesday after the US market close, will be a major test of confidence in AI infrastructure spending. Investors will look beyond revenue growth to data-center demand, margins, supply capacity and management’s forward guidance. Strong results may support the wider technology sector, but even good numbers could disappoint if expectations are too aggressive.
Retail earnings bring another important signal. Home Depot and Disney report Tuesday, while Target and Lowe’s are scheduled for Wednesday and Walmart for Thursday. Their commentary may reveal whether consumers are still spending confidently or becoming more selective.
Economic data could shift rate expectations. Tuesday brings US October retail sales and industrial production. Wednesday brings housing data and the Federal Reserve’s October meeting minutes. Thursday’s jobless claims and Friday’s consumer sentiment reading will add further clues about employment and household confidence.
The key connection is liquidity. Strong corporate results combined with resilient economic activity could support equities, but unexpectedly persistent inflation or cautious Fed guidance may keep financial conditions restrictive. Crypto markets could also react through changes in risk appetite, dollar strength and liquidity expectations.
My focus this week is not simply whether companies beat earnings estimates. It is whether their guidance confirms sustainable growth.
Which event do you think will move markets most: NVIDIA’s results, retail sales, or the Fed minutes?
$NVDAB