
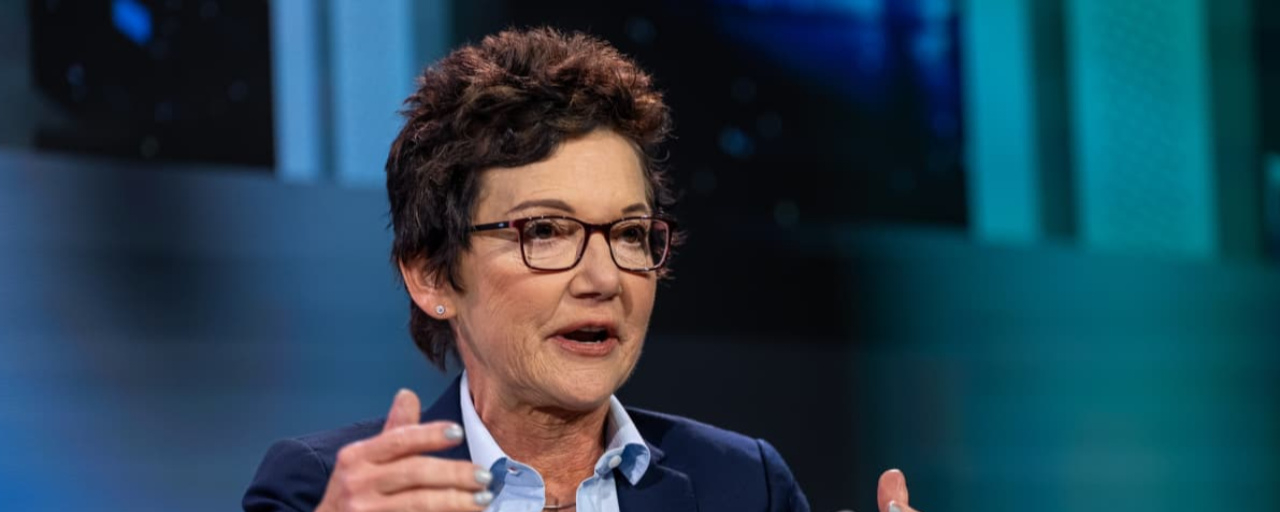
Mary C. Daly, President of the Federal Reserve Bank of San Francisco, who is not a voting member of the Federal Open Market Committee (FOMC) in 2026 because San Francisco’s turn on the rotating voting list comes in 2027, said her bias is that further tightening will be needed.
She spoke Thursday at the Stanford Institute for Economic Policy Research and made clear the Fed does not have to settle the timing and size of any move right away, with its next decision due Dec. 9.
Daly tied that stance to inflation. Shocks can compound, she warned, and the Fed cannot be complacent. Inflation is bleeding into services, and once services inflation rises, it is sticky. The Fed must focus on bringing it down. AI, she argued, is not the main culprit.
There is an inflation problem, but AI is not doing most of the driving. Still, she sees no doubt about AI-fueled price pressures and flagged a risk that AI could contribute more to inflation. Hiring faces a different squeeze.
Daly called it a perfect storm, with AI, uncertainty, and rising input costs all dampening hiring, though she said AI is having a limited impact on the labor market. On the supply side, she sees positive momentum for productivity growth, with a lot of work underway and more gains possible within the next one to three years.
Fighting inflation now, she said, does not mean ignoring the potential for productivity growth to be disinflationary. Daly also addressed AI valuations. She has seen repricing, but she said it is not the unwinding of interest or enthusiasm, and it suggests no risk to growth. The economy, she added, is being driven by a technology boom.
Key Quotes:
Monetary Policy
Bias is that further tightening will be needed
Must focus on bringing inflation down
Inflation
Inflation shocks can compound; cannot be complacent
Inflation is bleeding into services
Once services inflation rises, it is sticky
AI & Inflation
There is an inflation problem, but AI is not doing most of the driving
‘No doubt’ of AI-fueled price pressures
There is a risk AI could contribute more to inflation
Labor Market
We are in a perfect storm for hiring
AI, uncertainty, and rising input costs are all dampening hiring
AI is having a limited impact on the labor market
AI & Productivity
Sees positive momentum for productivity growth
A lot of work being done; might see more productivity growth within next 1-3 years
Having to fight inflation problem now does not mean ignoring potential for productivity growth to be disinflationary
AI Investment & Valuations
Have seen repricing in AI valuations, ‘but it’s not the unwinding of interest or enthusiasm’
Repricing in AI valuations suggests there’s not a risk to growth
Deep AI pipeline that continues even if it slows
Growth & Economy
Sees a stable labor market, positive growth and productivity growth, and high inflation
Economy is being driven by a technology boom