#BitMineReports$6.3BNetLossForFiscal2026
⚖️ BITMINE'S $6.3B LOSS: THE REAL TEST ISN'T ETH'S PRICE — IT'S THE TREASURY MODEL
🏢 BitMine Immersion Technologies (BMNR) | FY2026 Financial Deep Dive | 12 November 2026
📉 The headline looks disastrous. But the underlying story is far more complicated.
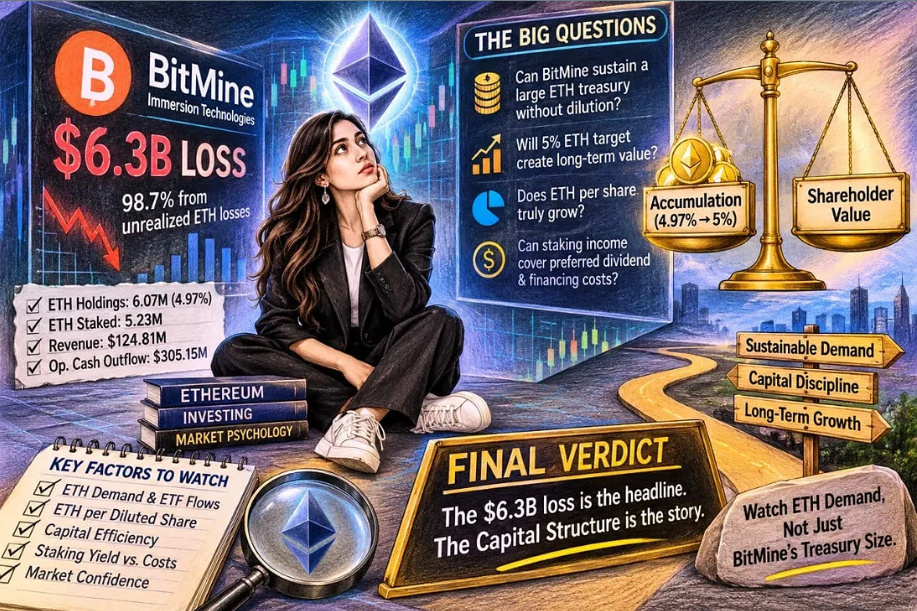
BitMine reported a $6.313 billion net loss for the fiscal year ended August 31, 2026, reversing a $348.6 million profit in FY2025.
But beneath that headline lies a much bigger question for Ethereum investors:
🧠 Can an institutional company continue building an enormous ETH treasury without sacrificing shareholder value through dilution, financing costs and declining asset prices?
Let's look beyond the headline.
━━━━━━━━━━━━━━━━━━━━
🔴 1. THE $6.3 BILLION LOSS: ACCOUNTING DAMAGE OR FINANCIAL DISTRESS?
The most important distinction is the source of the loss.
• 📉 Total net loss: $6.313 billion
• 🧾 Unrealized digital-asset losses: $6.229 billion
• 💰 Total revenue: $124.81 million
• 🔐 Staking and validation revenue: $121.36 million
• 🏢 General and administrative expenses: $376.90 million
• 💸 Operating cash outflow: $305.15 million
Approximately 98.7% of the reported net loss corresponds to unrealized digital-asset valuation losses.
Under fair-value accounting, falling ETH prices flow directly into reported earnings even when the underlying holdings remain on the balance sheet.
However, calling the entire loss harmless would be misleading. BitMine still reported negative operating cash flow, substantial operating expenses and considerable exposure to ETH volatility.
🧠 The distinction: An unrealized loss does not automatically mean cash has disappeared, but a falling asset base can eventually affect liquidity, financing capacity and shareholder confidence.
━━━━━━━━━━━━━━━━━━━━
🎯 2. THE 5% ETH TARGET: THE NEXT IMPORTANT CATALYST
This is where the story becomes particularly interesting for ETH traders.
As of November 8, BitMine disclosed:
• 🪙 ETH holdings: 6,070,092 ETH
• 📊 Share of ETH supply: 4.97%
• 🔒 ETH staked: 5,227,037
• 🛒 Latest weekly purchase: 9,587 ETH
• 🎯 Remaining distance to 5%: approximately 40,000 ETH.
The company is approaching its publicly stated Alchemy of 5% objective.
At the latest reported purchasing pace, the remaining quantity represents roughly four weeks of accumulation.
But there is an important distinction: 5% is a strategic target, not a binding purchase ceiling.
Why does this matter?
BitMine has been a consistent institutional ETH buyer. If it reaches its target and reduces purchases, one source of recurring demand could weaken.
However, the market impact should not be exaggerated. Its latest weekly purchase was approximately $21.4 million, relatively small compared with the overall ETH market.
⚠️ The bigger impact could be psychological: traders may begin questioning where the next sustained institutional buyer will come from.
━━━━━━━━━━━━━━━━━━━━
🏦 3. THE HIDDEN PRESSURE: SHAREHOLDER DILUTION
This is arguably more important for BMNR shareholders than the accounting loss itself.
During FY2026:
• 📈 BitMine issued approximately 395.1 million shares through its at-the-market offering.
• 💵 Gross proceeds were approximately $13.2 billion.
• 🔄 It repurchased approximately 20.8 million shares at an average price of $17.
Capital raising helped finance its enormous digital-asset accumulation.
But shareholders should look beyond the total ETH held.
The more meaningful measurement is ETH per diluted share.
If the number of shares increases faster than the ETH treasury, an investor's proportional exposure to ETH may not grow as quickly as the headline treasury suggests.
This creates a critical distinction between owning a growing corporate ETH reserve and owning an increasingly valuable claim on that reserve.
⚖️ A large treasury does not automatically translate into attractive per-share returns.
━━━━━━━━━━━━━━━━━━━━
💳 4. THE 9.5% PREFERRED DIVIDEND: A STRUCTURAL FINANCING CHALLENGE
BitMine's Series A preferred stock, trading under BMNP, carries a cumulative 9.50% annual dividend rate.
Its FY2026 filing disclosed:
• 🏦 3.5 million preferred shares issued.
• 💰 $280 million gross proceeds.
• 💵 $271.48 million net proceeds.
• 📋 $100 stated liquidation preference per share.
• ⚠️ Preferred claims rank ahead of common equity.
• 📅 Approximately $33.3 million in expected cash dividends over the next 12 months, based on the disclosed capital structure.
Compare this with the 2.65% trailing seven-day staking yield reported on November 8.
The difference deserves attention.
The preferred financing carries a substantially higher stated rate than the current staking yield.
But this is not a simple one-to-one comparison: the preferred dividend applies to preferred capital, while staking income is earned across a much larger ETH position.
BitMine estimates approximately $309 million in annualized staking rewards at its existing staking scale.
That provides an income stream, but does not eliminate the financing burden, operational costs or ETH price risk.
🧠 The real question: Can staking income, treasury appreciation and institutional staking services collectively support the company's capital structure over time?
━━━━━━━━━━━━━━━━━━━━
🌊 5. ETH MARKET IMPACT: WHO REPLACES BITMINE'S BUYING?
The broader market environment makes this development worth watching.
Spot ETH ETFs recorded approximately $365.3 million in net outflows during the week ending November 6, extending their losing streak to six consecutive weeks.
This creates an uncomfortable combination:
• 📉 Institutional ETF demand is weakening.
• 🎯 BitMine is approaching its accumulation target.
• 🏦 ETH treasury companies face financing and valuation pressures.
• 🔐 Staking rewards remain sensitive to ETH prices and network yields.
However, ETF flows and corporate treasury purchases are not the entire ETH demand picture.
On-chain activity, stablecoin growth, tokenization, network adoption, macroeconomic liquidity and broader investor positioning will also influence the next market direction.
🌍 The market does not necessarily need another BitMine. It needs sustainable demand from multiple sources.
━━━━━━━━━━━━━━━━━━━━
🧩 6. THE BIGGER PICTURE: THE DIGITAL ASSET TREASURY MODEL IS BEING TESTED
BitMine's situation has implications beyond one company.
The digital asset treasury (DAT) model depends on several interconnected factors:
🪙 The underlying cryptocurrency must maintain or increase its long-term value.
💰 The company must raise capital without destroying shareholder value.
📈 Treasury growth must translate into stronger per-share exposure.
⚖️ Financing costs must remain manageable.
🤝 The company's stock must retain sufficient market confidence and liquidity.
When the share price trades below the value of its underlying assets, issuing additional shares can become economically unattractive.
When ETH declines, the treasury shrinks in dollar terms.
When financing costs remain elevated, the company must work harder to justify its equity valuation.
⚠️ This is where the DAT model can move from a powerful accumulation strategy into a difficult capital-allocation exercise.
━━━━━━━━━━━━━━━━━━━━
🔍 7. WHAT TRADERS AND INVESTORS SHOULD WATCH NEXT
📊 For ETH traders:
• Whether BitMine continues weekly purchases after approaching 5%.
• Whether ETF outflows begin stabilizing.
• Whether institutional spot demand returns.
• Whether ETH establishes stronger support and recovers important trend levels.
• Whether broader liquidity conditions improve.
🏢 For BMNR shareholders:
• ETH held per diluted share.
• Common-share issuance versus repurchases.
• Preferred dividend coverage.
• Staking income versus operating and financing costs.
• Net asset value relative to BMNR's market capitalization.
These indicators will reveal more about the company's financial health than the headline loss alone.
━━━━━━━━━━━━━━━━━━━━
🧠 FINAL VERDICT: THE $6.3 BILLION LOSS IS THE HEADLINE. THE CAPITAL STRUCTURE IS THE STORY.
BitMine has not suddenly become a failed Ethereum treasury because of one accounting-heavy loss.
Its staking business is generating meaningful revenue, its ETH position remains enormous, and its balance sheet reported just $33.7 million in liabilities at fiscal year-end.
But the investment thesis is changing.
The next stage is no longer simply about accumulating as much ETH as possible.
It is about converting that accumulation into sustainable shareholder value.
For Ethereum, the potential reduction in BitMine's buying deserves attention, particularly alongside ETF outflows. But it is not sufficient evidence of an impending supply-demand collapse.
For BMNR, the real test is whether ETH appreciation, staking economics and disciplined financing can outweigh dilution and preferred capital costs.
🎯 MY MARKET VIEW:
Watch ETH demand, not just BitMine's treasury size.
Watch ETH per share, not just total ETH holdings.
Watch capital efficiency, not just accumulation announcements.
And never confuse a company's conviction in an asset with a guarantee of returns for its shareholders.
The next chapter of the institutional Ethereum treasury trade will be decided by capital efficiency, not accumulation headlines. ⚖️