
📉 The S&P 500 Just Got Cheaper Without Falling—Here's the Real Story
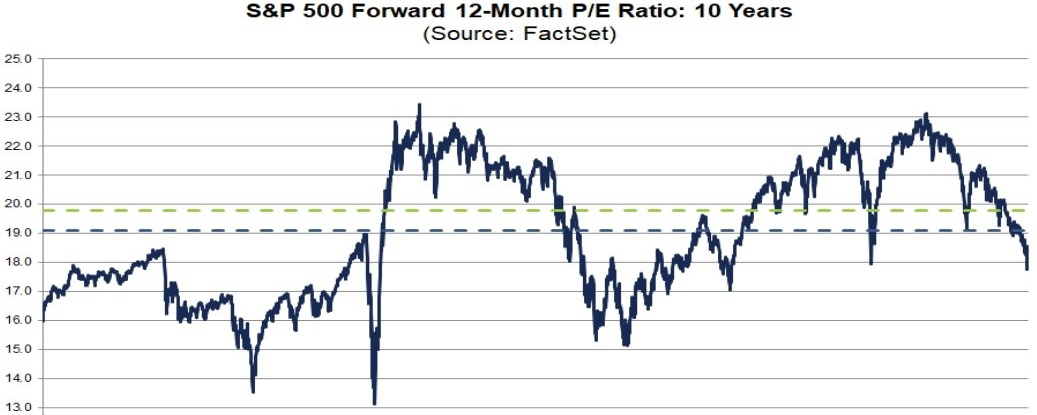
The S&P 500's forward 12-month P/E ratio has slipped to 17.7, its lowest reading since November 2023 . On the surface, that might sound like the market has been bleeding. It hasn't. The index is actually up this year. What's happening is something far more interesting—and honestly, far healthier than a typical "cheap market" narrative.

Let's put the number in context. The five-year average sits at 19.8, the ten-year at 19.1, and the fifteen-year at 17.6 . So yes, we're below the recent norms, but not in some historic bargain bin. The 25-year low was 8.6 back in 2008 . Perspective matters here.
So what's actually driving the multiple down? Earnings estimates have been on a tear. At the start of 2026, the forward P/E was sitting at 22.0. Since then, the S&P 500's price has climbed about 7.4%, while forward 12-month EPS estimates have surged roughly 33.6% . The "E" in that ratio is doing all the heavy lifting. Prices moved, but earnings forecasts moved nearly five times faster 😅.

That gap tells you something important: this isn't a market being carried by multiples expanding or speculative euphoria. It's a market where analysts keep getting surprised by how strong corporate profits are turning out to be, and they're rushing to mark their numbers up . The denominator is catching up to the numerator—and then some.
The AI capex boom deserves a lot of the credit here. Goldman Sachs has pointed out that AI infrastructure spending is expected to account for roughly half of S&P 500 earnings growth this year, with the biggest cloud providers pouring hundreds of billions into data centers .
That spending flows straight into the revenue lines of semiconductors, hardware, industrials, and even utilities. It's not just a story stock narrative anymore—it's showing up in the actual profit estimates.

One detail that caught my eye: the Information Technology sector's forward P/E has dropped to around 17.3, which is actually below its 25-year average of 20.0 .
For the first time in years, tech isn't the most expensive kid on the block by this measure. Energy sits at 11.7 versus a 25-year average of 13.9 . The "expensive market" label is getting harder to stick.
None of this means the road ahead is smooth. Concentration is still historically high, and the whole earnings story leans heavily on AI spending continuing at this pace . If those estimates start getting revised downward instead of upward, the math flips fast.
But for now, the takeaway is straightforward: the market didn't get cheaper because prices crashed. It got cheaper because profits grew into the price 📊.
That's a much more comfortable place to be than the alternative.
Please don’t forget to like, follow, and share! 🩸 Thank you so much ❤️
#HotCPIDecemberHikePriced #AnthropicRejectsIPODelayValuationinQuestion #CoreWeaveJumps10%On168%RevenueGrowth