$SNDKB : Liquidity Tier Effects on Slippage and ATR
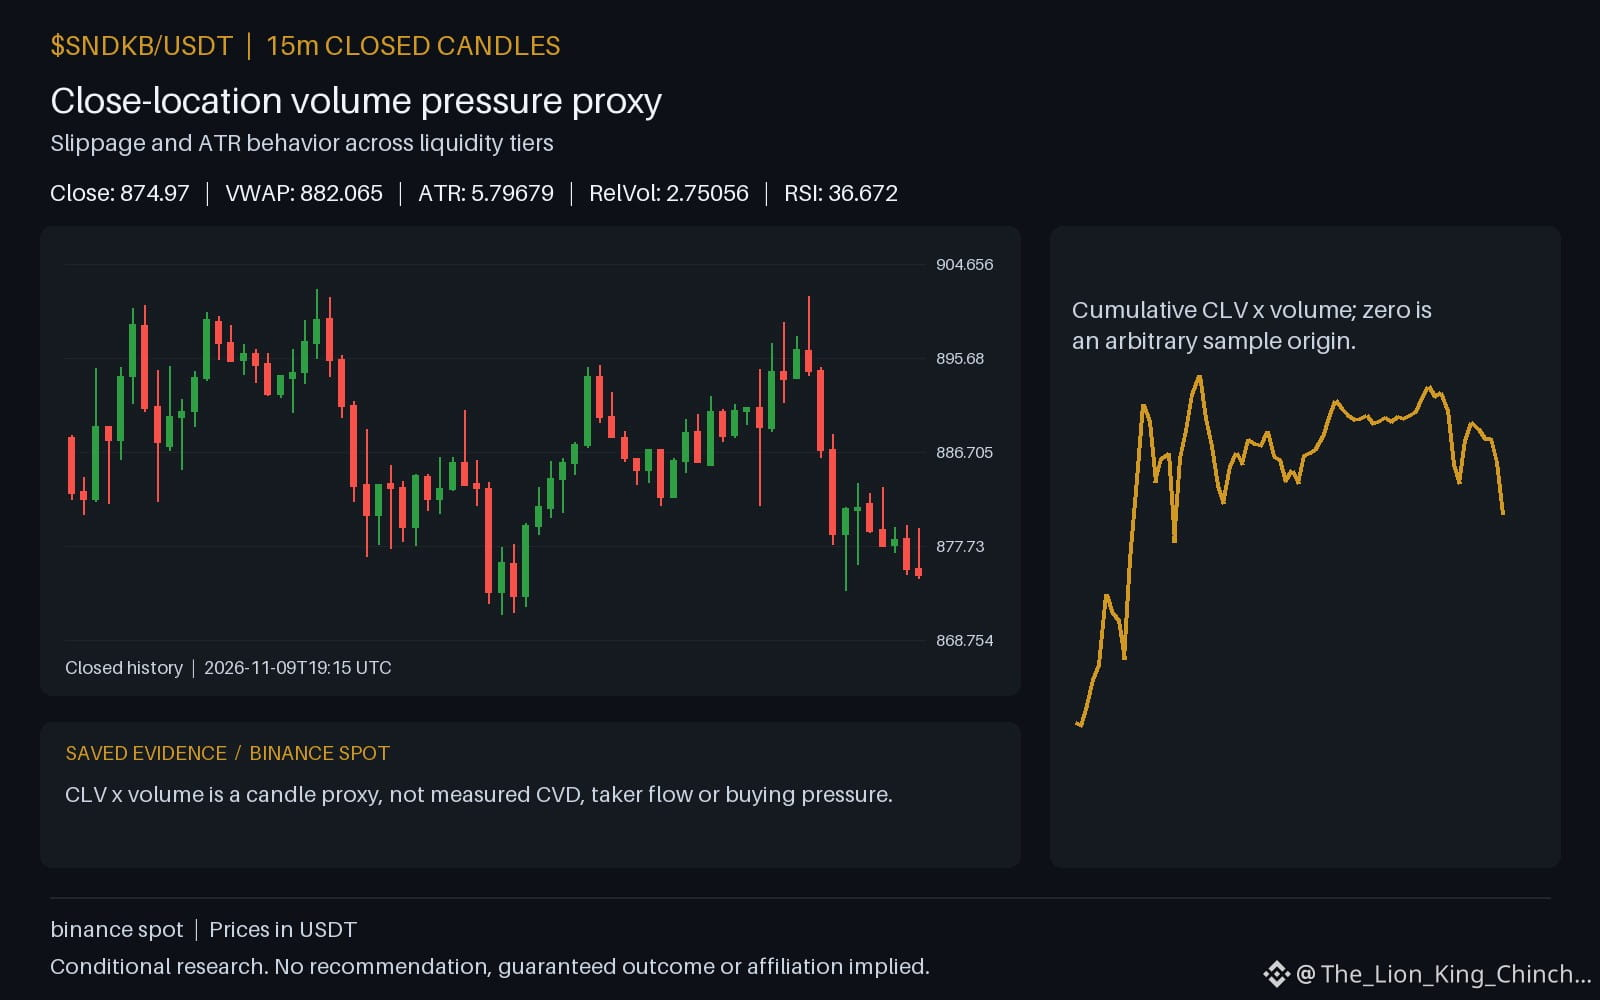
A common assumption is that lower liquidity always produces higher slippage, and that the average true range (ATR) will rise proportionally. The observation for the primary asset shows an hourly direction down with volume above baseline, while peer ETH also moves down but with strong volume, and peer INIT moves down with weaker volume. This contrast creates a thought experiment about how ATR reacts across tiers.
The counterexample considers that even with higher volume, a thinly traded coin can display a modest ATR if price moves stay within a narrow band. Conversely, a highly liquid asset may exhibit a larger ATR when a sudden shift overwhelms market depth. The hourly ATR reading for the primary asset uses 5.79679, while peers display their own 5.79679 values that are not directly comparable because liquidity conditions differ.
What could change the reading is a shift in order flow that expands the effective spread, causing slippage to grow faster than ATR. To reassess, one could monitor the relative volume 2.75056 alongside the ATR on an hourly chart and note when the spread widens beyond the typical 5.79679 range. This self‑check highlights the limits of assuming a fixed relationship between slippage and ATR across liquidity tiers. 🙂
Probabilistic market research, not a recommendation or guaranteed return.
For a wider view: $ETH has hourly direction down and volume above its baseline; $INIT has hourly direction down and volume not above its baseline. This alone does not establish correlation.
Would you keep the same rule after missing a move?
#SNDKB #ETH #INIT
A common assumption is that lower liquidity always produces higher slippage, and that the average true range (ATR) will rise proportionally. The observation for the primary asset shows an hourly direction down with volume above baseline, while peer ETH also moves down but with strong volume, and peer INIT moves down with weaker volume. This contrast creates a thought experiment about how ATR reacts across tiers.
The counterexample considers that even with higher volume, a thinly traded coin can display a modest ATR if price moves stay within a narrow band. Conversely, a highly liquid asset may exhibit a larger ATR when a sudden shift overwhelms market depth. The hourly ATR reading for the primary asset uses 5.79679, while peers display their own 5.79679 values that are not directly comparable because liquidity conditions differ.
What could change the reading is a shift in order flow that expands the effective spread, causing slippage to grow faster than ATR. To reassess, one could monitor the relative volume 2.75056 alongside the ATR on an hourly chart and note when the spread widens beyond the typical 5.79679 range. This self‑check highlights the limits of assuming a fixed relationship between slippage and ATR across liquidity tiers. 🙂
Probabilistic market research, not a recommendation or guaranteed return.
For a wider view: $ETH has hourly direction down and volume above its baseline; $INIT has hourly direction down and volume not above its baseline. This alone does not establish correlation.
Would you keep the same rule after missing a move?
#SNDKB #ETH #INIT