🏛️ The bond market's refusal to blink is forcing a violent liquidation of the long-duration trade, ruthlessly separating cash-flow monopolies from subsidized cyclicality... 💀
The macro mechanism at play is the aggressive repricing of the Fed's terminal rate expectations. With real yields holding structurally elevated, high-multiple and capital-intensive sectors are being crushed by an unforgiving discount rate. The AI narrative is no longer a rising tide; it is failing to subsidize legacy hardware or speculative infrastructure when liquidity is actively draining from the system.
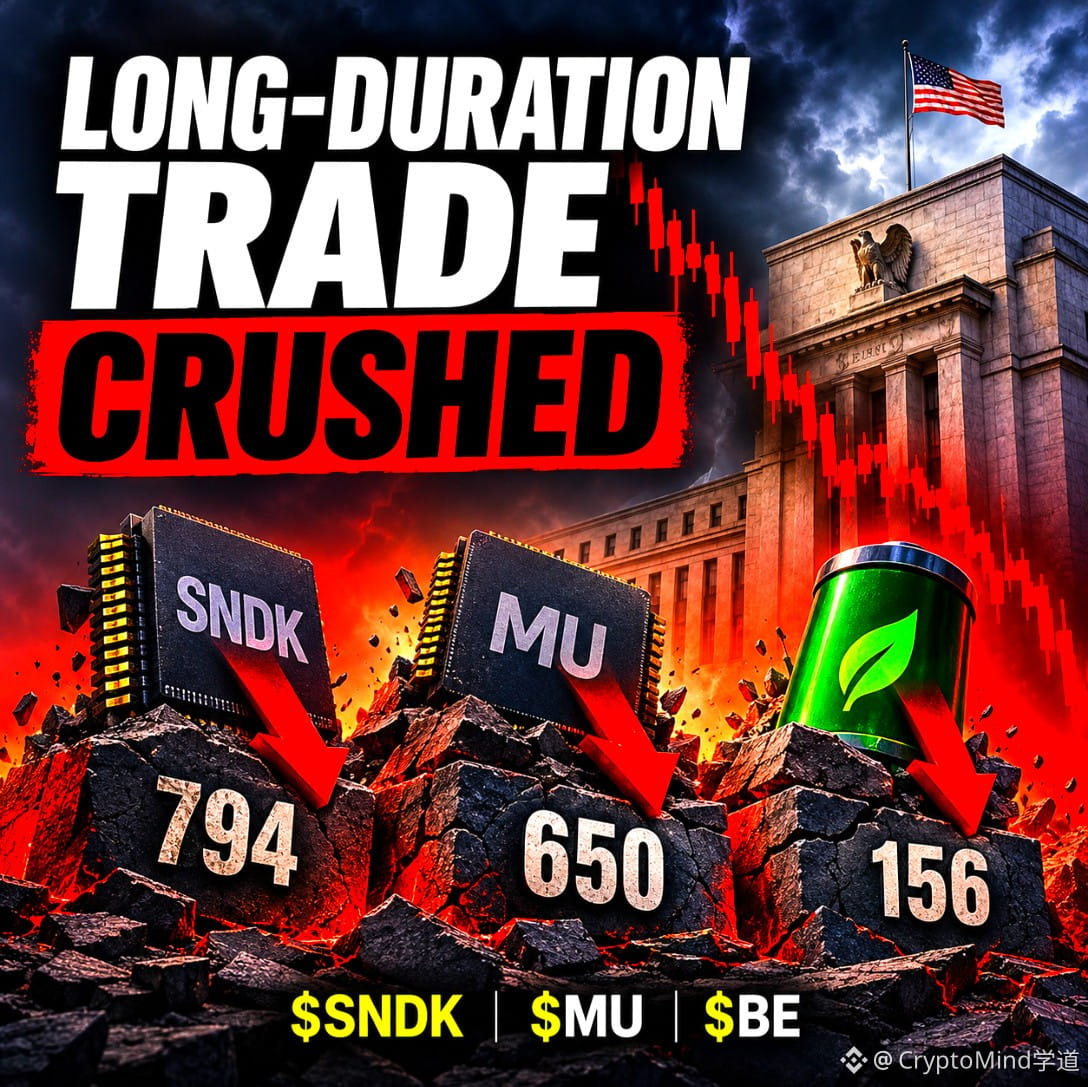
Look at the structural breakdown in the memory complex. $SNDK has collapsed from 1,199 down to 794, and while the RSI sits at 33 indicating oversold conditions, there is zero institutional bid stepping in to catch the falling knife. $MU is trapped in the exact same bearish regime, gutted from 916 to 650 with an RSI of 37, as the market violently reprices the hardware cycle and abandons delayed cyclical recoveries.
Meanwhile, $BE a highly capital-intensive energy transition play, is being rejected at every technical bounce—crushed from 232 to 156, barely clinging to 175 with an RSI of 43. When the cost of capital is this punitive, funding is indiscriminately pulled from both cyclical hardware and speculative green infrastructure.
Capital is fleeing into short-duration safety and immediate cash-flow generators. If real yields remain structurally restrictive to fight sticky inflation, which of these capital-intensive sectors actually has the balance sheet to survive the ongoing liquidity drain?
The macro mechanism at play is the aggressive repricing of the Fed's terminal rate expectations. With real yields holding structurally elevated, high-multiple and capital-intensive sectors are being crushed by an unforgiving discount rate. The AI narrative is no longer a rising tide; it is failing to subsidize legacy hardware or speculative infrastructure when liquidity is actively draining from the system.
Look at the structural breakdown in the memory complex. $SNDK has collapsed from 1,199 down to 794, and while the RSI sits at 33 indicating oversold conditions, there is zero institutional bid stepping in to catch the falling knife. $MU is trapped in the exact same bearish regime, gutted from 916 to 650 with an RSI of 37, as the market violently reprices the hardware cycle and abandons delayed cyclical recoveries.
Meanwhile, $BE a highly capital-intensive energy transition play, is being rejected at every technical bounce—crushed from 232 to 156, barely clinging to 175 with an RSI of 43. When the cost of capital is this punitive, funding is indiscriminately pulled from both cyclical hardware and speculative green infrastructure.
Capital is fleeing into short-duration safety and immediate cash-flow generators. If real yields remain structurally restrictive to fight sticky inflation, which of these capital-intensive sectors actually has the balance sheet to survive the ongoing liquidity drain?