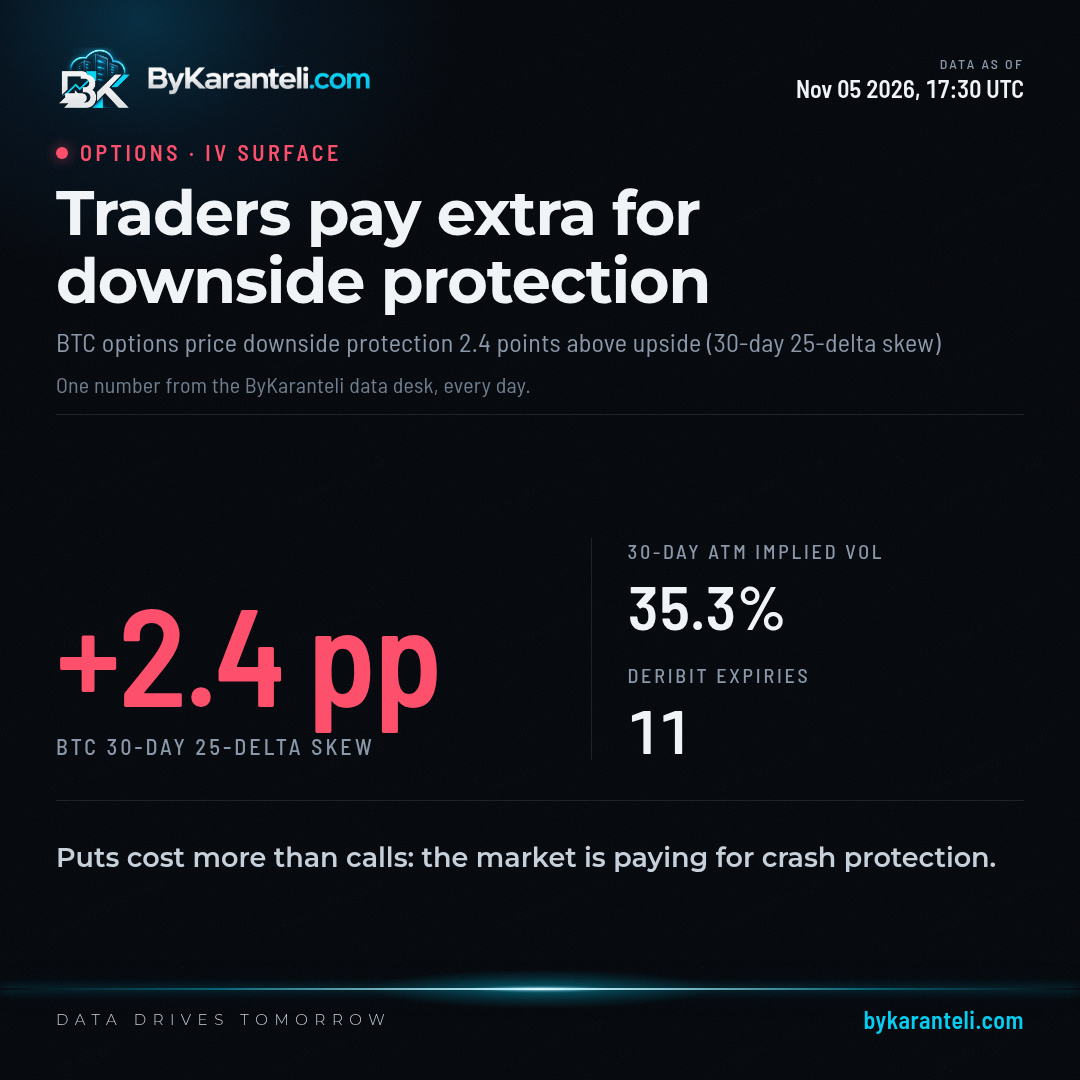
Options traders are paying a little extra to insure against a drop. Downside protection is priced +2.4pp above comparable bets on a rise, measured across 11 expiries.
Skew is the gap in implied volatility between puts, which pay if the price falls, and calls, which pay if it rises. At the money, implied volatility reads 35.3, the size of move the options market is pricing either way.
A modest premium on the downside shows where hedging demand sits. It is a measure of what protection costs, not a call on direction.
Skew is the gap in implied volatility between puts, which pay if the price falls, and calls, which pay if it rises. At the money, implied volatility reads 35.3, the size of move the options market is pricing either way.
A modest premium on the downside shows where hedging demand sits. It is a measure of what protection costs, not a call on direction.