
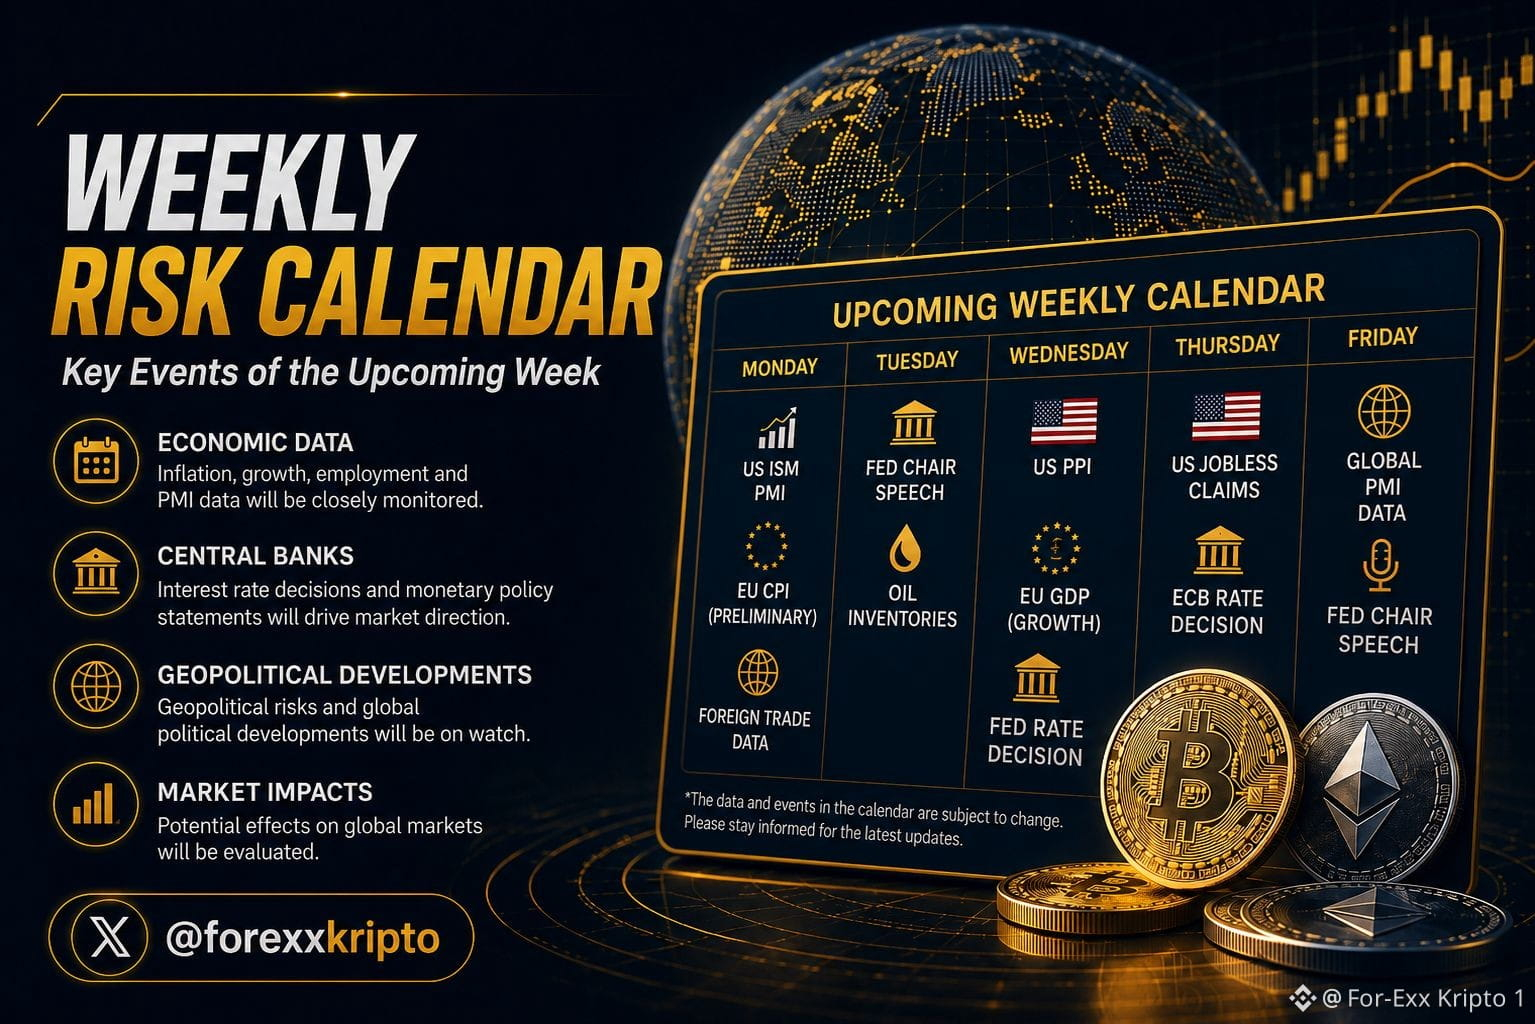
📅 WEEKLY MACRO & RISK CALENDAR | NOV 2–6, 2026 Theme: US midterms, Friday’s jobs report, RBA/BoE decisions. No Fed meeting; next Dec. 8–9. US winter time began Nov. 1; US data are 8 hours behind Istanbul. MON, NOV 2 8:00 — ISM Manufacturing PMI. 🌍 Final global manufacturing PMIs. NPC Standing Committee begins (to Nov. 6). TUE, NOV 3 06:30 — RBA decision. 10:00 — October CPI; 🇨🇭 October CPI. 18:00 — JOLTS (Sep.). Midterms: 35 Senate seats, 435 House seats, 36 governorships. Results overnight into Nov. 4. WED, NOV 4 13:00 — Eurozone flash CPI; final services/composite PMIs. 16:15 — ADP; 16:30 — trade balance/Treasury refunding; 18:00 — ISM Services. Riksbank, 🇵🇱 NBP, 🇧🇷 BCB decisions; 🇯🇵 BoJ minutes. THU, NOV 5 12:00 — Norges Bank. 15:00 — BoE decision/report. CNB, 🇲🇽 Banxico decisions. 16:30 — Jobless claims; 🇨🇦 federal budget. FRI, NOV 6 16:30 — October payrolls, unemployment, hourly earnings. 16:30 — October jobs report. 18:00 — Michigan sentiment (prelim.). Industrial production; 🇪🇺 retail sales (Sep.). ━━━ CRYPTO IMPACT & WEEKLY RISKS Midterms are the key uncertainty. Congressional control may shift tax, spending, regulation and crypto-law expectations. Overnight results create Asia-session volatility; close counts may prolong uncertainty. Friday’s NFP is key for December Fed pricing. Weak hiring may boost rate-cut bets and support crypto; strong data could lift dollar/yields and hurt risk appetite. Wednesday’s ADP and ISM Services offer earlier signals. Treasury refunding affects long-term bond supply and liquidity. RBA, Riksbank and BoE decisions matter: hawkish surprises could tighten global liquidity. BoE votes/guidance and Eurozone CPI shape rate expectations. Türkiye’s CPI may affect TCMB expectations, lira assets, local crypto volumes and USDT/TRY. Key risk windows: election night into Wednesday; Wed. 16:15–18:00 US data; Fri. 16:30 NFP. Thin liquidity can amplify moves; review leverage. $BTC $ET
Krypto-Nutzer weltweit auf Binance Square kennenlernen
⚡️ Bleib in Sachen Krypto stets am Puls.
💬 Die weltgrößte Kryptobörse vertraut darauf.
👍 Erhalte verlässliche Einblicke von verifizierten Creators.
E-Mail-Adresse/Telefonnummer