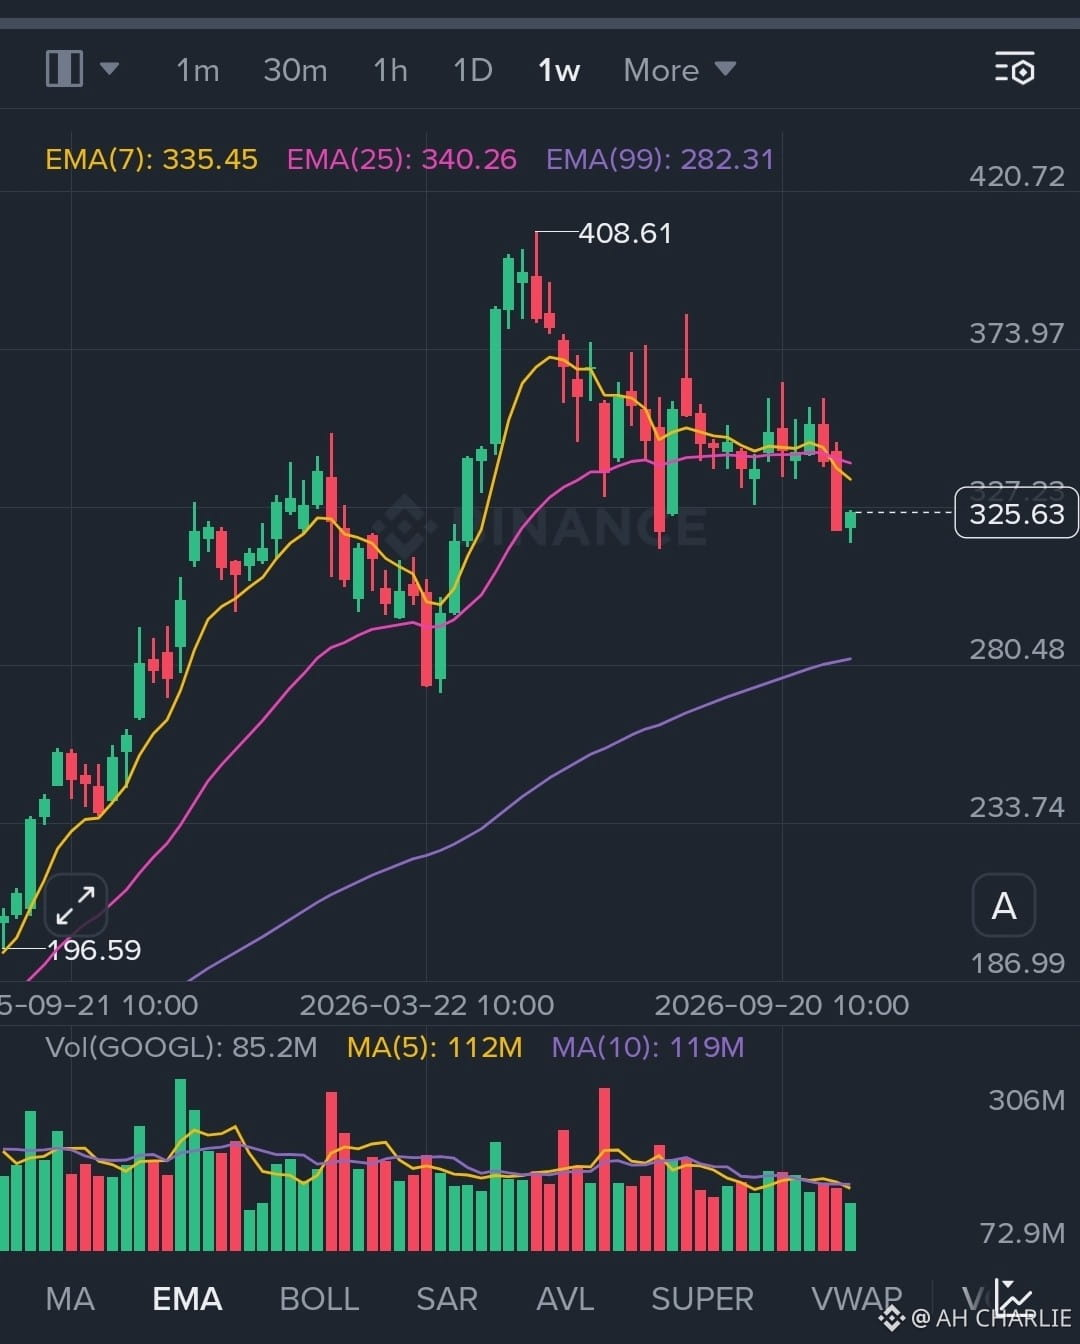
$GOOGL reclaiming its $408.61 ATH requires roughly a 25.5% expansion. While that sounds modest to crypto traders, in TradFi mega-caps that means injecting over $1.01 Trillion in fresh equity value — literally absorbing the equivalent of Meta’s entire market cap into a single ticker. At $325.63, the market is finally waking up to the structural friction: Alphabet is rapidly transitioning from an asset-light ad monopoly into an asset-heavy compute utility. The cash mechanics explain why smart money is hesitating. Pushing Q3 CapEx to $51.4 Billion flipped quarterly Free Cash Flow negative to -$9.1 Billion. Even though Google Cloud posted an impressive $11.1B operating income backed by a $561B backlog, legacy Search still funds the entire balance sheet. The deeper issue isn't just spending $200B+ on infrastructure; it’s that generative AI search queries cost significantly more compute per user session than classic blue links. Alphabet is spending historic capital not to expand its moat, but simply to defend it while actively diluting its own operating margins. Technically, the weekly chart reflects this valuation stress.GOOGL has cracked cleanly below both the 7-week EMA ($335.45) and the 25-week EMA ($340.26) on heavy distribution. Unless bulls engineer an immediate high-volume reclaim above $340, the natural structural base for this multi-quarter reset sits down at the 99-week EMA ($282.31).
Until massive CapEx translates into genuine bottom-line earnings rather than defensive margin cannibalization, Wall Street will keep compressing multiples. Is this dip an institutional buying window, or is the market repricing Alphabet into an asset-heavy era? Are you holding GOOGL through this CapEx cycle or waiting for the $282 EMA(99) retest?
Educational Only.Always DYOR before managing risk.
#BinancePick #EarningsSeason #CanGoogleDefendItsCore