

10:30 AM ET is arguably the first domino.** 🛢️
Here's the setup: the API estimated U.S. crude inventories fell by **4.93 million barrels** in the week ending October 16, right after a massive **11.12 million barrel draw** the week before. The official EIA number lands at **10:30 AM ET today**, and the consensus forecast sits at roughly **-0.3 million barrels**. If the government data confirms anything close to the API, that's a fifth consecutive surprise draw — and crude sits at **415.6 million barrels, 3% below the five-year average**.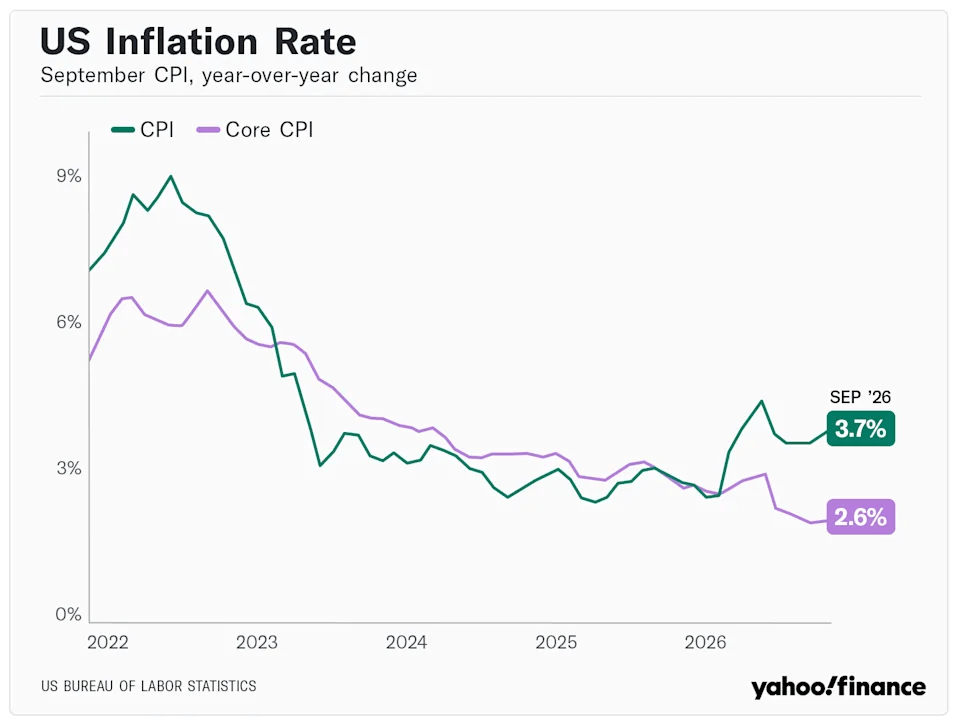
## The chain nobody connects
Your point is spot on, and the data proves it. September CPI came in at **0.6% month-over-month and 3.7% year-over-year**, hotter than the 3.6% expected. And here's the kicker: **gasoline jumped 9.1% in a single month and accounted for more than half of that increase**.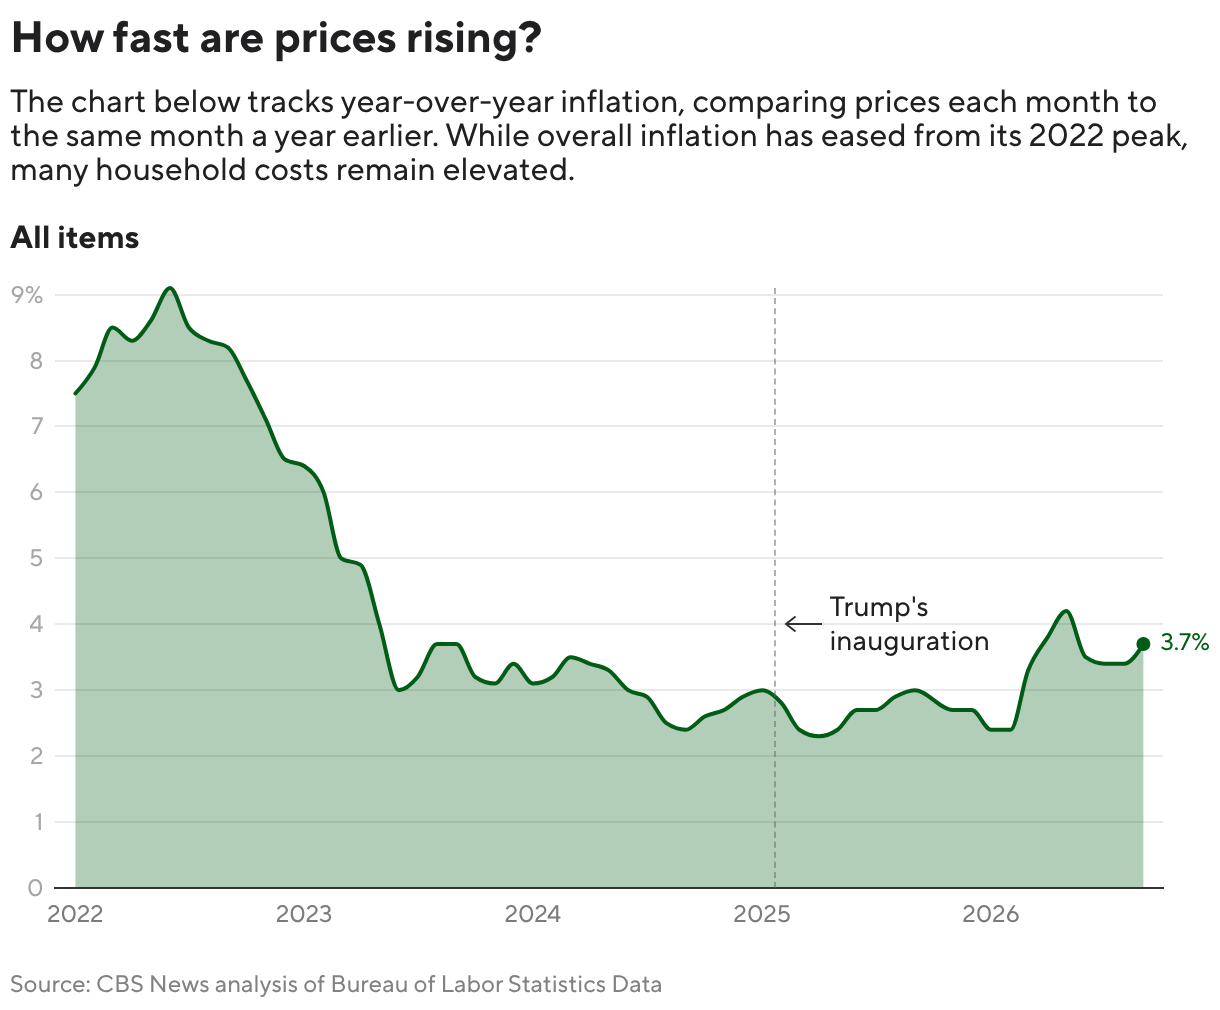
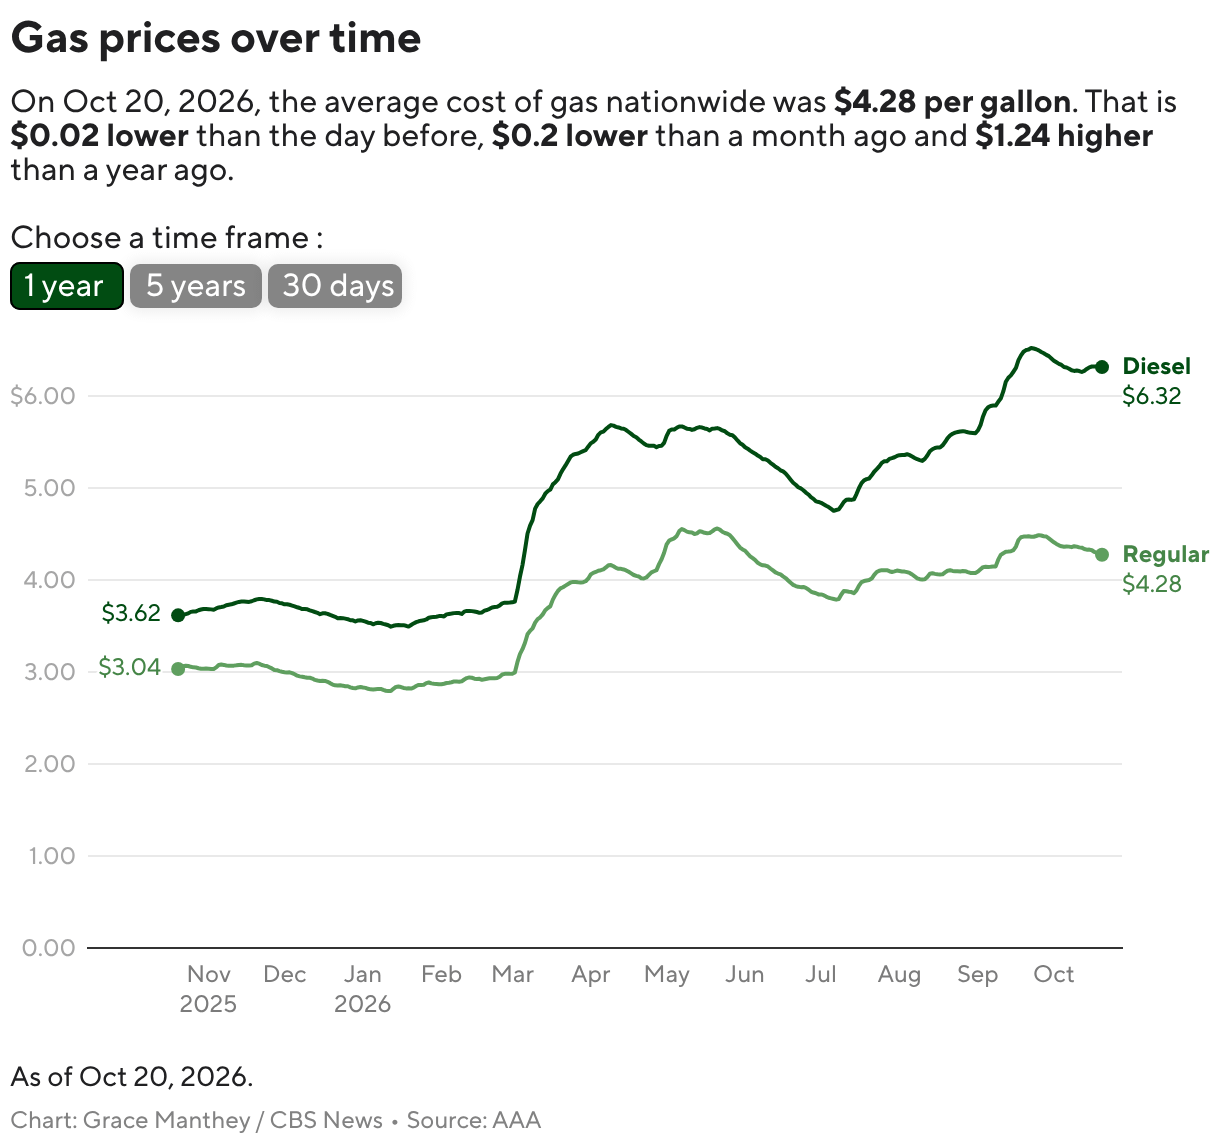
So the causal chain is direct: oil at $99 WTI and $110 Brent → expensive gasoline → hot CPI → Fed with no room to cut.
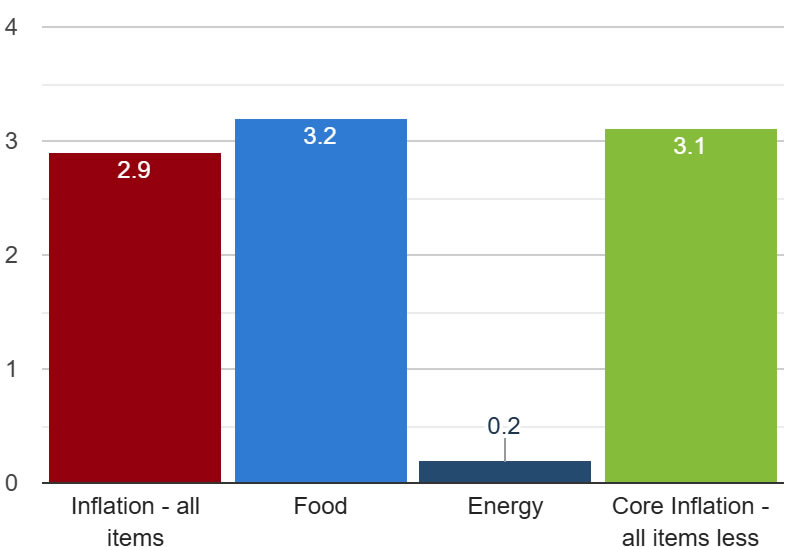
The Fed already hiked in September to **3.75%–4.00%**. Before the CPI print, traders priced about **22% odds** of another hike on October 27–28. Now it's roughly **44%–49%**. That swing happened because of energy prices, not because of jobs data or wages.
> **A hot inventory draw today = tighter supply = pressure on oil = pressure on CPI = pressure on the Fed.** 📉
That's why the entire market should care about a report that most traders file away as "energy sector noise." It isn't noise. It's an input to the thing everybody is watching.
## What's actually moving today
Crude is already soft on the day — **WTI at $99.03, down $2.76**, Brent at **$110.23** — so today's reaction will hinge on whether the EIA confirms the API's draw. A bigger-than-expected build could ease inflation worry short-term; a fifth straight draw confirms the tight-supply thesis.
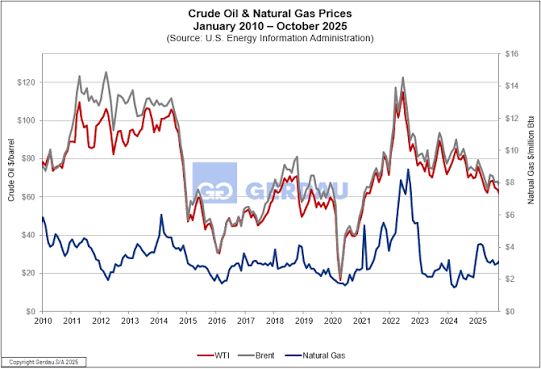
The background matters too: oil has traded above **$90 a barrel** for most of the past two months amid the war between the U.S. and Iran, and U.S. crude stocks are already **3% below the five-year average**.
## The coins in focus
Crypto tracks this more tightly than most people assume — and the reason is mechanical: a **5.3% risk-free Treasury yield** competes directly with Bitcoin, which pays nothing.
- **Bitcoin (BTC)** — $82,142, down 1.5% on the hot CPI. The cleanest read on Fed expectations.
- **Ethereum (ETH)** — $2,440, down 2.8%. Higher beta, deeper drawdown.
- **Solana (SOL)** — down 1.9%.
- **XRP** — down 1.3%.
Total crypto market cap shed 0.7% to **$2.8 trillion**. The S&P fell 0.6% and Nasdaq 0.8% on the same news — crypto just swings harder because of liquidation cascades.
The 2-year yield jumped roughly **10 basis points to 4.9%**, and the 10-year climbed to about **5.3%**, near 24-year highs. *That* is the number crypto trades against, and it's downstream of oil.
## What's coming next
Thursday brings the **Producer Price Index** — the cleaner read on whether energy costs are bleeding into business pricing. Then the **Fed decision on October 28**.
Today's oil number is the first input into that chain. **Watch 10:30 AM ET.** 👀
#OilPrice #TrumpExpectedToOutlineCrackdownOnOverseasCryptoScams #FIL/USDT #Binance #bitcoin