

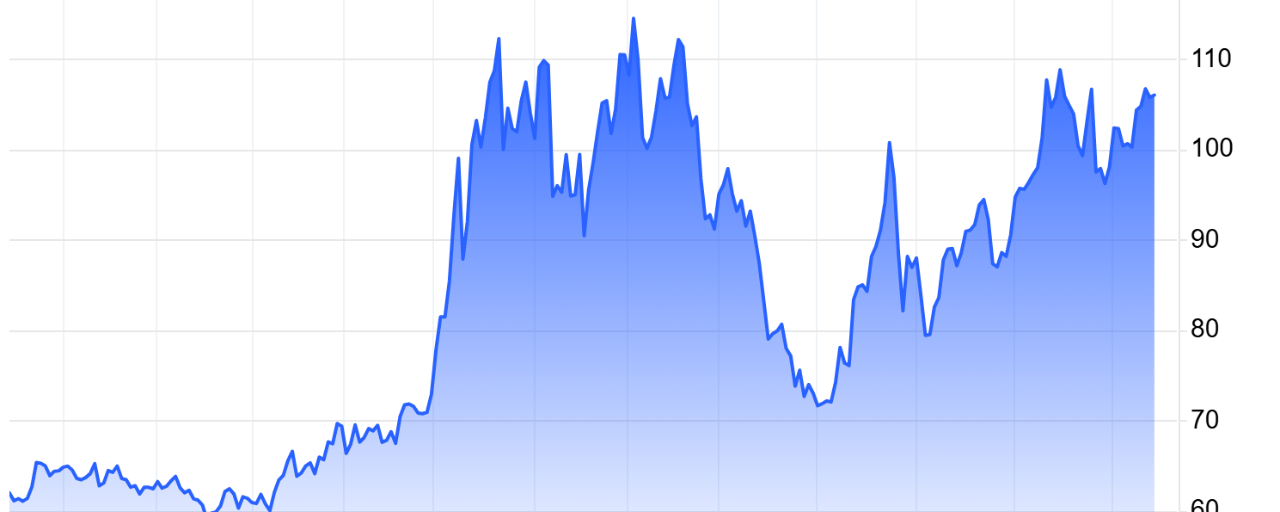
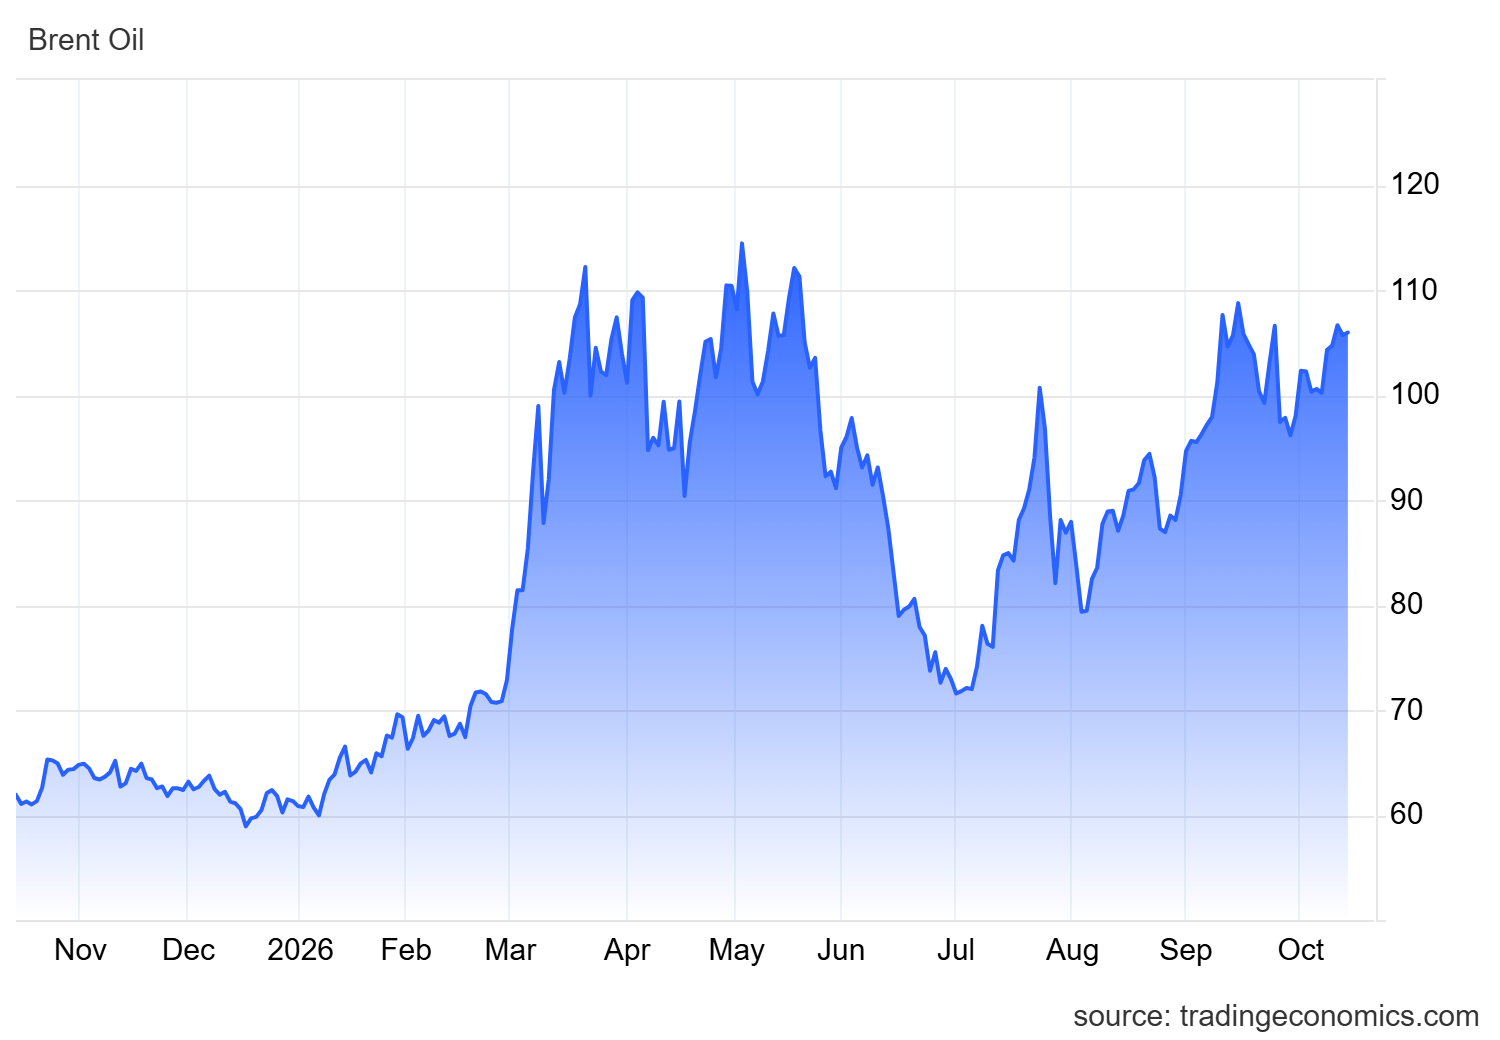
Brent crude has been trading around $105 -106 a barrel this week, still elevated after Houthi attacks on Saudi infrastructure and repeated tanker incidents near the Strait of Hormuz. Energy costs have already pushed August CPI to 3.4% YoY, and consensus now looks for September headline CPI to accelerate to around 0.6% MoM / 3.6% YoY when the data drops later today, largely on the back of gasoline prices that jumped roughly 7% last month.
A hotter-than-expected print would reinforce the idea that the Fed’s September hike (to 3.75 – 4.00%) was not a one-off. Markets are already pricing additional tightening, which has kept the 10-year Treasury yield hovering near 5.20%, multi-decade highs. Higher yields mean lower bond prices, so the path for long-duration Treasuries remains under pressure as long as oil stays sticky and the energy component of CPI refuses to cool.
My current bias:
Watching BZUSDT for further oil upside if supply disruptions persist.
Cautious on long Treasuries (prefer TBT exposure over TMFUSDT if CPI prints hot).
Keeping dry powder in RWUSD for the yield while waiting for clearer Fed signals.
Will September CPI come in hotter than expected and keep oil climbing, or will shelter and core finally give the Fed breathing room? Data in a few hours will decide the next leg for both oil and Treasuries.