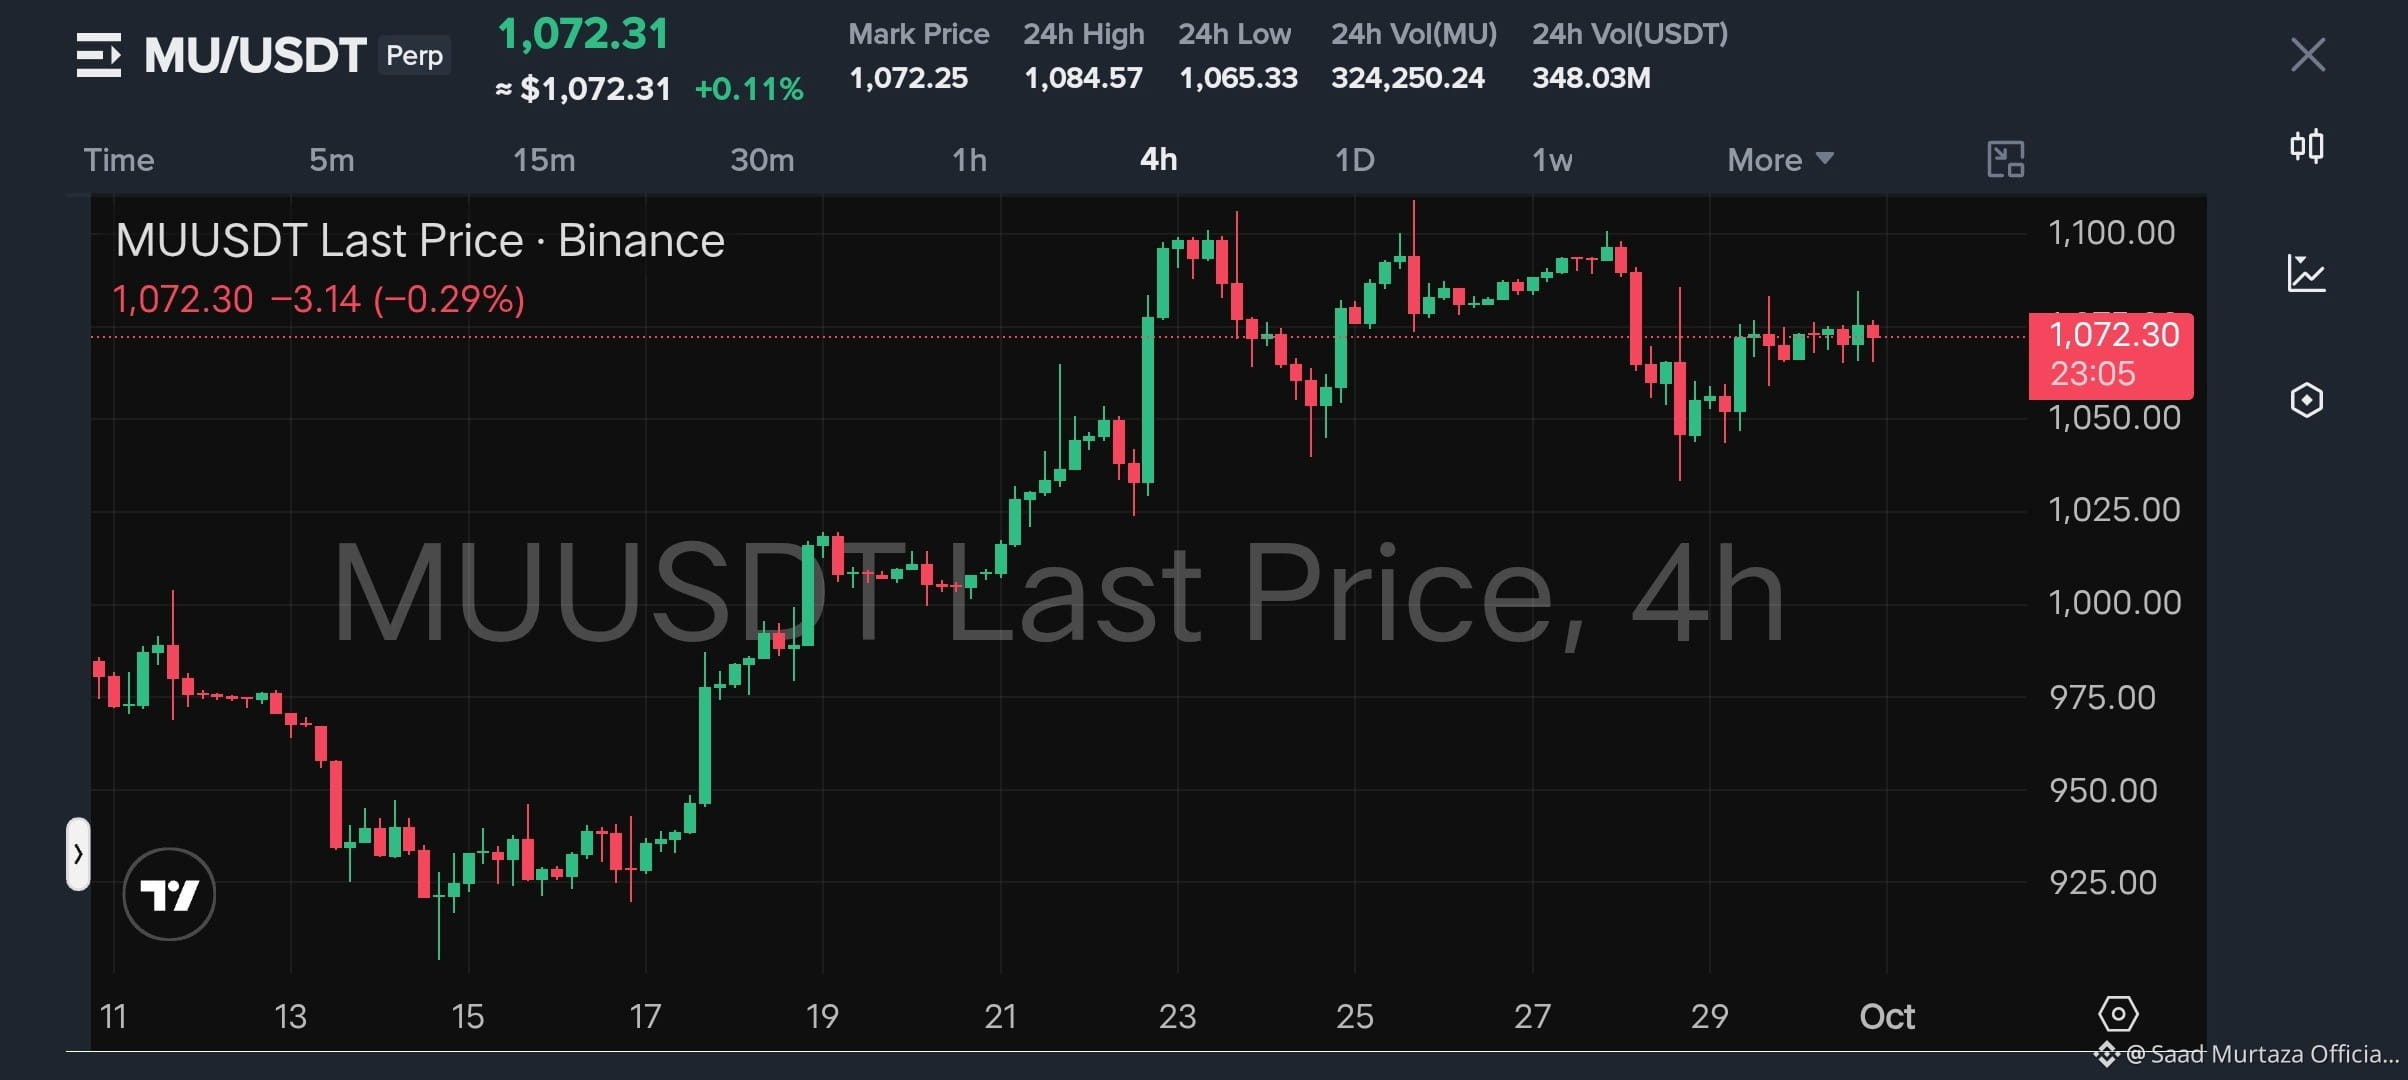
$MU is heading into Q4 earnings with expectations already extremely high. Micron guided for roughly $50B revenue and 86% non-GAAP gross margin, while consensus is around $51B revenue and ~$31.5 EPS.
I’m bullish, but cautious. The AI-driven memory shortage remains the key catalyst, and analysts see supply-demand tightness extending into 2027. HBM demand and higher DRAM/NAND pricing could keep margins elevated.
For my MU trade, I’d avoid chasing the pre-earnings move. I’d rather keep risk controlled and react to the earnings gap + guidance. A beat with stronger-than-expected margin guidance would favor continuation; a strong quarter with weaker forward guidance could trigger a sharp sell-the-news move.
My bigger question: can an 86%+ gross margin actually be sustained? If pricing stays tight and HBM keeps taking capacity, the memory super cycle may have considerably more runway than previous cycles.
Bias: Bullish above key support, but I’ll let post-earnings price action confirm the trade.
$MOVR
$SOON
#EarningsSeason #MU #Micron #Stocks #AI