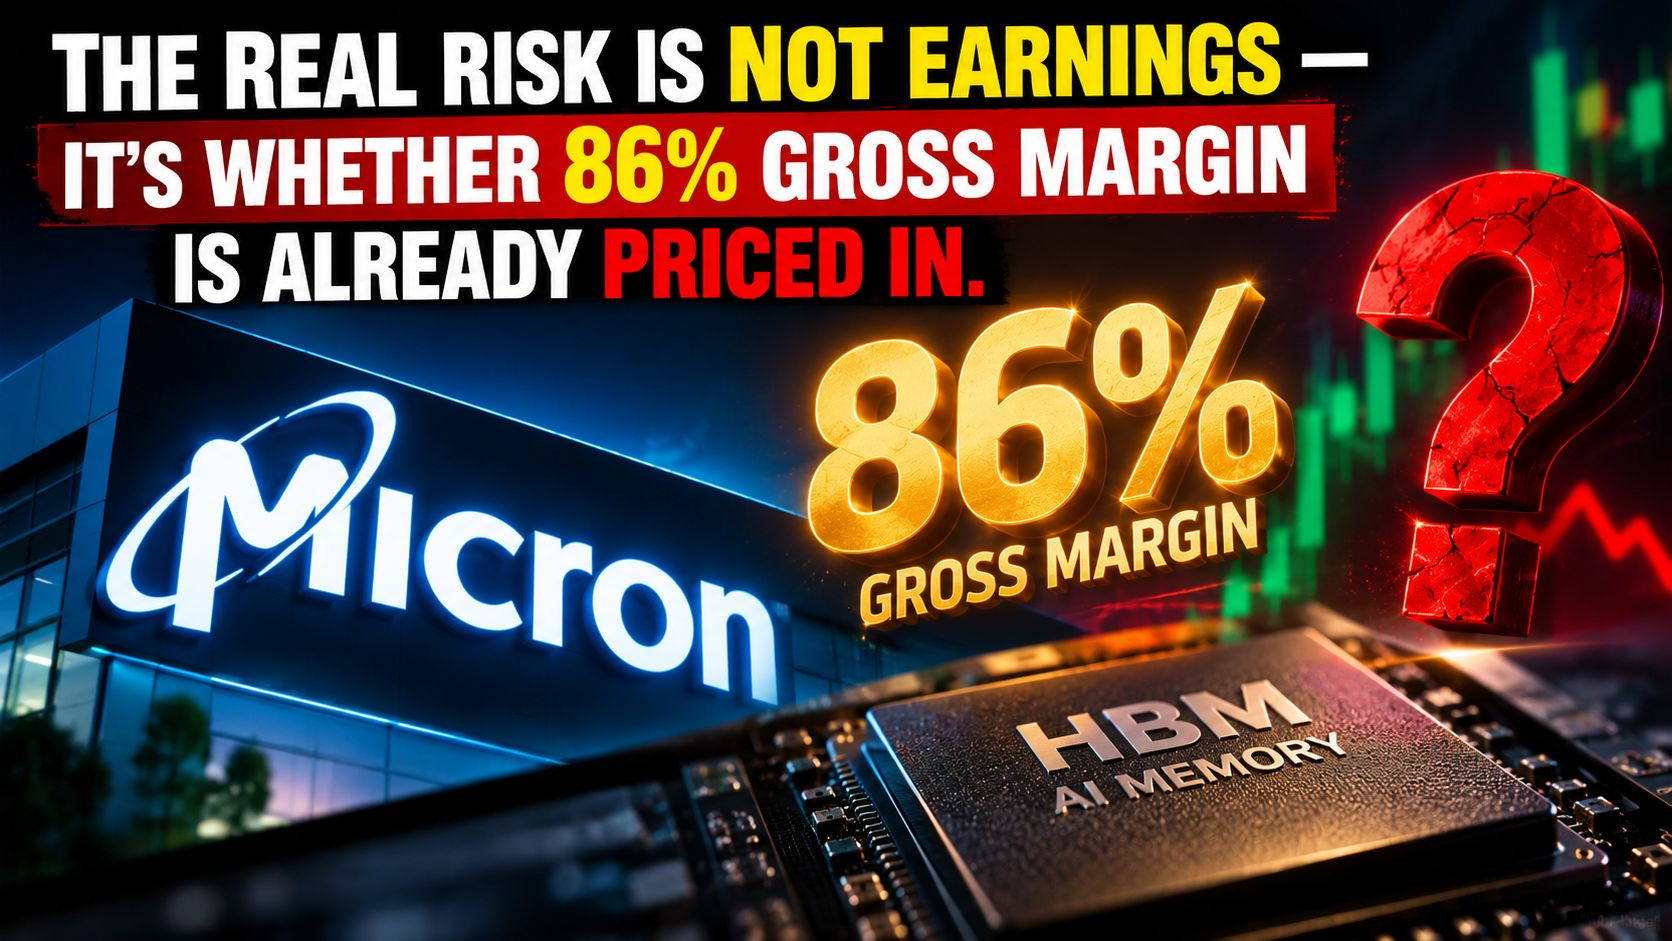
🚨 THE REAL RISK IS NOT EARNINGS — IT’S WHETHER 86% GROSS MARGIN IS ALREADY PRICED IN.
Micron heads into FY2026 Q4 earnings with one of the strongest setups in the entire semiconductor space.
Management is guiding for roughly:
Revenue: ~$50B
Gross margin: ~86%
EPS: ~$31
That sounds incredibly bullish.
But that’s exactly why the setup is dangerous.
MU has already run hard, AI memory demand is no longer a surprise, and HBM strength is now part of the base case.
So the market may not reward Micron simply for delivering “good” numbers.
It may need another upside surprise.
For me, the key question is simple:
Can Micron push gross margin above 86% and still guide higher?
If yes, the memory supercycle narrative stays alive.
If not, even a strong quarter could trigger a sell-the-news move.
I’m watching the reaction, not just the headline.
$MU $NVDA.US $SNDK.US
#EarningsSeason #ECBToTestAIAgentsInDigitalEuroPayments #StrategyAdds1666BTCHoldingsReach847666 #NvidiaApproves$150BBuyback #OpenAIDelaysGPT6.1OverSafetyIssues