#EarningsSeason
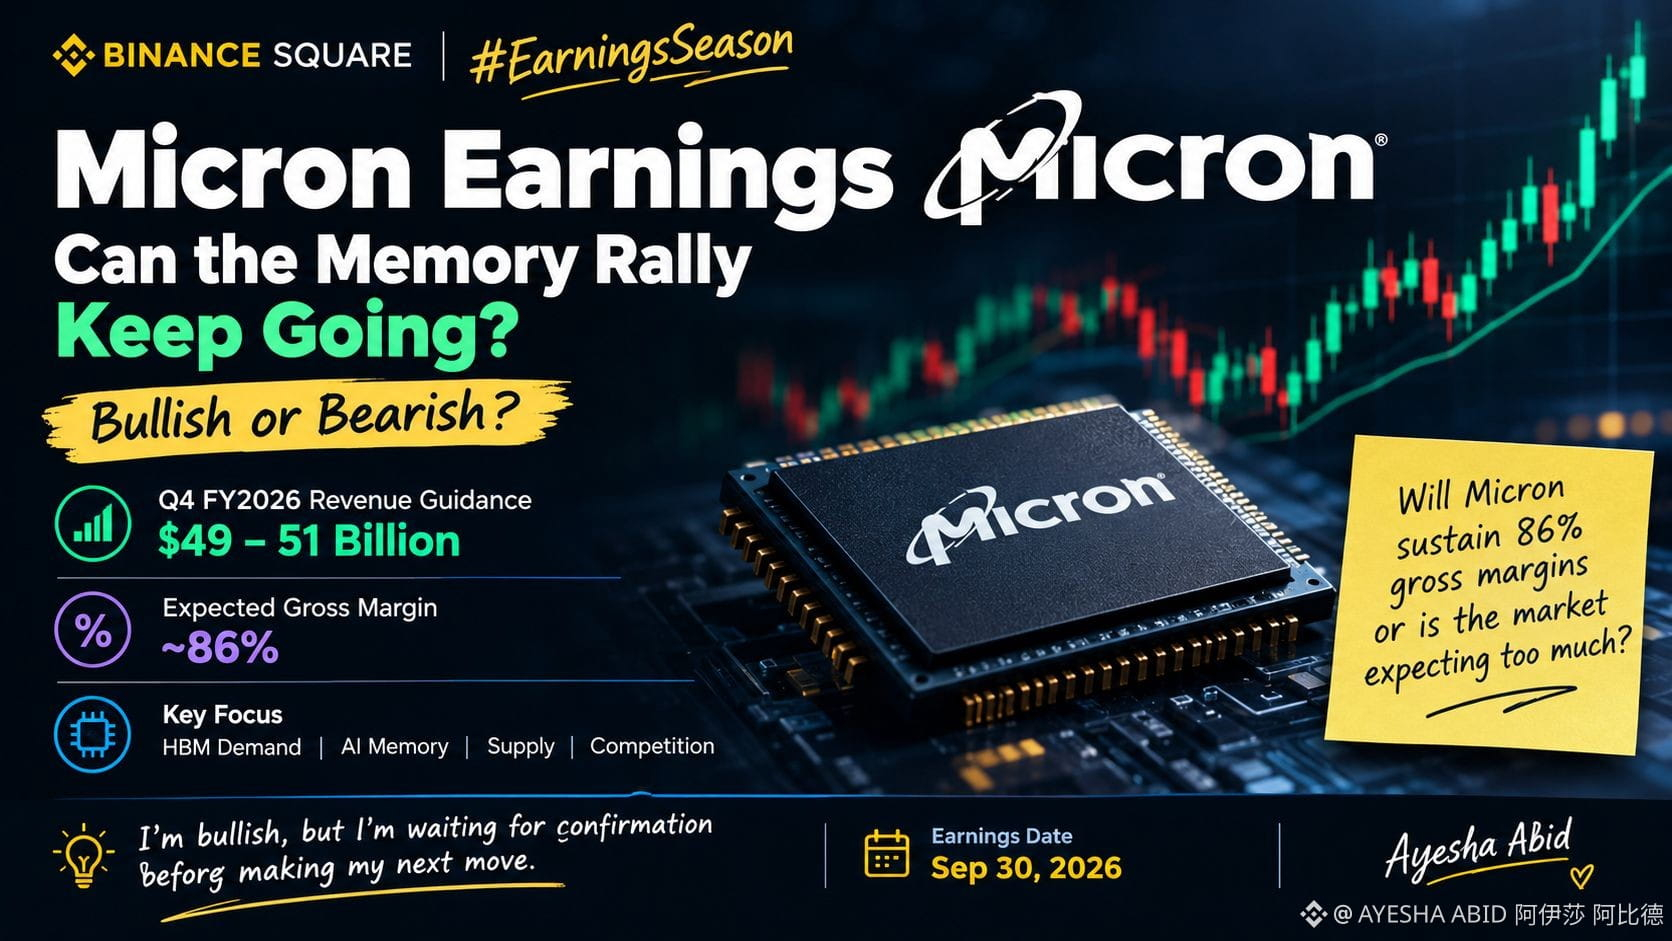
Micron Earnings: Can the Memory Rally Keep Going? 📊
My stance: Bullish on $MU , but I’m waiting for confirmation before making my next move.
Micron’s Q4 FY2026 earnings could reveal whether the AI memory boom still has room to grow. The company’s revenue guidance of $49–51 billion and expected gross margin of approximately 86% set a high bar for this report.
I’ll be watching three key factors: revenue growth, HBM demand, and forward guidance. Can Micron actually deliver those margins while maintaining strong demand for AI memory?
The bigger question is how long this memory supercycle can last. AI infrastructure continues to drive demand, but pricing, supply expansion, and competition will determine whether this growth is sustainable.
My trading plan is simple: I won’t chase a pre-earnings rally. I’ll watch how $MU reacts to the results, check volume and price action, and look for confirmation before adjusting my position. Strong earnings could support further upside, while disappointing guidance could trigger profit-taking.
$MU
Can Micron sustain 86% gross margins, or is the market expecting too much?
#Micron #MU