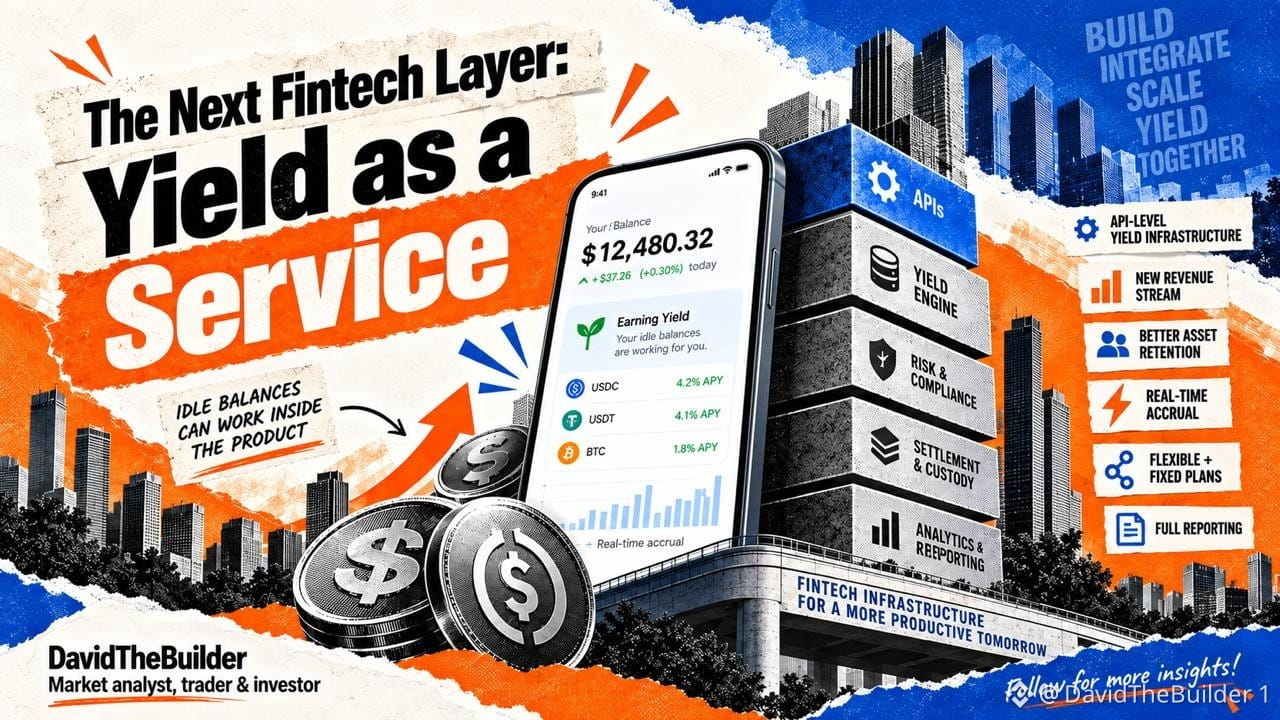
What If Every Fintech Balance Could Earn Yield? 👀 If the $BTC fintech market moves nearly as fast as AI, we might soon need a separate speed limit just to keep up with new product releases. Every day, new infrastructure changes what modern financial platforms can offer. One trend I’m watching closely right now is Yield as a Service. ➡ Not long ago, a fintech app, neobank, or payroll platform that wanted to pay users interest on idle balances had no shortcut: build an in-house treasury desk, hire risk managers, navigate securities or crypto regulation, and absorb a pile of legal complexity that has nothing to do with the core product. Yield as a Service offers a different approach. Instead of building the entire yield layer internally, platforms can integrate infrastructure that handles much of the operational complexity behind it. And the market is already taking shape: 1️⃣ OpenTrade │ $600M+ transaction volume processed │ $300M+ total value locked │ Stablecoin yield infrastructure embedded into fintech products https://www.opentrade.io/?utm_source=coinmarketcap&utm_medium=opent_davidb&utm_campaign=post 2️⃣ WhiteBIT Yield-as-a-Service │ Revenue-sharing model │ Real-time yield accrual │ Flexible + Fixed plans │ Support for 80+ assets │ Full reporting for finance teams https://institutional.whitebit.com/yield-as-a-service?utm_source=coinmarketcap&utm_medium=yaas_davidb&utm_campaign=post What interests me most is what happens when yield becomes an API-level product feature rather than a separate financial business a company needs to build.💡 For fintechs, that could mean a new revenue stream and better asset retention. For users, it means balances that can potentially work without leaving the product they already use. Disclaimer: This is not financial or investment advice. DYOR before making any decisions. Use at your own risk. #BTC Price Analysis# #Bitcoin Price Prediction: What is Bitcoins next move?#

Veröffentlichen
Haftungsausschluss: Enthält Meinungen von Drittanbietern. Keine Beratung. Binance AI wird ohne Gewähr bereitgestellt. Siehe AGB.