Oracle has a pretty interesting earnings setup coming up.
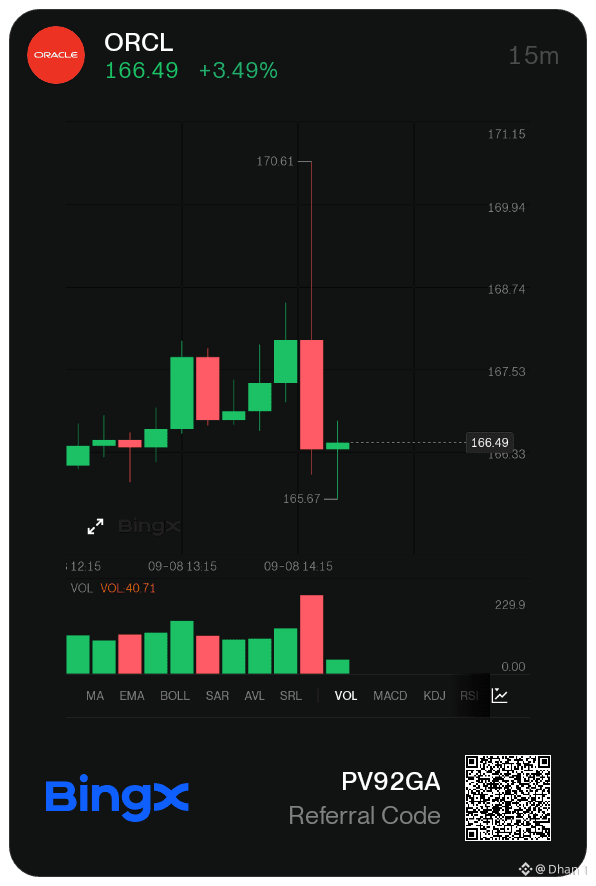
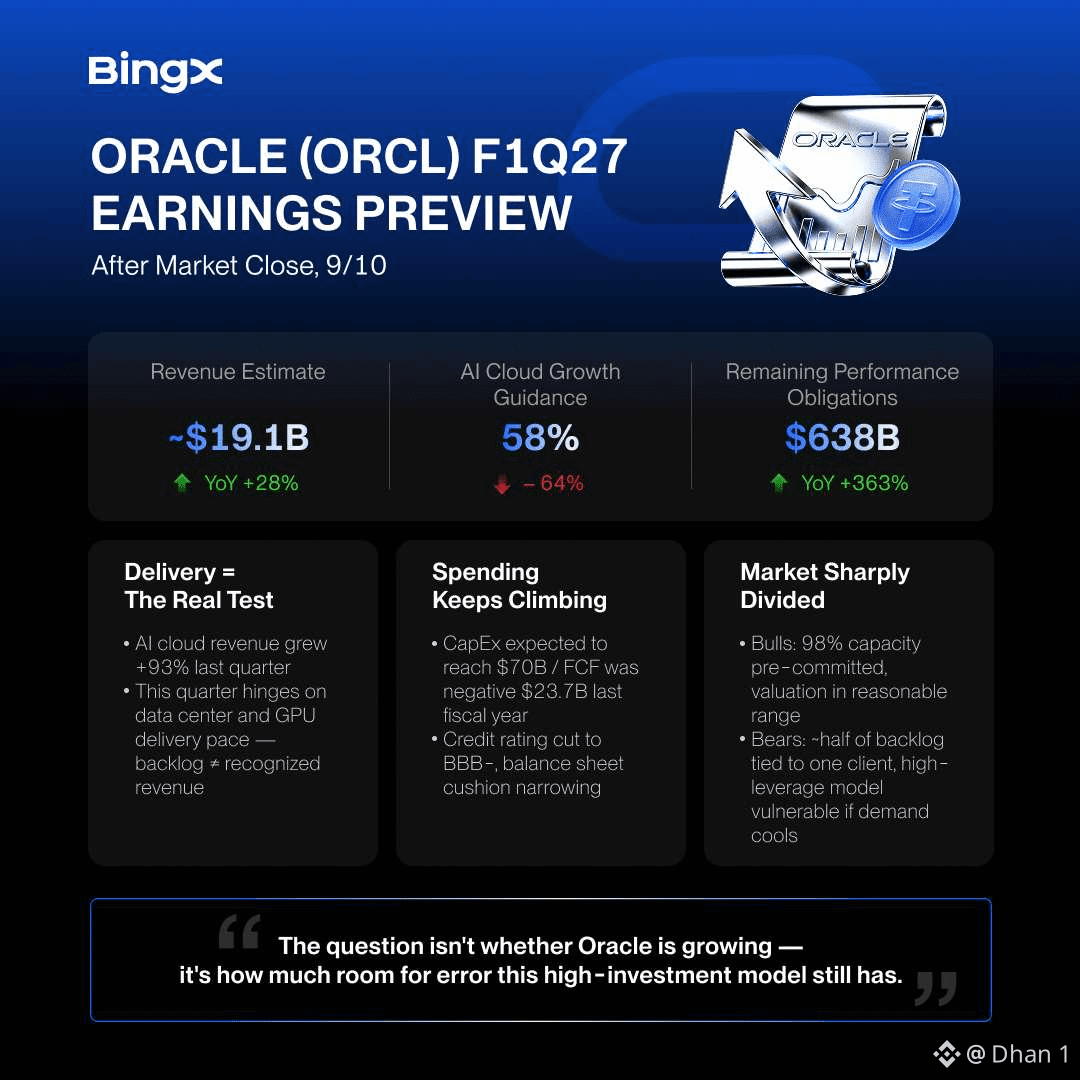
$ORCL reports F1Q27 earnings after the market closes on September 10, and the $638B backlog immediately stands out.
AI Cloud revenue grew 93% last quarter, which shows how much demand Oracle is getting from the AI infrastructure boom.
But the other side is worth watching too: around $95B in debt and roughly $70B in expected CapEx.
So for me, the big question isn't just whether Oracle beats revenue estimates.
Can the company keep growing fast enough to justify how much it's spending?
What do you think matters more for this earnings reaction, Oracle's massive backlog or the rising cost of delivering it?
#BingX #Macro Insights# $BTC
$ORCL reports F1Q27 earnings after the market closes on September 10, and the $638B backlog immediately stands out.
AI Cloud revenue grew 93% last quarter, which shows how much demand Oracle is getting from the AI infrastructure boom.
But the other side is worth watching too: around $95B in debt and roughly $70B in expected CapEx.
So for me, the big question isn't just whether Oracle beats revenue estimates.
Can the company keep growing fast enough to justify how much it's spending?
What do you think matters more for this earnings reaction, Oracle's massive backlog or the rising cost of delivering it?
#BingX #Macro Insights# $BTC