

Under Internal Revenue Service (IRS) guidelines, cryptocurrency is legally classified as property, not fiat currency. This fundamental distinction dictates how trades are handled.
When you trade one cryptocurrency for another on an exchange (e.g., swapping Bitcoin for Ethereum, or trading an altcoin for a stablecoin like USDT), the IRS treats the transaction as a two-step financial event:
You are treated as having sold your original cryptocurrency at its current fair market value.
You are treated as having used those proceeds to purchase the new cryptocurrency.
Key Rules for Crypto-to-Crypto Trades
1. Every Swap is a Taxable Disposal
Because trading one digital asset for another counts as a "disposition" of property, every single crypto-to-crypto trade is a taxable event. This applies even if:
No U.S. dollars or fiat currency ever changed hands.
The trade occurred entirely within an exchange, and no funds were withdrawn to a bank account.
You immediately lost money on the subsequent trade.
2. How to Calculate Capital Gain or Loss
For each trade, you must calculate your capital gain or loss in U.S. dollars using this formula:
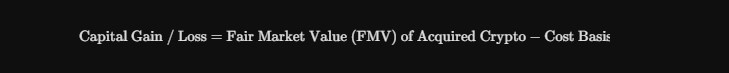
Fair Market Value (FMV): The U.S. dollar value of the coin you received at the exact minute the trade executed on the exchange.
Cost Basis: What you originally paid to acquire the coin you traded away (including any purchase fees).
Example: If you bought 1 Bitcoin (BTC) years ago for a cost basis of $10,000, and later traded that Bitcoin for Ethereum (ETH) when BTC's market value reached $60,000, you have triggered a $50,000 taxable capital gain in the year of the trade, even though you only hold ETH now.
3. Short-Term vs. Long-Term Holding Periods
The tax rate applied to your capital gain depends on how long you held the original asset before trading it away:
Short-Term Capital Gains: If you held the asset for one year or less, the gain is taxed at ordinary income tax rates (up to 37% federally).
Long-Term Capital Gains: If you held the asset for more than one year, it qualifies for preferential long-term capital gains rates (0%, 15%, or 20% depending on your total income bracket).
4. Stablecoins Are Not a Safe Haven
Trading a volatile cryptocurrency (like Solana or Cardano) into a stablecoin (like USDT or USDC) is still a taxable trade. The stablecoin is legally recognized as a distinct digital asset property, meaning any accrued appreciation up to that swap date must be realized and reported.
5. Establishing the Cost Basis for the New Coin
The fair market value of the cryptocurrency you receive during a crypto-to-crypto swap automatically becomes its new cost basis. If you later trade or sell that new coin, your next calculation starts from that dollar figure.
What is NOT a Taxable Event?
To contrast with crypto-to-crypto trades, the IRS explicitly exempts certain actions from triggering taxes:
Buying crypto with fiat currency (USD): Simply purchasing crypto with cash establishes your cost basis but is not a taxable disposal.
Transferring crypto between your own wallets: Moving coins from an exchange to your own hardware wallet (or between two wallets you own) is a non-taxable event, as long as ownership does not change.
Reporting Requirements
Taxable crypto-to-crypto trades must be reported on Form 8949 and summarized on Schedule D (Form 1040) of your federal tax return. With digital asset reporting standards, centralized exchanges also issue Form 1099-DA to report transaction histories to both you and the IRS, making accurate tracking of every individual swap critical.