


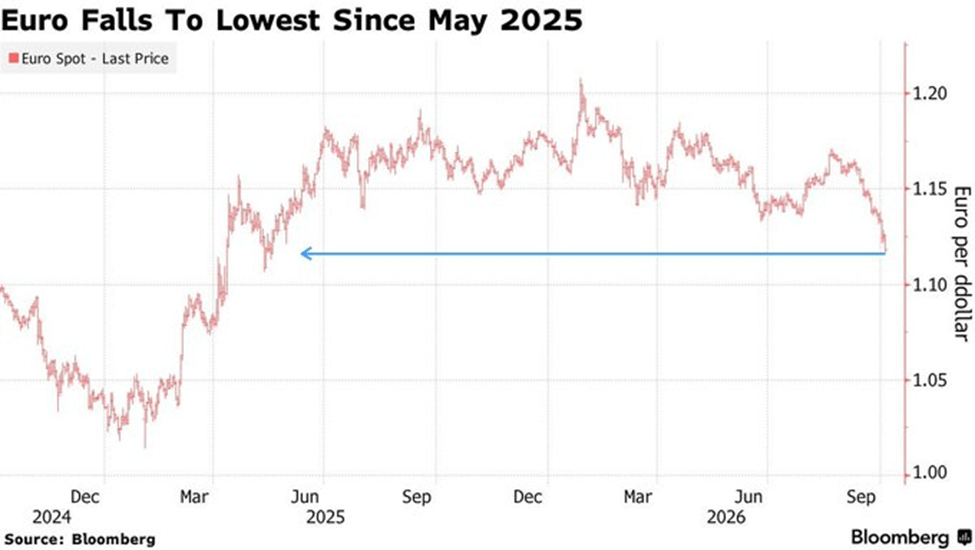
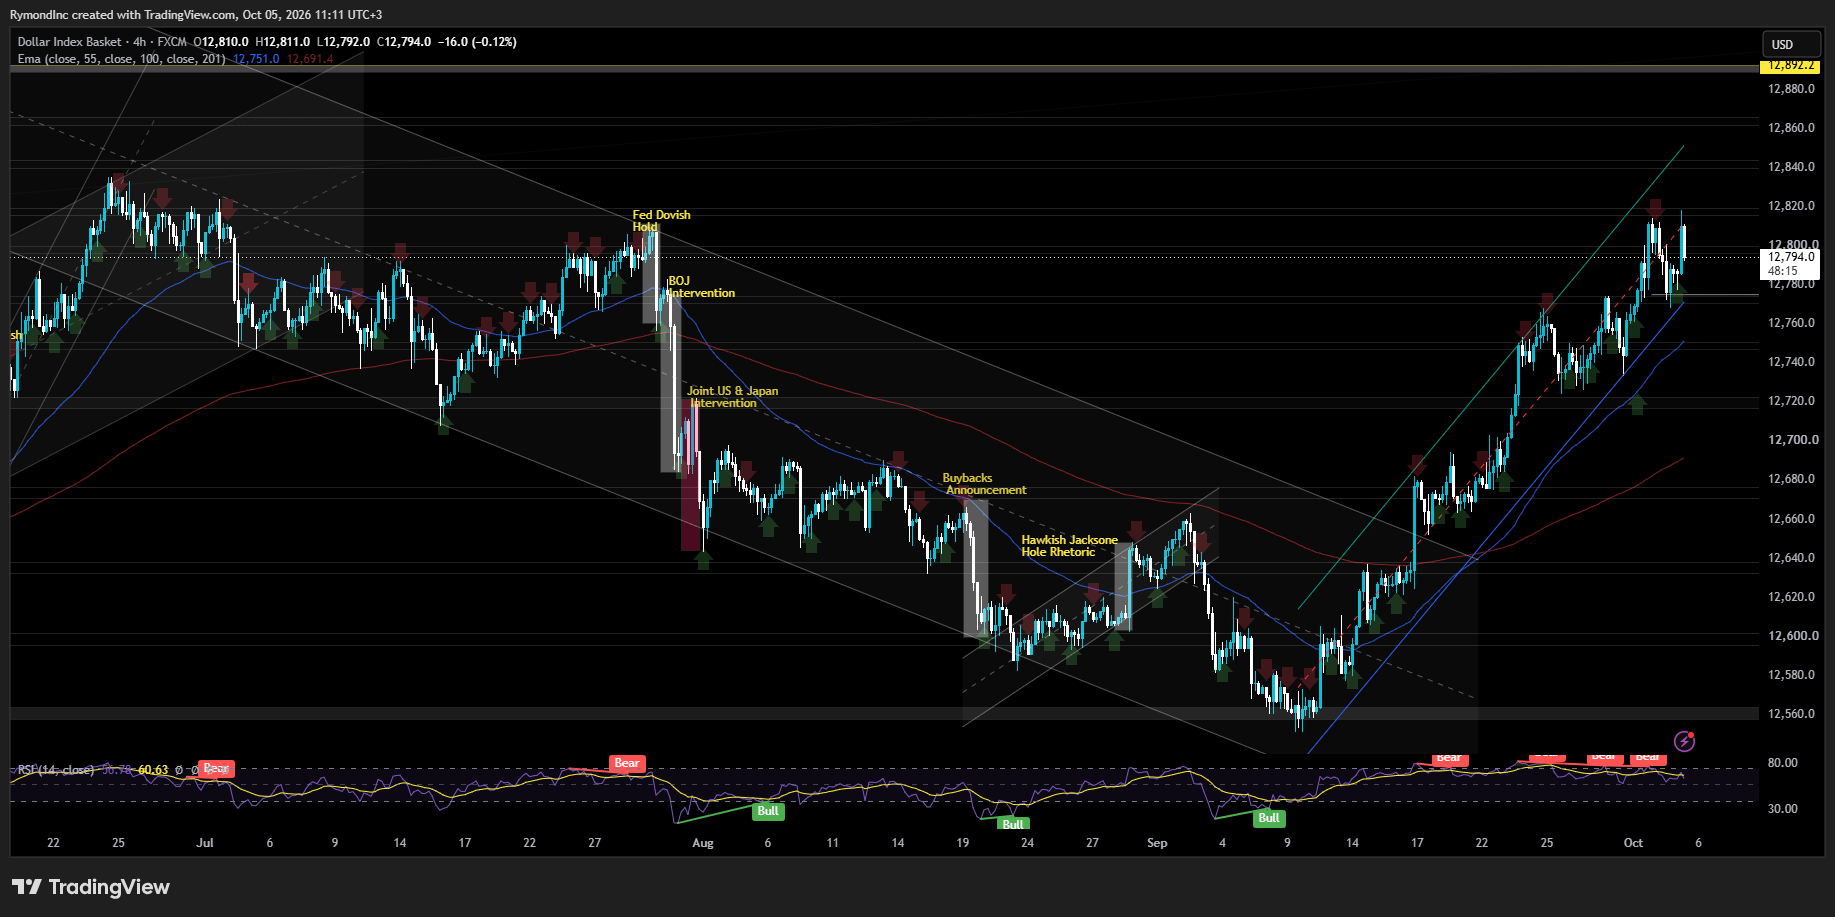
The euro dropped as low as $1.1161 in Asian trading on Monday, its weakest since May 2025 before paring back some of those loses. Reports that Spanish government officials are preparing for an early election landed on top of the worries already hanging over France's bond market. The currency was last down about 0.7% at $1.1176 after four straight weekly losses, and the dollar index rose 0.47% to 102.37, close to a 17-month high.
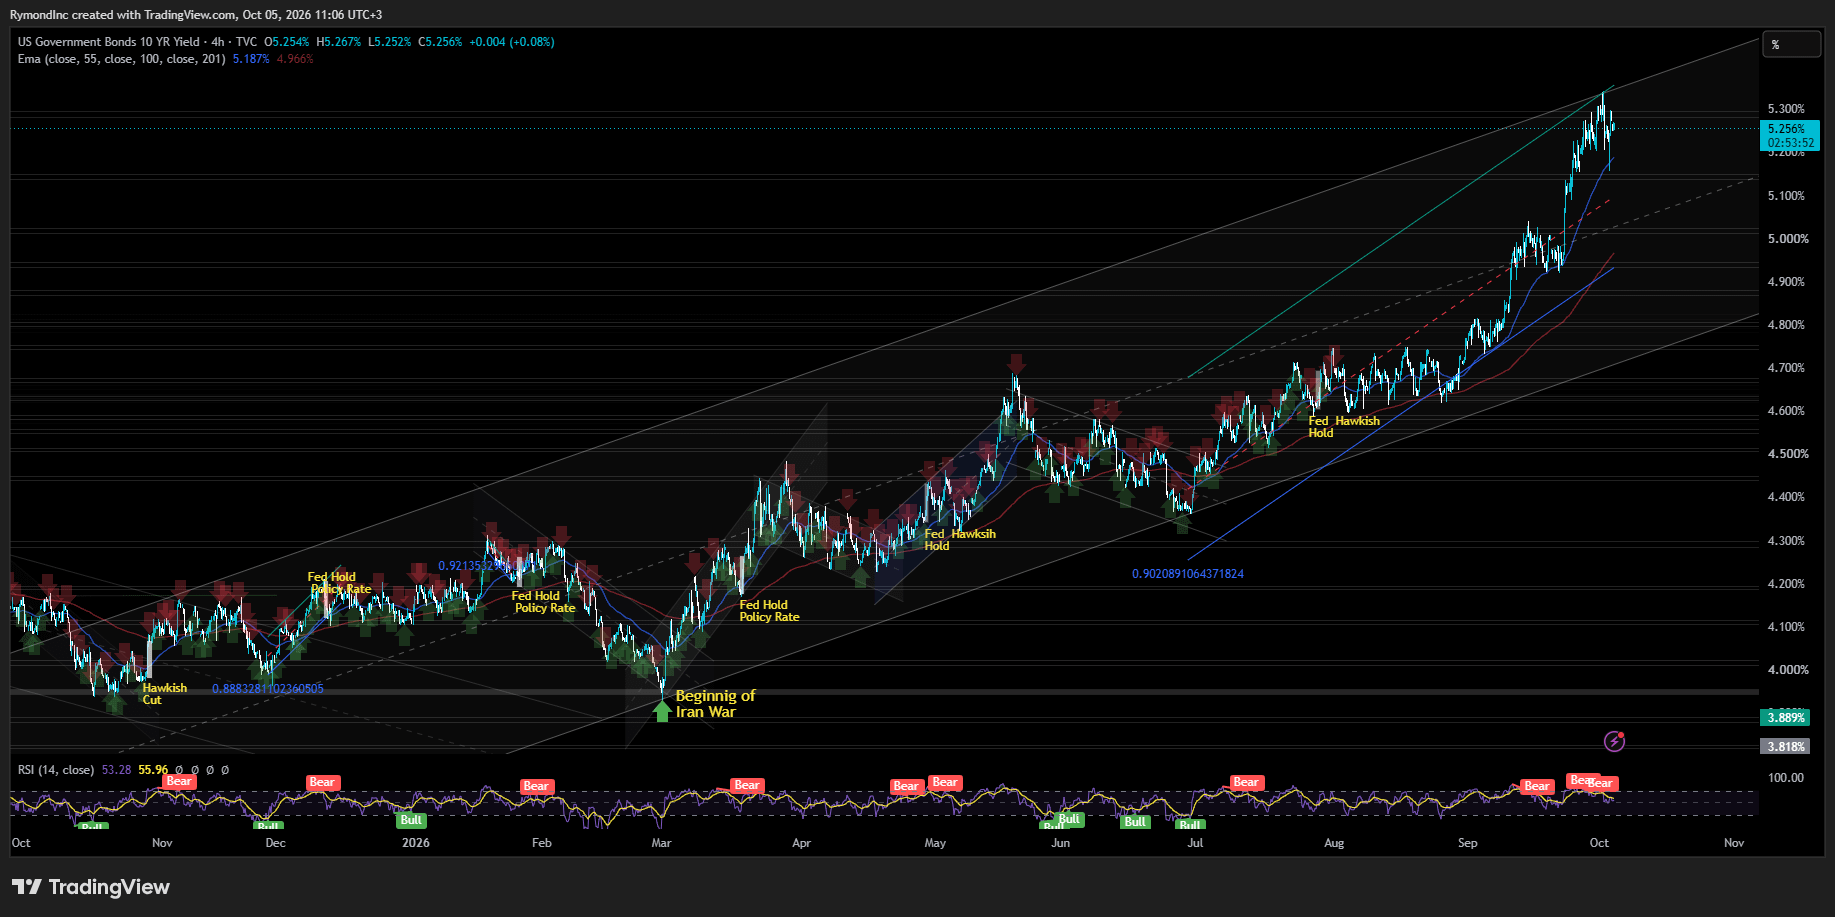
Treasury yields are holding the dollar up. The 10-year note yielded roughly 5.26%, a little under the 24-year high it hit last week, and that kept the greenback firm even though Friday's jobs report was soft. Matthew Ryan, head of market strategy at Ebury, said higher US yields and the global debt selloff are both sending safe-haven money into the dollar.
That jobs report did change the Fed picture. Payrolls grew by only 29,000 in September, and unemployment ticked up to 4.2% from 4.1%. August's gain was cut to 133,000 from 162,000. The rise in the jobless rate largely reflects a 485,000 jump in the labor force, not a surge in layoffs.
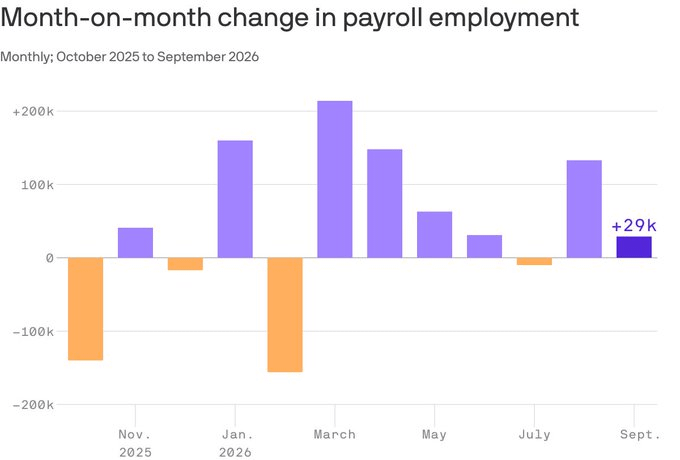
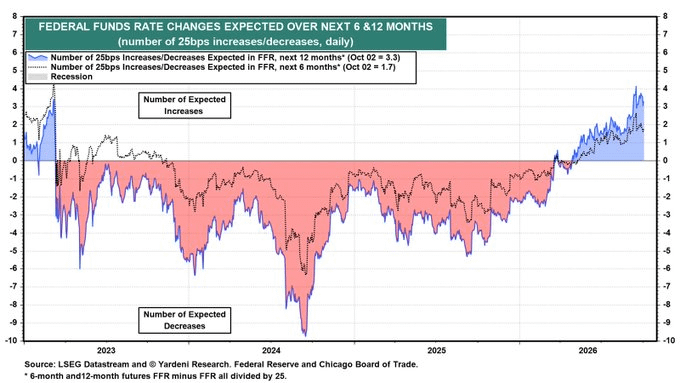
Traders now put the odds of a Fed hold in October at 78%, up from 36% a week earlier, according to CME FedWatch. They still expect a hike in December and two more in the first half of 2027. The Fed raised rates by a quarter point in September. The FFR futures market’s prediction is more hawkish than the Fed officials’ median. FFR futures imply 3.3 rate hikes over the next 12 months and 1.7 over the next six months.
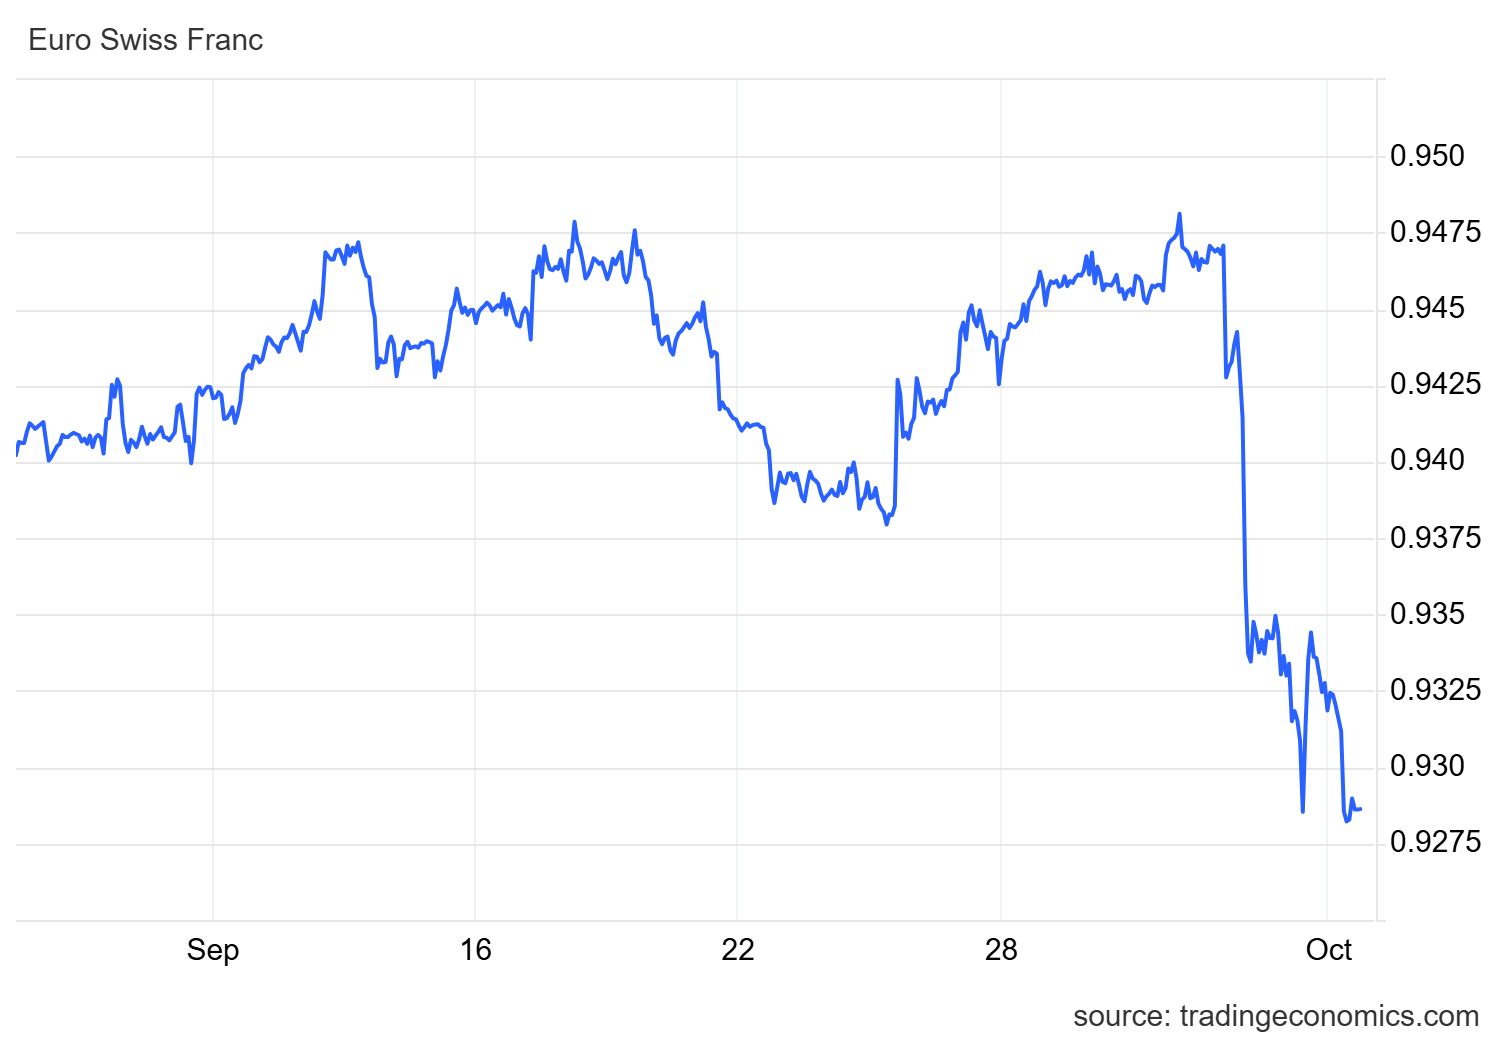
Monday's selling started in Asia. Hedge funds there sold the euro against the dollar in the cash market, according to traders, and that tripped option barriers that made the drop worse. The euro also fell 0.5% against the Swiss franc and 0.39% against sterling. It lost nearly 2.5% in September, its biggest monthly decline since July 2025, and it slipped below $1.13 on Thursday for the first time since May 2025.
Spain is the fresh problem. Three people close to Prime Minister Pedro Sánchez, who asked not to be named because the talks are private, said cabinet ministers and other senior government and Socialist Party officials think an early ballot is the best response to a heavy defeat in parliament last week.
On Friday, Congress rejected two housing decrees after Junts, a Catalan party among Sánchez's allies, refused to back them. Nothing has been decided. November 29 is the earliest possible election date, but hitting it would mean an announcement on Monday and a dissolution decree in Tuesday's official gazette. Deputy Prime Minister Yolanda Díaz said the call belongs to Sánchez alone.
France is still the bigger worry. Paris unveiled its 2027 budget on Thursday with a deficit target of 5% of GDP, down from 5.4% this year. The plan leans on about €54 billion of consolidation, including a freeze on public-sector pay and limits on pension increases, and the debt agency intends to borrow a record €340 billion next year. MUFG Research described the draft as an opening bid in a fragmented parliament, with everything up for negotiation. French 10-year yields climbed to about 4.96% on Thursday, the highest since July 2002.
The gap to Germany keeps growing. German yields fell while French yields rose, and by Bloomberg's measure the premium over bunds hit 152 basis points on Friday, last seen in 2011. LSEG data cited by Reuters had it at 140 basis points at the end of the week, a 34-basis-point jump and the biggest weekly move in 17 years. French bond futures slid 0.22% on Monday, near record lows, while German futures rose 0.1%. France now pays more than Italy or Greece to borrow for 10 years.
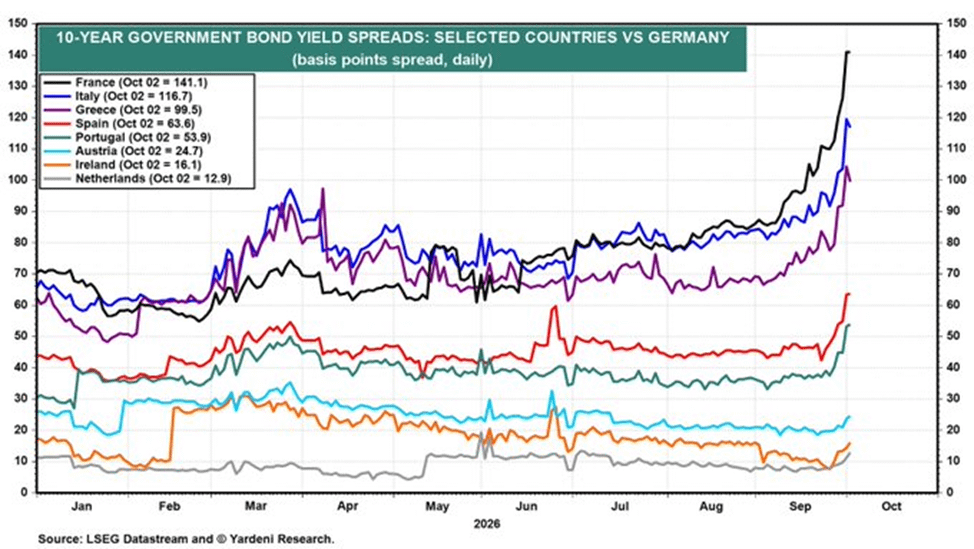
It isn't only France. Of the 22 government bond markets Bloomberg tracks, six have seen 10-year yields rise by 100 basis points or more this year. France leads at 131 basis points and the US is next at 112, followed by Italy, Indonesia, Japan and South Korea.
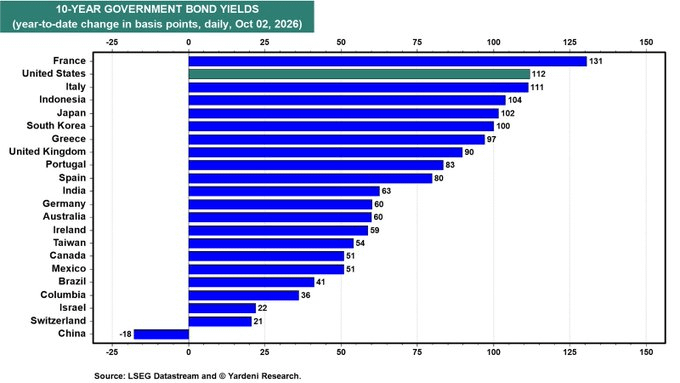
Homin Lee, senior macro strategist at Lombard Odier Singapore, said bond and currency markets are "clearly signaling investor discomfort about the rising instability of the French government." He tied that to a weakening fiscal anchor ahead of the 2027 elections. ING strategists went further and said even a fully passed budget would "not resolve France's structural fiscal problems."
How far this spreads is unclear. Chris Weston, head of research at Pepperstone, cautioned against betting on a quick rebound ("Don't stand in front of the train") and spoke of a possible whiff of contagion. Brent Donnelly, president of FX trading at Spectra Markets, said the French politics trade many expected to build over the winter has already arrived, and that budget promises don't carry much credibility with a change of power coming. Ninghui Liu at State Street Investment Management was calmer. In his view, it's still a country story, not a euro crisis, and he expects Germany to step in if the strain deepens.
The wider backdrop doesn't help. Higher oil prices and inflation are hurting an energy-importing euro zone, and Germany's chancellor faces mounting pressure after a run of regional gains for the far-right AfD. Jane Foley, head of FX strategy at Rabobank, pointed out that the ECB was one of the first G10 central banks to hike and is expected to move again, yet "the euro hasn't been able to get traction."