

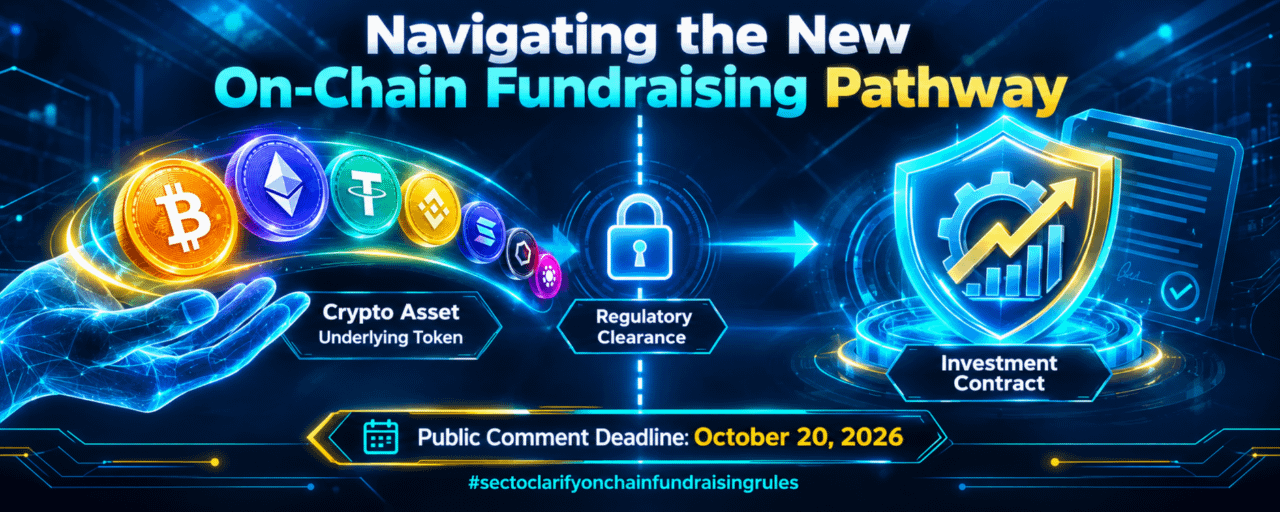
The proposal is more nuanced than “the SEC is making token fundraising legal.” The main implication is that it would create specific federal pathways for certain crypto investment-contract offerings, while preserving securities-law obligations.
What it would actually change
Two proposed fundraising exemptions:
Up to $5 million over a four-year period under a one-time exemption.
Up to $75 million in any 12-month period under a larger offering exemption.
Disclosure still matters. Projects using the exemptions would have to provide specified, principles-based disclosures. The $75M route would additionally involve financial statements and continuing reporting.
It doesn't mean “tokens are securities” or “tokens aren't securities.” The proposal distinguishes the underlying crypto asset from an investment contract surrounding its sale. That could allow an asset initially sold through an investment contract to cease being subject to that investment-contract treatment when the issuer's promised/represented essential managerial efforts have been completed or permanently ceased, subject to the proposed conditions.
There is a proposed safe harbor. Proposed Rule 400 would establish conditions under which an issuer's investment contract would cease to be treated as such for the relevant federal securities-law definitions.
What this could mean for an on-chain fundraising model
Conceptually, a project could have a clearer path like:
Project → disclosed token offering → qualifying exemption → capital raised → development/managerial commitments → potentially transition away from investment-contract treatment
But the important caveat is that the exemption is not a blanket exemption for any token sale. Eligibility, disclosures, offering limits, reporting, and the precise structure of the transaction still matter.
The proposal also seeks to preempt certain state securities registration/qualification requirements for offerings conducted under the proposed regime, which could reduce one layer of compliance complexity.
One important distinction
This is still a proposal, not a final rule. The SEC lists October 20, 2026 as the public-comment deadline.
And the SEC's September 25 FAQs are staff guidance rather than binding rules; the SEC expressly says they do not create new legal obligations.
So, in practical terms: the proposal could make compliant on-chain capital formation substantially more structured and predictable, but it does not create a free pass for token launches. The biggest questions for a particular project would be whether its offering fits one of the exemptions, what disclosures it must make, and when/if the token can separate from the investment-contract relationship.
#sectoclarifyonchainfundraisingrules #Binance
