

With the Bar—and the Stock—Already High
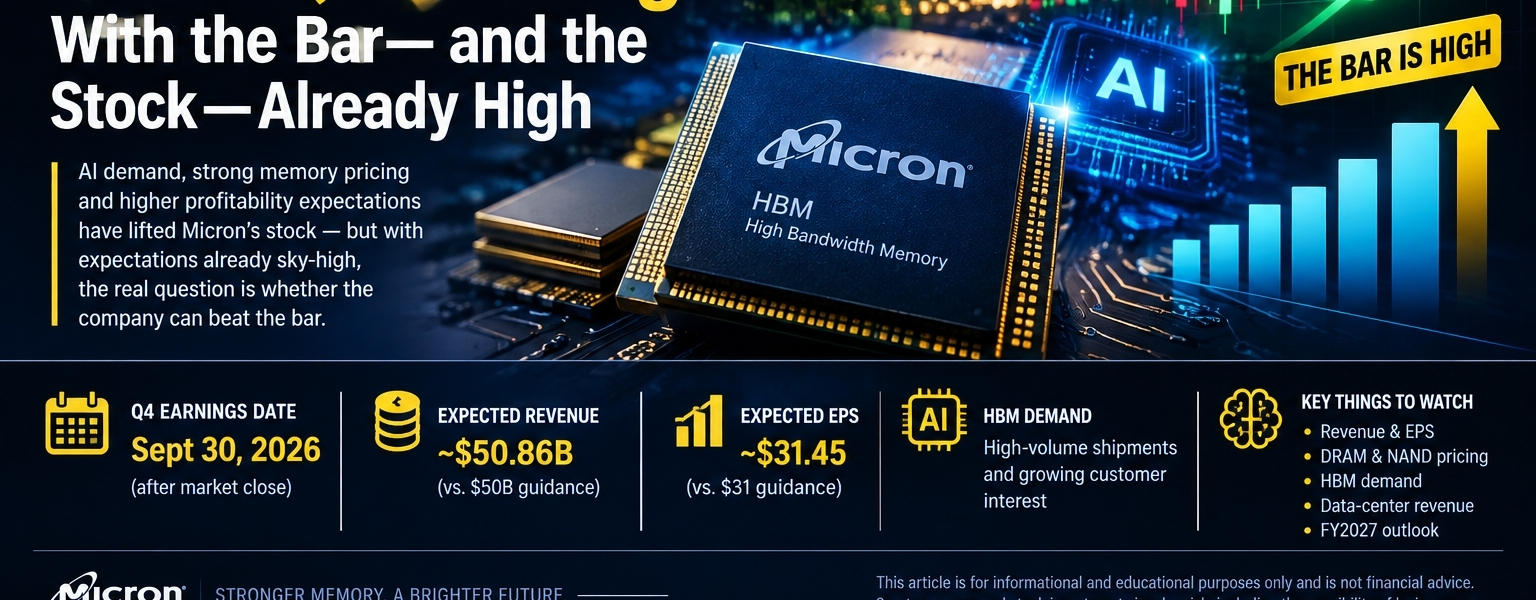
Micron Technology (NASDAQ: MU) is heading into its fiscal fourth-quarter earnings report with unusually high expectations surrounding its AI-driven memory business. The company is scheduled to release its fiscal Q4 2026 results after the U.S. market closes on September 30, 2026. (Micron Technology Investors)
High Expectations for Q4
Micron's own guidance calls for approximately $50 billion in revenue, with a range of plus or minus $1 billion. The company expects non-GAAP gross margin of about 86% and adjusted diluted earnings per share of approximately $31, plus or minus $1. (Micron Technology Investors)
Wall Street expectations are broadly around the same level. One recent consensus estimate puts Q4 revenue at approximately $50.86 billion and adjusted EPS at $31.45. Those figures would represent very substantial year-over-year growth. (Zacks)
AI Memory Remains Central
A major factor behind the optimism is demand for memory used in artificial-intelligence infrastructure. Micron has been expanding its high-bandwidth memory (HBM) business, and the company said HBM4 is already in high-volume shipments for a lead customer's platform, with qualification samples sent to additional customers. (Micron Technology Investors)
The broader memory market is also benefiting from tight supply and strong demand for data-center products. This has helped support higher pricing and margins across parts of the DRAM and NAND markets.
The Stock Has Already Moved Sharply
The challenge for investors is that strong expectations are already reflected to a significant degree in Micron's share price. Recent trading has placed MU around $1,082 per share, while the stock has experienced a major rally during 2026. (MarketBeat)
That means the earnings report may be judged not simply on whether Micron beats its previous results, but on whether its numbers and forward guidance are strong enough relative to the expectations already built into the valuation.
What Investors Will Watch
Key areas to watch when the results arrive include:
Revenue and adjusted EPS
DRAM and NAND pricing
HBM demand and production
Data-center revenue
Gross-margin performance
Capital spending plans
Management's outlook for fiscal 2027
Whether AI-related memory demand remains strong
Micron's previous quarter was also exceptionally strong: fiscal Q3 2026 revenue reached $41.46 billion, while the company reported adjusted EPS of $25.11. (Micron Technology Investors)
Bottom Line
Micron enters the September 30 earnings event with a powerful combination of AI-related demand, strong memory pricing and elevated profitability expectations. But because expectations are already high, the market's reaction could depend heavily on future guidance and the sustainability of current growth, rather than simply whether the company reports another strong quarter.
This article is for informational and educational purposes only and is not financial advice. Cryptocurrency and stock investments involve risk, including the possibility of losing money.