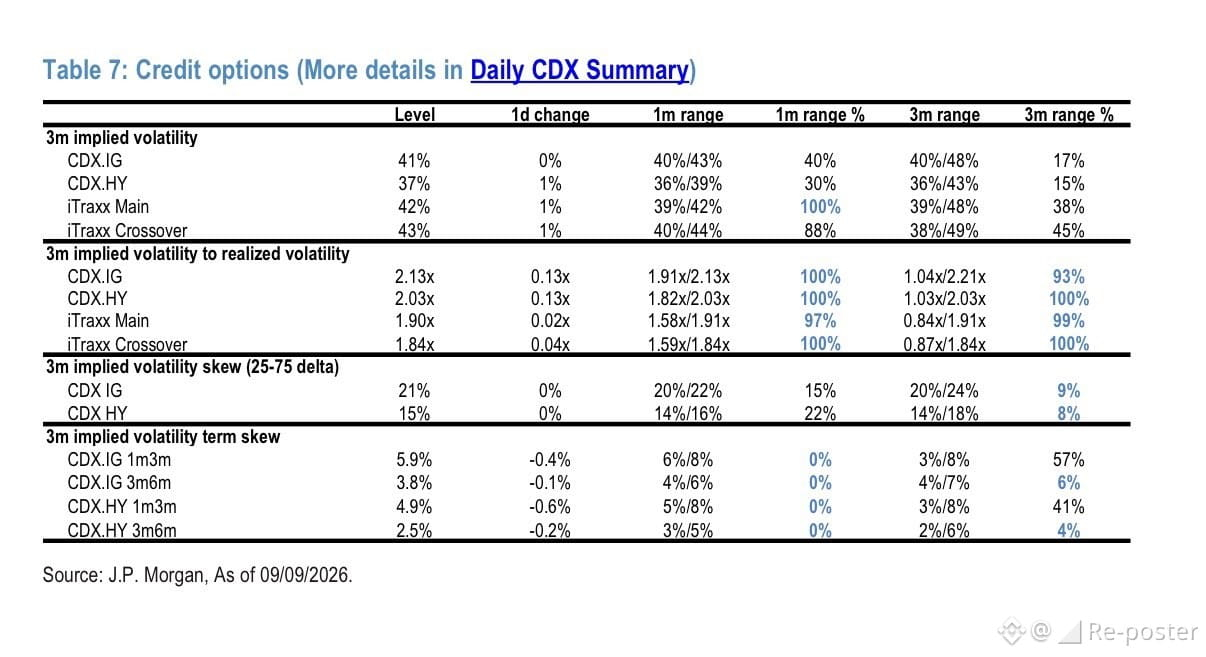
CDX.IG implied-to-realized vol ratio hits 100th percentile of 1m range at 2.13x; CDX.HY ratio at 100th percentile of 3m range at 2.03x
Credit options vol is stretched relative to realized in both IG and HY as of 10 September 2026, per J.P. Morgan's daily credit strategy.
The 3-month implied-to-realized volatility ratio for CDX.IG stands at 2.13x, at the 100th percentile of the 1-month range and the 93rd percentile of the 3-month range.
CDX.HY is at 2.03x, also at the 100th percentile of both its 1-month and 3-month ranges.
Credit options vol is stretched relative to realized in both IG and HY as of 10 September 2026, per J.P. Morgan's daily credit strategy.
The 3-month implied-to-realized volatility ratio for CDX.IG stands at 2.13x, at the 100th percentile of the 1-month range and the 93rd percentile of the 3-month range.
CDX.HY is at 2.03x, also at the 100th percentile of both its 1-month and 3-month ranges.