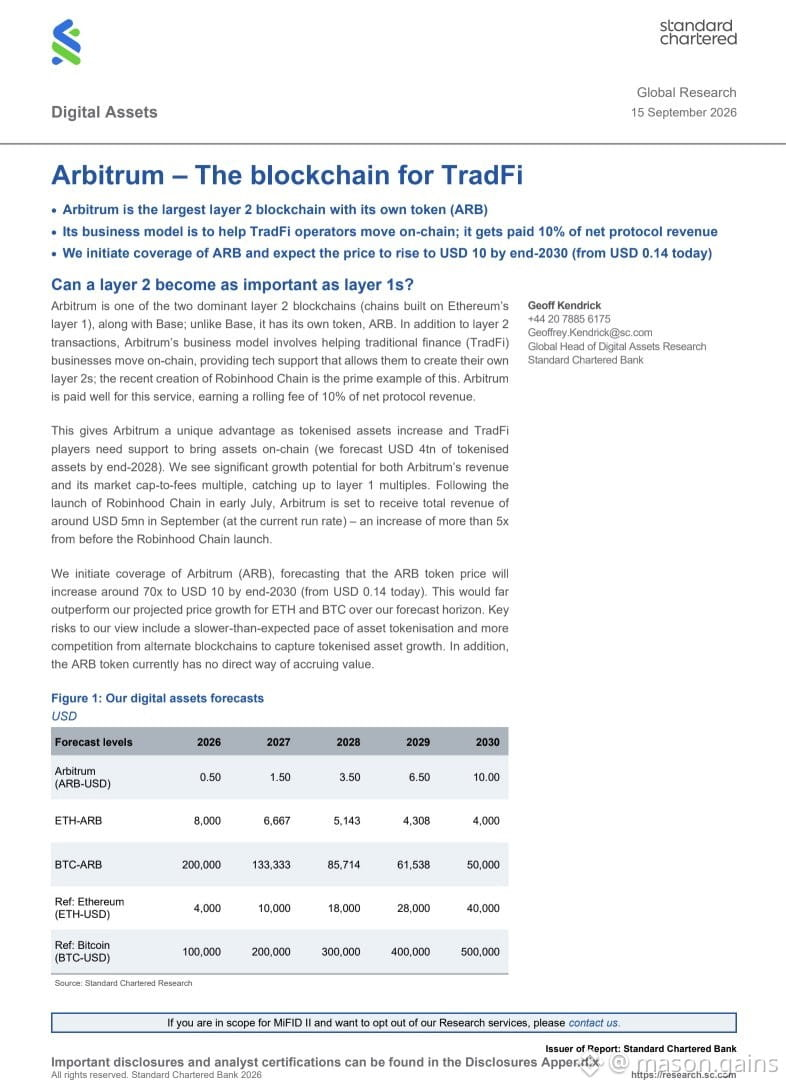
Standard Chartered just dropped a nuclear take: $ARB from $0.14 → $10 by 2030. That's a 70x.
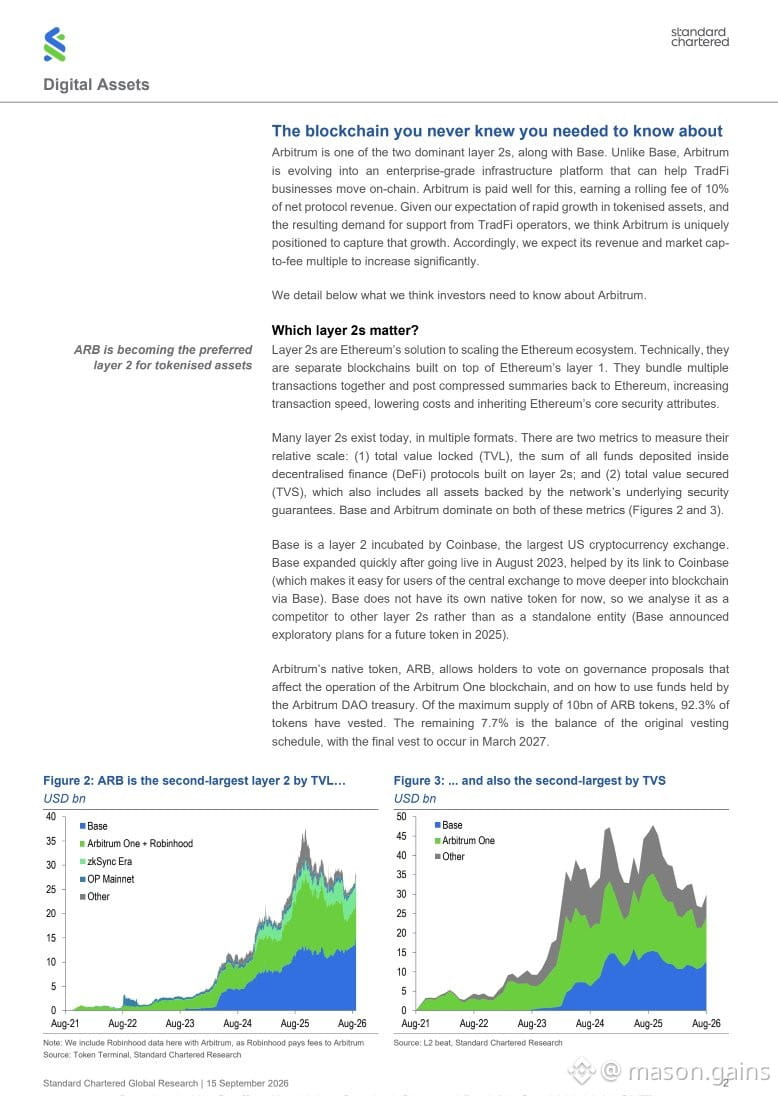
Their thesis? Arbitrum's rev-share model. They take 10% of net protocol revenue from every L2 built on their stack (Robinhood, TradFi rails coming onchain). As tokenized assets hit $4T by 2028, Arbitrum becomes the infrastructure play for RWAs.
Their price ladder:
$0.5 in 2026
$1.5 in 2027
$3.5 in 2028
$6.5 in 2029
$10 in 2030
We're at $0.14. To hit their 2026 target in 3 months? $ARB needs a 3.5x.
TradFi banks pricing in L2 dominance. Arbitrum's bet: own the rails, not just the chain.
Their thesis? Arbitrum's rev-share model. They take 10% of net protocol revenue from every L2 built on their stack (Robinhood, TradFi rails coming onchain). As tokenized assets hit $4T by 2028, Arbitrum becomes the infrastructure play for RWAs.
Their price ladder:
$0.5 in 2026
$1.5 in 2027
$3.5 in 2028
$6.5 in 2029
$10 in 2030
We're at $0.14. To hit their 2026 target in 3 months? $ARB needs a 3.5x.
TradFi banks pricing in L2 dominance. Arbitrum's bet: own the rails, not just the chain.