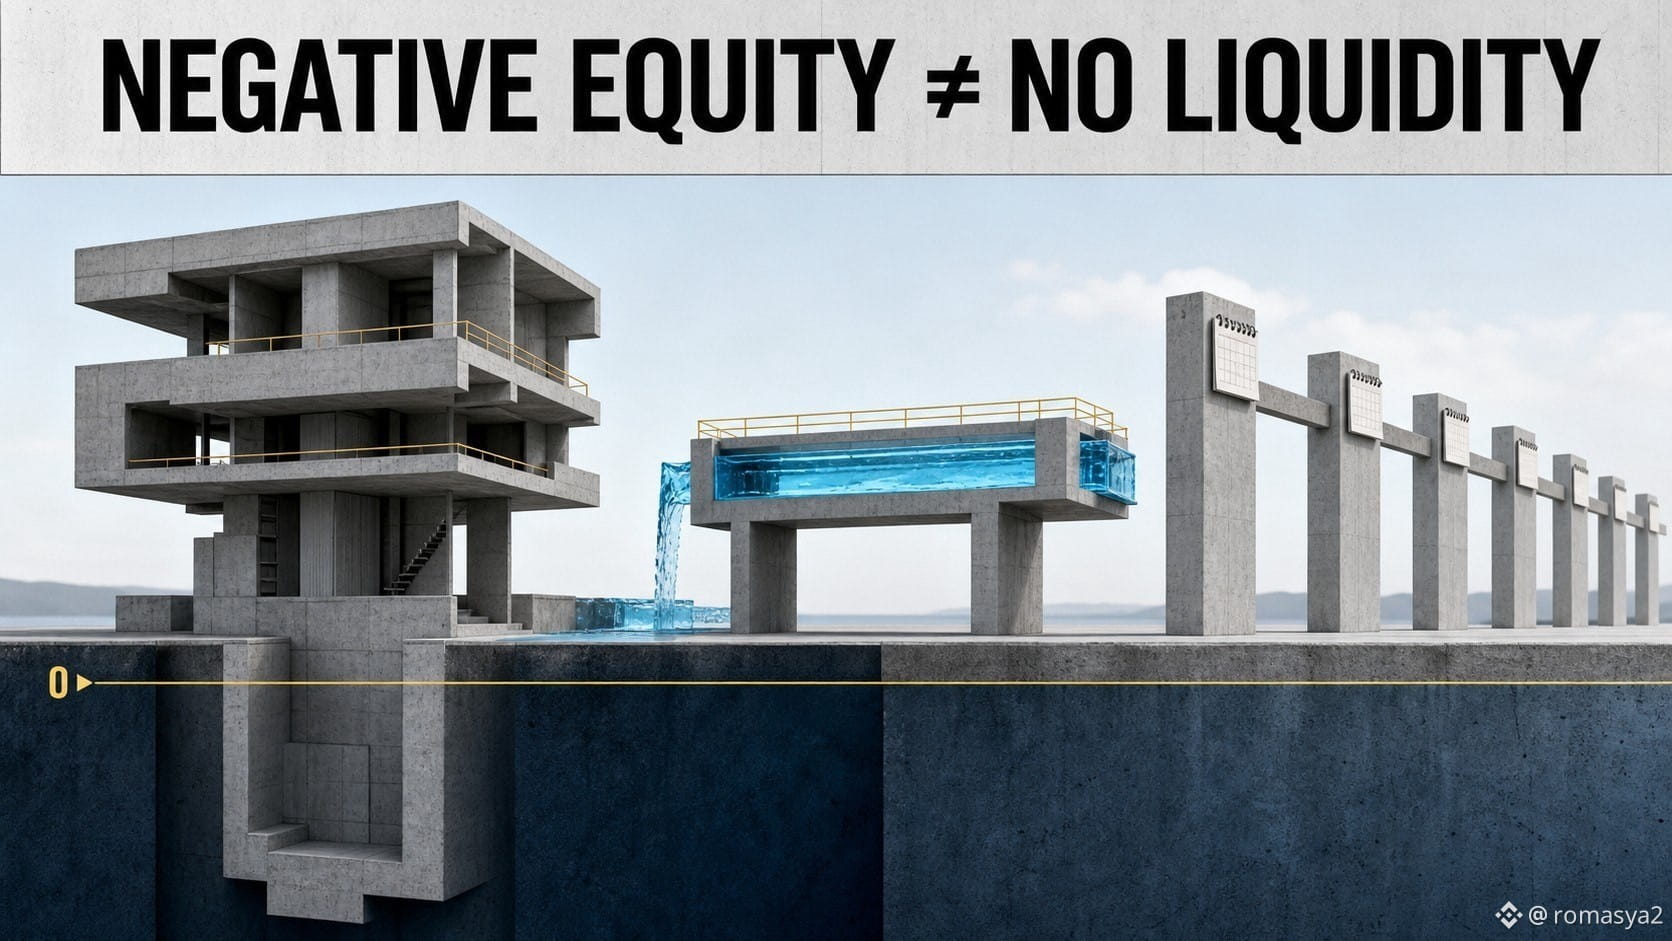
A negative equity line does not mean the company’s bank account is empty.
Dell reported a stockholders’ deficit in its FY2026 Form 10-K. Book equity is a cumulative accounting balance: assets minus liabilities after retained results, distributions, share repurchases and other accounting entries. It is not a live measure of cash available tomorrow, and it is not a market valuation.
That means two shortcuts can both fail:
“negative equity = immediate insolvency”
and
“positive cash flow = balance-sheet risk solved.”
For $DELLB, I would connect five statements:
1. cash and operating cash flow;
2. the statement of stockholders’ equity;
3. share repurchases and distributions;
4. debt and maturity schedule;
5. interest obligations and liquidity facilities.
The equity roll-forward explains how the deficit formed. The cash-flow statement explains current cash generation. The debt notes explain contractual timing.
Negative book equity is a prompt for deeper work—not a conclusion by itself.
Source checked: Dell Technologies FY2026 Form 10-K.
#bstockscis @BinanceCIS
Dell reported a stockholders’ deficit in its FY2026 Form 10-K. Book equity is a cumulative accounting balance: assets minus liabilities after retained results, distributions, share repurchases and other accounting entries. It is not a live measure of cash available tomorrow, and it is not a market valuation.
That means two shortcuts can both fail:
“negative equity = immediate insolvency”
and
“positive cash flow = balance-sheet risk solved.”
For $DELLB, I would connect five statements:
1. cash and operating cash flow;
2. the statement of stockholders’ equity;
3. share repurchases and distributions;
4. debt and maturity schedule;
5. interest obligations and liquidity facilities.
The equity roll-forward explains how the deficit formed. The cash-flow statement explains current cash generation. The debt notes explain contractual timing.
Negative book equity is a prompt for deeper work—not a conclusion by itself.
Source checked: Dell Technologies FY2026 Form 10-K.
#bstockscis @BinanceCIS